5.01 The principal auditor relies on the [equity investee] auditor's report for 2023, but the only [equity investee] audit report in the 10-K covers 2025 and 2024
Company B · a US-listed transportation and logistics company · Compliance or disclosure gap
In brief
The principal auditor's report says its opinion on the amounts for [equity investee], LLC ([equity investee]) rests solely on the report of the investee's own auditor, and it names [equity investee] equity income for 2025, 2024 and 2023, including [amount] for 2023. The only report of the investee's auditor included in the 10-K covers the investee's statements as of and for the years ended [date] and 2024. The report that covered 2023, included in the prior-year 10-K, is not in this filing.
The evidence, as filed
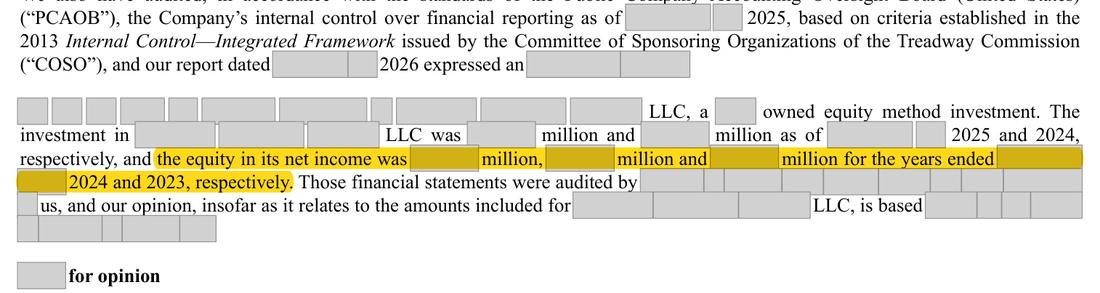
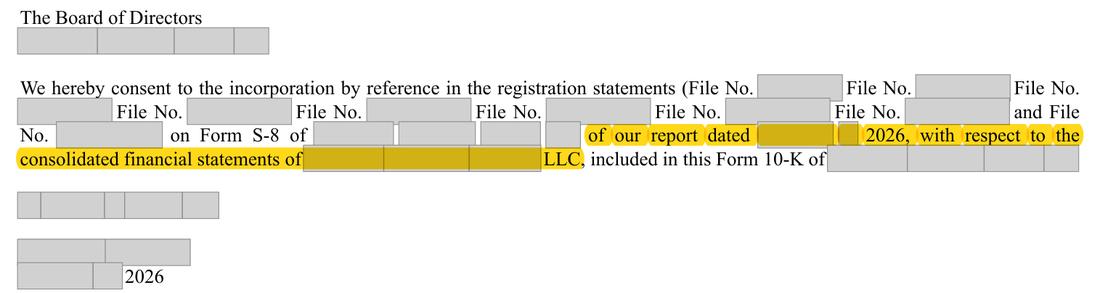
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Principal auditor refers to the investee's auditor for 2025, 2024 and 2023 (2023 equity income [amount]); the included [equity investee] auditor's report covers 2025 and 2024 only | A report of the investee's auditor covering every year for which the principal auditor refers to it (the prior report covering 2024 and 2023 included again, or a report covering all three years), or a principal auditor's report that refers only to the years the included report covers |
The rule
Regulation S-X Rule 2-05
the principal accountant elects to place reliance on the work of the other accountant and makes reference to that effect in his report, the separate report of the other accountant shall be filed
Version: Text in force at the date of this review · Source: 17 CFR 210.2-05, Examination of financial statements by more than one accountant ([n] FR [n], [date]), eCFR text
Why it applies here. For 2023 the opinion relied on is not in the filing. the investee's 2023 equity income of [amount] was 29.6% of 2023 pre-tax income of [amount]. In the prior-year 10-K the two reports matched.
Why it matters
- The 2023 column of the audited statements carries an opinion that depends on a report the reader cannot see.
- The staff could ask for the missing report by amendment; registration statements that incorporate this 10-K carry the same gap.
Exposure
A staff comment asking for the [equity investee] auditor's report covering 2023 to be filed by Form 10-K/A (with an updated consent), or for the principal auditor's report to be conformed.
Our workings
the principal auditor's report on the financial statements states that the investee's statements were audited by another firm and that its opinion, insofar as it relates to the amounts included for [equity investee], is based solely on that firm's report; it lists equity income from [equity investee] for 2025, 2024 and 2023. The statement of operations shows income from the equity method investment of [n] (thousand) for 2023. The [equity investee] auditor's report in the 10-K is dated [date] and opines on the investee's balance sheets as of [date] and 2024 and on the years then ended; Exhibit 23.2 consents only to that report.
the 2023 equity income was 29.6% of 2023 pre-tax income (workings). Prior-year comparison: in the fiscal 2024 10-K the principal auditor referred to the investee's auditor for 2024 and 2023 only, and the [equity investee] auditor's report included there covered exactly those two years.
in the fiscal 2025 10-K the reference was widened to three years without the [equity investee] auditor's report for the earliest year, so for 2023 the filing contains a referred-to opinion that the reader cannot see. Regulation S-X Rule 2-05 requires the separate report of the other accountant to be filed whenever the principal accountant places reliance on it and makes reference to that effect.
| Item | Figure | Source |
|---|---|---|
| 2023 income from equity method investment ([equity investee]) | [n] | Statement of operations, 2023 column |
| 2023 income before income taxes | [n] | Statement of operations, 2023 column |
| Share of 2023 pre-tax income | [n] / [n] = 29.6% | computed |
| Years the principal auditor refers to the investee's auditor | 2025, 2024, 2023 | Principal auditor's report |
| Years covered by the [equity investee] auditor's report filed | 2025, 2024 | [equity investee] auditor's report dated [date] |
Management’s best defense, and our reply
Management would say the [equity investee] auditor's report covering 2023 was filed with the fiscal 2024 10-K and remains publicly available, so no reader is deprived of it. The principal auditor might add that its mention of 2023 equity income only describes amounts it already relied on last year, and that the wording of its report is its own. However, Rule 2-05 attaches to each filing in which the principal accountant makes the reference, and the fiscal 2025 report makes it for 2023; nothing in the 10-K incorporates the earlier report by reference, and the prior-year filing shows the company and its auditors matching the reference to the years of the report included.
The fix
- Include the [equity investee] auditor's report covering 2023 (reissued, with Exhibit 23.2 naming it) alongside the 2026 report, or have the principal auditor's report refer to the investee's auditor only for the years covered by the report included; in the fiscal 2026 10-K include the [equity investee] auditor's reports for every year referred to.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The principal auditor's reference to the investee's auditor covers three years, including 2023 | Document | Form 10-K 2025, unnumbered page |
| 2 | The principal auditor places reliance on the investee's auditor and says so in its report | Document | Form 10-K 2025, unnumbered page |
| 3 | The only [equity investee] auditor's report in the 10-K covers 2025 and 2024 | Document | Form 10-K 2025, unnumbered page |
| 4 | That report is dated [date] | Document | Form 10-K 2025, page 53 |
| 5 | 2023 equity income from [equity investee] in the statement of operations | Document | Form 10-K 2025, page 55 |
| 6 | 2023 pre-tax income used for the share computed in the workings | Document | Form 10-K 2025, page 55 |
| 7 | The [equity investee] auditor's consent names only the 2026 report | Document | |
| 8 | The report covering the investee's 2023 statements was included in the prior-year 10-K | Document | Form 10-K 2024 (prior year), unnumbered page |
| 9 | That prior-year report is dated [date] | Document | Form 10-K 2024 (prior year), page 53 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Opinion on the Consolidated Financial Statements
- What is missing
- a report of the investee's auditor covering the investee's 2023 financial statements, the year for which the principal auditor also refers to that auditor
- Pages looked at
- p.50-53 (all auditors' reports) and unnumbered page (exhibit index); Exhibit 23.2
- Result
- '[audit firm]' hits unnumbered page (the Exhibit 23.2 consent row), unnumbered page (the principal auditor's reference) and p.53 (signature of the only [equity investee] auditor's report, which covers 2025 and 2024); 'We have served as [equity investee]' hits only p.53, the same report; '[date] and 2023' hits only unnumbered page (discontinued operations) and unnumbered page (income tax note), neither an auditor's report; '[date]' has no hits.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.