4.13 Generic risk factors sit inside the Financial Risks group in both years, with no 'General Risk Factors' caption at the end of Item 1A
Company B · a US-listed transportation and logistics company · SEC-style question
In brief
Regulation S-K Item 105(a) discourages risks that could apply to any registrant and, where they are presented, requires them at the end of the risk factor section under the caption 'General Risk Factors'. In both the fiscal 2024 and fiscal 2025 Forms 10-K, the closing part of Item 1A includes a factor on stock price volatility and, as its last factor, one on the inherent limitations of internal control, which are written in terms that apply to any company, but they are placed inside the 'Financial Risks' group and the caption 'General Risk Factors' does not appear anywhere in either report.
The evidence, as filed
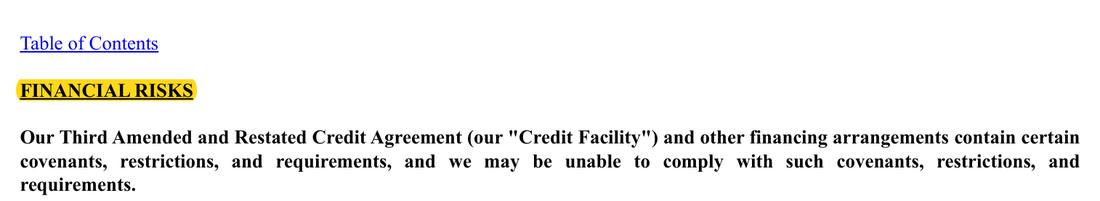
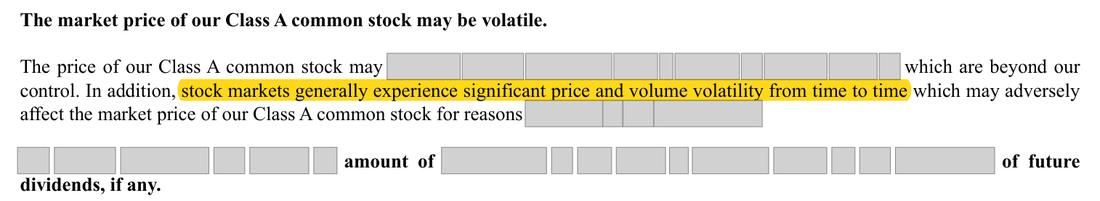
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Item 1A grouped as Strategic, Compliance, Operational and Financial Risks; the stock-price volatility factor ('stock markets generally experience significant price and volume volatility') and the internal-control limitations factor appear under 'Financial Risks'; no 'General Risk Factors' caption in either year. | Either omit the generic factors, or move them to the end of Item 1A under the caption 'General Risk Factors', or make them specific to the Company (for example, the effect of the dual-class structure on the Class A price). |
The rule
Regulation S-K Item 105(a)
The presentation of risks that could apply generically to any registrant or any offering is discouraged, but to the extent generic risk factors are presented, disclose them at the end of the risk factor section under the caption “General Risk Factors.”
Version: Text in force at the date of this review · Source: 17 CFR 229.105, Regulation S-K Item 105 (as amended by Release 33-10825)
Why it applies here. the two factors read as generic, so the structure Item 105(a) prescribes is not followed in either year; whether a factor is generic is, however, a judgment for the registrant, which is why this is put as a question.
Why it matters
A possible staff comment asking the Company to remove generic risk factors or move them under a 'General Risk Factors' caption at the end of Item 1A, normally answered by a future-filings undertaking.
Exposure
A presentation question; the realistic outcome, if the staff took the same view, is a comment letter and a change in the next Form 10-K, with no fine.
Our workings
Item 1A of the fiscal 2025 Form 10-K closes its last group, 'Financial Risks', with factors on the market price of the Class A stock and on internal control; the price factor says that stock markets generally experience price and volume volatility for reasons unrelated to performance, and the internal-control factor describes limitations of any control system. The prior-year Form 10-K presents the same two factors in the same place. A search of both reports finds no 'General Risk Factors' caption and no other heading for generic risks. Law: since the 2020 amendments, Item 105(a) says generic risk factors are discouraged but, to the extent presented, must be disclosed at the end of the section under the caption 'General Risk Factors'.
Management’s best defense, and our reply
The Company can argue that both factors are tailored: the stock-price factor follows factors on the controlling stockholders' voting power and [state] anti-takeover provisions that are specific to the Class A stock, and the internal-control factor refers to integrating controls in acquired companies, which reflects its acquisition strategy. Item 105(a) only discourages generic risks, and the same structure has been used in both years. That defense is tenable, which is why this is a question. However, the stock-price factor's operative sentence concerns stock markets generally and the internal-control factor opens with limitations common to every control system, so at least those passages read as generic and the caption Item 105(a) prescribes would apply to them.
The fix
- In the next Form 10-K either delete the stock-price volatility and internal-control limitation factors, tailor them to the Company (for example the dual-class voting structure and the trading volume of the Class A stock), or move them to the end of Item 1A under the caption 'General Risk Factors'.
Question for the company
Does management regard the stock-price volatility and internal-control limitation risk factors as specific to the Company, and if not, will the next Form 10-K present them at the end of Item 1A under the caption 'General Risk Factors' as Item 105(a) provides?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Fiscal 2025 10-K: the last group heading in Item 1A | Document | Form 10-K 2025, unnumbered page |
| 2 | Fiscal 2025 10-K: stock-price factor placed within Financial Risks | Document | Form 10-K 2025, unnumbered page |
| 3 | Fiscal 2025 10-K: the stock-price factor is written in terms that apply to any listed company | Document | Form 10-K 2025, page 24 |
| 4 | Fiscal 2025 10-K: internal-control limitations factor, the last factor in Item 1A, also generic | Document | Form 10-K 2025, page 24 |
| 5 | Prior-year 10-K: the same generic stock-price factor within Financial Risks | Document | Form 10-K 2024 (prior year), unnumbered page |
| 6 | Prior-year 10-K: the same internal-control factor, last in Item 1A | Document | Form 10-K 2024 (prior year), page 24 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- If we fail to maintain effective internal control over financial reporting
- What is missing
- a 'General Risk Factors' caption at the end of Item 1A grouping the generic risks
- Pages looked at
- p.26-24 (Item 1A, all group headings: Strategic, Compliance, Operational, Financial Risks) and the whole Form 10-K text
- Result
- no term hits anywhere in the fiscal 2025 Form 10-K
Absence check
- Document
- Form 10-K 2024 (prior year)
- Where it would appear
- If we fail to maintain effective internal control over financial reporting
- What is missing
- the same caption in the prior-year Item 1A
- Pages looked at
- Form 10-K 2024 (prior year) p.26-24 (Item 1A) and the whole prior-year Form 10-K text
- Result
- no term hits anywhere in the prior-year Form 10-K
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.