1.18 Note 9 leaves part of the 2025 additions to intangibles and goodwill unexplained
Company B · a US-listed transportation and logistics company · SEC-style question
In brief
Segment 2 customer relationships rose by [n] (thousand dollars) in 2025, an addition the Form 10-K never explains; the company's second-quarter Form 10-Q attributed [amount] to the [date] purchase [wording masked], whose only trace in the 10-K is its [amount] earn-out. Note 9 also says the assignment of goodwill and intangibles to segments 'was not complete' while its table assigns all of the [acquisition 4] goodwill to Segment 3, and it shows a further [n] of 'post-acquisition goodwill adjustments' with no explanation.
The evidence, as filed
7 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Note 9: Segment 2 customer relationships gross [n] (2025) vs [n] (2024); [acquisition 4] intangibles [n] account for the Segment 3 increase only. Goodwill rollforward: [acquisition 4] [n] and post-acquisition adjustments [n], both in Segment 3; narrative: assignment 'was not complete as of [date]'. | A description of the [date] asset purchase (consideration, the intangible acquired and its amortization period); either the amount of goodwill not yet assigned to a segment or a statement that the assignment is provisional; and the nature of the [n] adjustment. |
The rule
Acquisition, goodwill and intangibles disclosures
Why it applies here. the 10-K reader cannot tell what was bought in [date], what was paid beyond the earn-out, or how long the new customer relationship will be amortized; and the goodwill narrative and table appear to contradict each other. Whether the purchase was a business combination or an asset acquisition, and whether any goodwill is in fact unassigned, are matters only management can answer.
Why it matters
Readers cannot reconcile [n] of the year's intangible additions to any transaction described in the 10-K, nor tell whether any goodwill remains unassigned to a segment for impairment testing.
Exposure
A question: no exposure is asserted until management explains the items.
Our workings
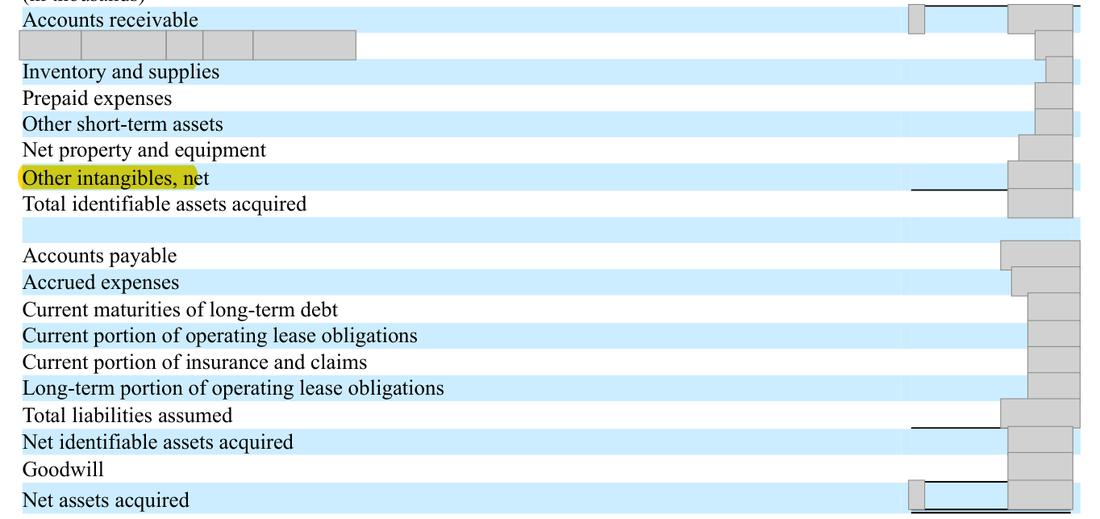
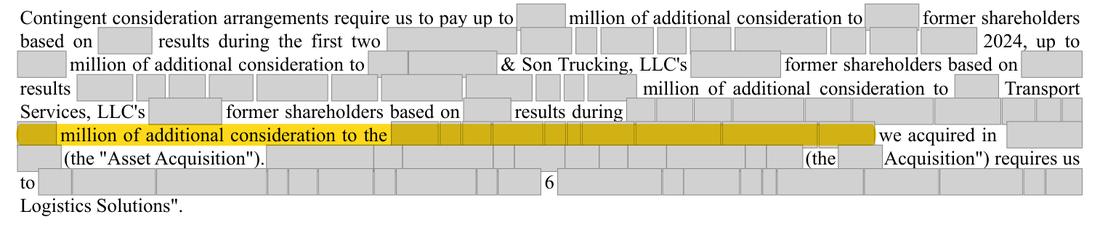
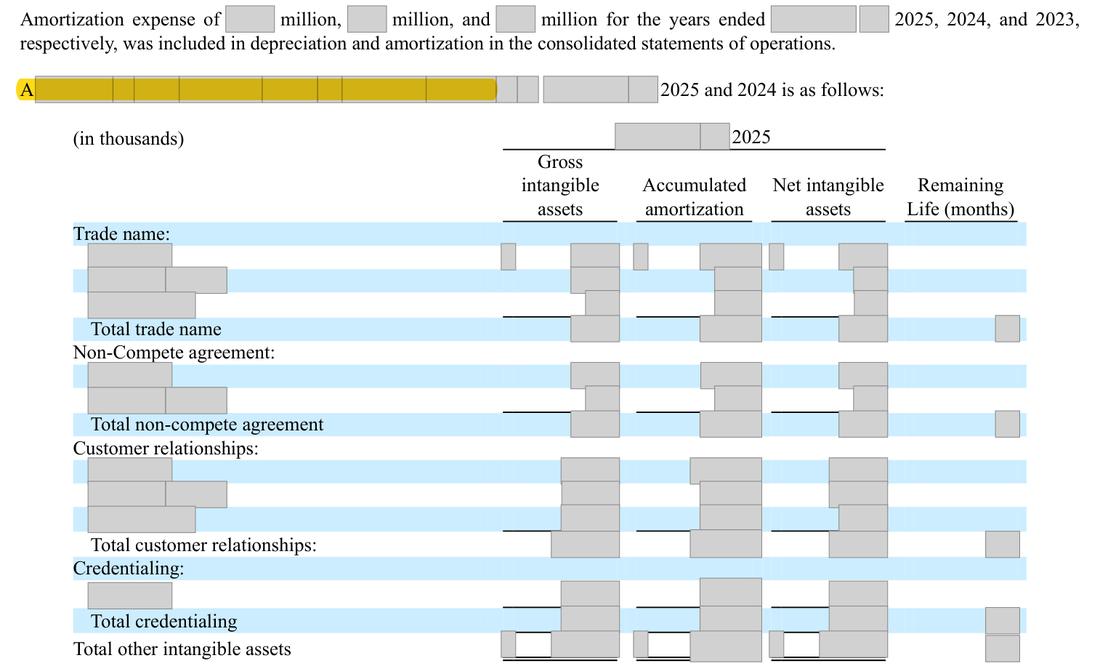
the intangible tables show Segment 2 customer relationships of [n] at [date] and [n] at [date]. The [acquisition 4] purchase price allocation recognizes intangibles of [n] (unnumbered page), which matches the Segment 3 increases. Note 3 mentions the [date] purchase only for its earn-out of up to [amount] (unnumbered page). The Form 10-Q for the quarter ended [date] states that an [amount] customer relationship was acquired for Segment 2 through that purchase; no such sentence is in the 10-K. Note 9 says the assignment of goodwill and intangibles to segments was not complete because of the [acquisition 4] acquisition, yet the goodwill table assigns the [n] of [acquisition 4] goodwill, plus a further [n] of post-acquisition adjustments, to Segment 3 (unnumbered page).
see workings.
| Check | Arithmetic (USD thousand) |
|---|---|
| Segment 2 customer relationships added in 2025 | [n] - [n] = [n] |
| Segment 3 customer relationships added | [n] - [n] = [n] |
| Segment 3 non-compete added | [n] - [n] = [n] |
| [acquisition 4] intangibles per allocation | [n] + [n] = [n] |
| Goodwill rollforward | [n] + [n] - [n] + [n] = [n] |
Management’s best defense, and our reply
The [date] purchase was small and was accounted for as an asset acquisition, for which the business combination disclosures do not apply, and it was described in the quarterly reports during the year. The 'not complete' sentence refers to the provisional [acquisition 4] allocation, which is shown in the segment the company expects, and [n] is immaterial. These explanations are plausible, which is why the points are put as questions. However, an [n] addition is large beside 2025 pre-tax income, the annual report must stand on its own without the Forms 10-Q, and the narrative and table on goodwill assignment say different things.
The fix
- Add to Note 9: 'In [date] we acquired the assets of a multi-stop distribution carrier for $x million in cash and up to [amount] of contingent consideration, recognizing an [amount] customer relationship in Segment 2 amortized over y years'; state the amount of goodwill (if any) not yet assigned, or delete the 'not complete' sentence; describe the [n] adjustment.
Question for the company
What consideration was paid for the [date] multi-stop distribution carrier assets, how was the purchase accounted for, and over what period is the [amount] customer relationship amortized? Was any goodwill unassigned to segments at [date], and what is the [n] post-acquisition goodwill adjustment?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Segment 2 customer relationships at [date] | Document | Form 10-K 2025, page 69 |
| 2 | Segment 3 customer relationships at [date] | Document | Form 10-K 2025, page 69 |
| 3 | Segment 3 non-compete at [date] | Document | Form 10-K 2025, page 69 |
| 4 | Segment 2 customer relationships at [date] | Document | Form 10-K 2025, unnumbered page |
| 5 | Segment 3 customer relationships at [date] | Document | Form 10-K 2025, unnumbered page |
| 6 | Segment 3 non-compete at [date] | Document | Form 10-K 2025, unnumbered page |
| 7 | [acquisition 4] intangibles recognized in the purchase price allocation | Document | Form 10-K 2025, unnumbered page |
| 8 | The [date] purchase appears in the 10-K only through its earn-out | Document | Form 10-K 2025, unnumbered page |
| 9 | Form 10-Q for the quarter ended [date] (filed [date]) identifies the intangible bought in [date] | Document | |
| 10 | Narrative says the segment assignment was incomplete | Document | Form 10-K 2025, unnumbered page |
| 11 | Goodwill by segment at the start of 2025 | Document | Form 10-K 2025, unnumbered page |
| 12 | All [acquisition 4] goodwill is assigned to Segment 3 | Document | Form 10-K 2025, unnumbered page |
| 13 | Segment 2 goodwill impairment in 2025 | Document | Form 10-K 2025, unnumbered page |
| 14 | A further [n] of post-acquisition goodwill adjustments, not explained | Document | Form 10-K 2025, unnumbered page |
| 15 | Goodwill by segment at [date] | Document | Form 10-K 2025, unnumbered page |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- A summary of other intangible assets, by reportable segment
- What is missing
- Any description of the [date] purchase: the consideration paid, the customer relationship acquired and its amortization period
- Pages looked at
- p.103-70 (policies and Notes 1-9), p.28-70 (MD&A)
- Result
- 'Asset Acquisition' and 'multi-stop' hit only unnumbered page, the earn-out terms and payments in Note 3; 'asset purchase' hits only unnumbered page, the [acquisition 4] agreement; '[n]' and 'unallocated' have no hits.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.