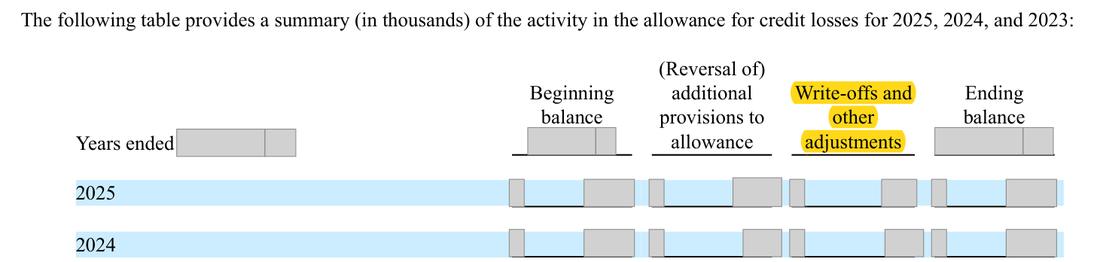
1.16 The 2025 allowance roll-forward shows a positive [n] under 'write-offs and other adjustments', so the allowance rose while provisions were reversed
Company B · a US-listed transportation and logistics company · SEC-style question
In brief
The allowance for credit losses on trade receivables rose from [n] to [n] in 2025 although the provision column shows a reversal of [n]. The increase comes from a positive [n] in a single column headed 'write-offs and other adjustments'; write-offs reduce an allowance, so the column must contain other additions larger than any write-offs. The note does not say what they are. The company files no Schedule II and relies on this note instead.
The evidence, as filed
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
2025 row: beginning [n], (reversal of) provisions ([n]), write-offs and other adjustments [n], ending [n]; write-offs, recoveries and other additions are combined in one net figure with no description. | Write-offs, recoveries and any other additions (for example allowances recognized on receivables acquired with [acquisition 4], or reclassifications) shown separately, with a short description of each non-provision addition. |
The rule
ASC 326-20-50-11 to 50-13 (credit-loss methodology and allowance activity; paraphrase, the Codification text is copyrighted)
Summary; FASB/IFRS text is copyrighted Describe how expected credit losses are estimated and why they changed, show allowance activity by portfolio segment, and (PBEs) credit quality and write-offs by vintage.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 326-20-50-11 to 50-13 (ASU 2016-13 as amended)
Regulation S-X Rule 5-04(c), Schedule II (valuation and qualifying accounts)
Schedule II—Valuation and qualifying accounts. The schedule prescribed by § [n]-09 shall be filed in support of valuation and qualifying accounts included in each balance sheet but not included in Schedule VI.
Version: Text in force at the date of this review · Source: Regulation S-X, 17 CFR 210.5-04(c), eCFR text as amended
Why it applies here. either the [n] includes an allowance brought in with an acquisition or a reclassification (which should be described, and for acquired non-deteriorated receivables would normally run through the provision column), or it nets recoveries against write-offs in a way the reader cannot see. The amounts are small against receivables of [n], but the [n] equals [n]% of the year's pre-tax income and the direction is unusual.
Why it matters
Readers cannot tell what increased the allowance in a year of net provision reversals, or whether an acquired allowance bypassed credit-loss expense; the note is the only valuation-and-qualifying-accounts disclosure in the 10-K.
Exposure
No penalty attaches to a question. The realistic outcome is a staff comment asking for the composition of the adjustment and a future-filings undertaking to split the column.
Our workings
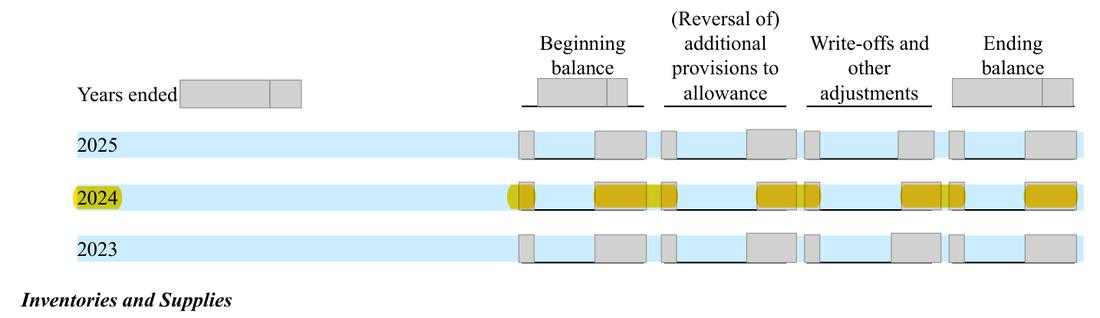
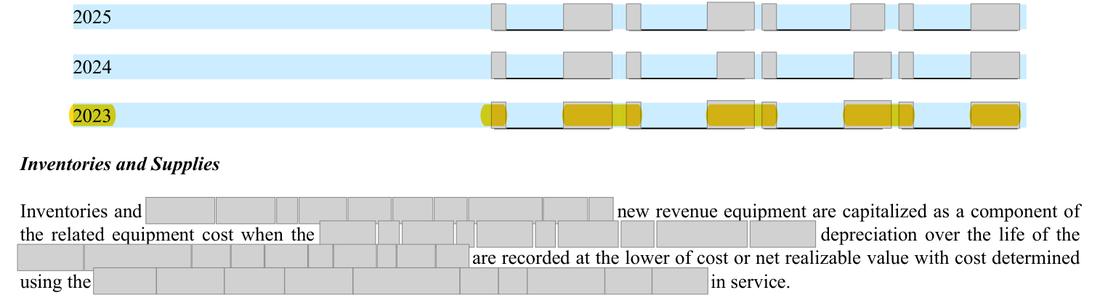
the roll-forward on unnumbered page shows for 2025 a beginning balance of [n], a reversal of provisions of [n], 'write-offs and other adjustments' of a positive [n] and an ending balance of [n]; in 2024 and 2023 the same column was negative ([n] and [n]), as write-offs normally are.
in [date] the company acquired [acquisition 4], taking on accounts receivable of [n] (unnumbered page).
Item 15 says financial statement schedules are omitted because the information is in the financial statements, so this note stands in for Schedule II (valuation and qualifying accounts), which separates additions charged to expense, additions charged to other accounts and deductions.
[n] - [n] + [n] = [n], and the allowance rose by [n] - [n] = [n] in a year with a net reversal of provisions. Law: the credit-loss disclosures require the activity in the allowance and why it changed; under the expected-loss model an allowance on acquired receivables that are not credit-deteriorated is recognized through credit-loss expense, not added directly to the allowance.
| Item | Computation | Result (USD thousand) |
|---|---|---|
| 2025 roll-forward | [n] - [n] + [n] = [n] | [n] |
| Increase in allowance in 2025 | [n] - [n] = [n] | [n] |
| Positive adjustment as % of pre-tax income | [n] / [n] = [n]% | [n]% |
Management’s best defense, and our reply
Management would say the amounts are small, below one-half of one percent of net receivables, and that combining write-offs with recoveries and minor reclassifications is a common presentation for a trade-receivable allowance. They would add that the information required by Schedule II is in substance given by the opening balance, the provision and the closing balance, and that any allowance on [acquisition 4] receivables was recorded within the measurement-period accounting for the acquisition.
The fix
- Split the column into 'Write-offs', 'Recoveries' and 'Other (describe)', and add a sentence such as: 'Other adjustments in 2025 include $X thousand of allowance recognized on receivables acquired in the [acquisition 4] Acquisition.'
Question for the company
What makes up the positive [n] shown under write-offs and other adjustments in the 2025 allowance roll-forward (write-offs, recoveries, an allowance on receivables acquired with [acquisition 4], a reclassification from another allowance), and was any allowance on acquired receivables recognized through credit-loss expense?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Write-offs and other adjustments share one column. | Document | Form 10-K 2025, unnumbered page |
| 2 | 2025: provisions reversed by [n] yet the allowance rises, through a positive [n]. | Document | Form 10-K 2025, unnumbered page |
| 3 | 2024: the same column is negative, as write-offs normally are. | Document | Form 10-K 2025, unnumbered page |
| 4 | 2023: the column is again negative. | Document | Form 10-K 2025, unnumbered page |
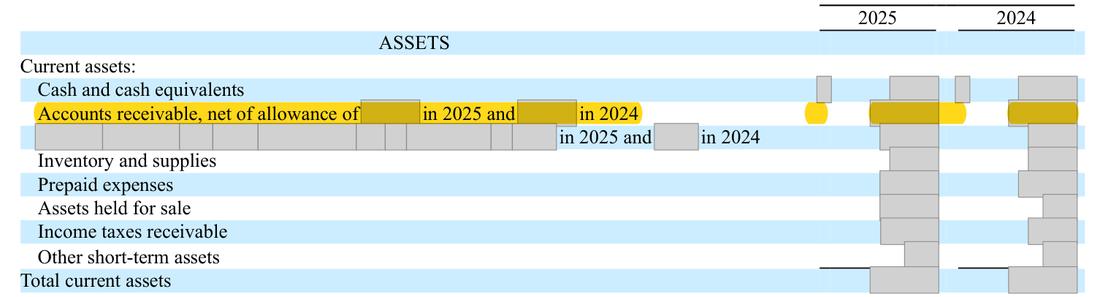
| 5 | The allowance and net receivables on the balance sheet. | Document | Form 10-K 2025, unnumbered page |
| 6 | Receivables acquired with [acquisition 4] in [date]. | Document | Form 10-K 2025, unnumbered page |
| 7 | No Schedule II is filed; the note stands in for it. | Document | Form 10-K 2025, unnumbered page |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.