1.09 Dividend restrictions are named but not quantified, and the share of retained earnings that is undistributed [equity investee] earnings is not stated
Company B · a US-listed transportation and logistics company · Compliance or disclosure gap
In brief
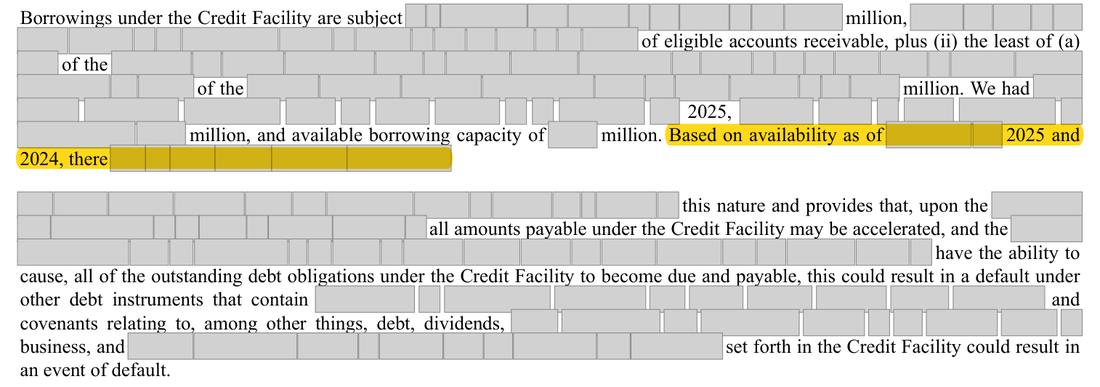
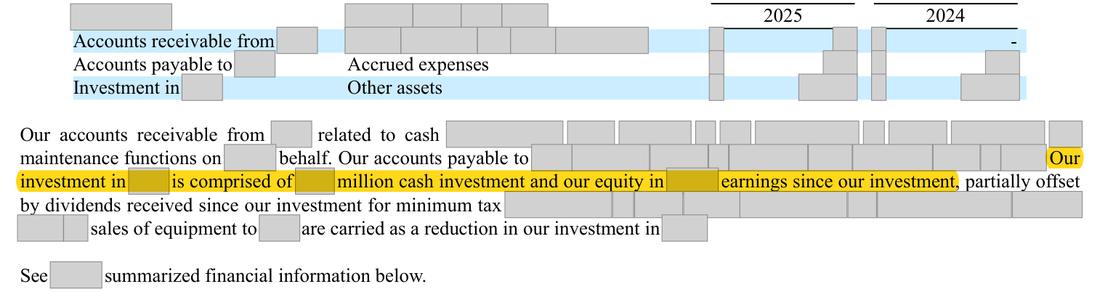
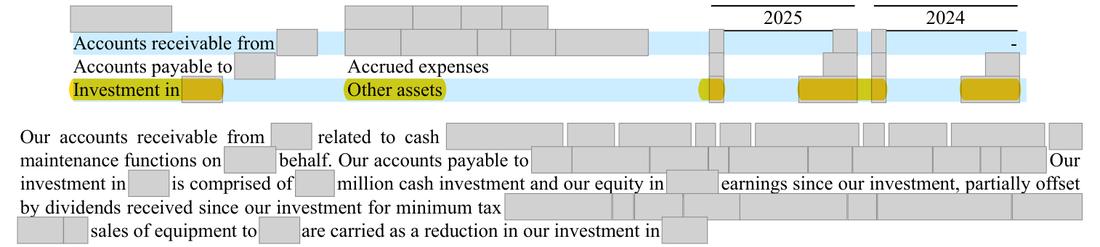
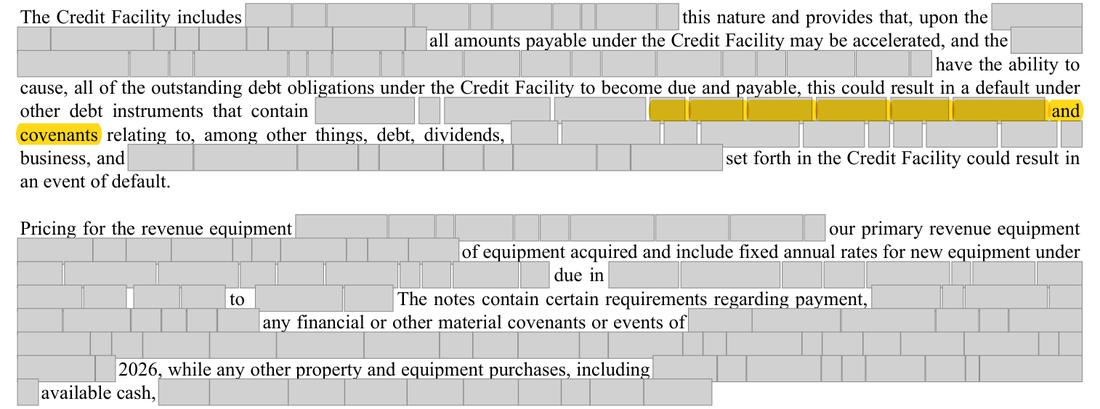
Regulation S-X requires the notes to describe the most significant restrictions on paying dividends, with their pertinent provisions and the amount of retained earnings restricted or free, and to state how much of consolidated retained earnings is undistributed earnings of equity-method investees. The debt note says only that the Credit Facility contains covenants relating to dividends, among other things. Item 5 adds only that the payment of cash dividends is "currently limited by our financing arrangements", without the provisions or an amount. The [equity investee] note says the [amount] investment is a [amount] cash investment plus accumulated equity earnings, but does not give the undistributed amount, which works out at about [amount], or [n]% of retained earnings of [amount]. The prior-year 10-K has the same gaps.
The evidence, as filed
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Dividend covenants mentioned with no provisions and no amount of retained earnings restricted or free; undistributed earnings of the [n]%-owned [equity investee] within retained earnings not stated, in either year. | Note 10 describes the dividend restriction (for example the availability or fixed-charge test that would limit dividends) and states the retained earnings restricted or free at year end; Note 13 (or the equity note) states the amount of consolidated retained earnings that represents undistributed [equity investee] earnings. |
The rule
Regulation S-X Rule 4-08(e)(1) and (e)(2)
(1) Describe the most significant restrictions on the payment of dividends by the registrant, indicating their sources, their pertinent provisions, and the amount of retained earnings or net income restricted or free of restrictions.
Version: Text in force at the date of this review · Source: 17 CFR 210.4-08(e), as in force for fiscal 2024 and 2025
Regulation S-X Rule 4-08(e)(2)
(2) Disclose the amount of consolidated retained earnings which represents undistributed earnings of 50 percent or less owned persons accounted for by the equity method.
Version: Text in force at the date of this review · Source: 17 CFR 210.4-08(e), as in force for fiscal 2024 and 2025
Why it applies here. Neither the provisions, an amount restricted or free, nor the undistributed [equity investee] earnings are given, in this or the prior-year Form 10-K.
Why it matters
- Readers cannot tell how much of retained earnings is available for dividends and buy-backs, at a company paying a regular quarterly dividend.
- A staff comment and future-filings undertaking are the realistic outcome; the statements themselves do not change.
Exposure
A staff comment and a future-filings undertaking are the realistic consequences; no change to the statements.
Our workings
Note 10 states that the Credit Facility contains restrictions and covenants relating to debt, dividends, liens, acquisitions and dispositions and affiliate transactions, and that based on availability at the two year ends there was no fixed charge coverage requirement. No provision of the dividend restriction and no amount restricted or free is given. Item 5 (p.26) states that the payment of cash dividends is currently limited by the Company's financing arrangements, so a restriction is in operation, but it too gives no provision and no amount. Note 13 says the investment in [equity investee] comprises a [amount] cash investment and the company's equity in the investee's earnings since the investment, less distributions, and that [amount] of deferred gains reduce the investment; the investment is [n] and retained earnings are [n] (USD thousand). The company paid quarterly dividends throughout 2025. A search of the whole filing finds no amount of retained earnings restricted or free and no undistributed-earnings figure. The prior-year 10-K uses the same wording.
undistributed [equity investee] earnings are about [n] - [n] + [n] = [n], which is [n] / [n] = [n]% of retained earnings.
both elements of the dividend-restriction rule are absent; the undistributed-earnings figure can only be approximated from the note, and the restriction cannot be judged without its provisions or an amount, which matters for a company paying a regular dividend and buying back shares.
| Step | Computation | Result (USD thousand) |
|---|---|---|
| Cash investment in [equity investee] | [n] x [n] = [n] | [n] |
| Deferred gains carried against the investment | [n] x [n] = [n] | [n] |
| Approximate undistributed [equity investee] earnings in retained earnings | [n] - [n] + [n] = [n] | [n] |
| Share of consolidated retained earnings | [n] / [n] = [n]% | [n]% |
| 2025 dividends per share declared | [n] x 4 = [n] | [amount] per share |
| Requirement | Where | Status |
|---|---|---|
| (e)(1) most significant dividend restrictions: sources | Note 10, p.72 (Credit Facility) | Given |
| (e)(1) pertinent provisions of the restriction | Note 10, p.72: 'covenants relating to ... dividends' only | Absent |
| (e)(1) amount of retained earnings or net income restricted or free | Searched whole filing | Absent |
| (e)(2) consolidated retained earnings representing undistributed earnings of equity-method investees | Note 13, unnumbered page: components named, amount not given | Absent |
| (e)(3) restrictions on subsidiaries' transfers of funds and restricted net assets, when material | Not determinable from the filing (holding company; insurance subsidiary) | Not tested: needs the Credit Facility terms |
Management’s best defense, and our reply
Management could say the Credit Facility only limits dividends if availability falls below a threshold, which it did not, so nothing was restricted and there was no amount to give; and that readers can derive the undistributed [equity investee] earnings from the investment balance and the [amount] cash investment given in Note 13. They could add that the auditor has accepted the wording for years. However, the Company's own Item 5 says the payment of cash dividends is currently limited by its financing arrangements, so a restriction is in operation; the rule asks for its pertinent provisions and the amount restricted or free, and 'none restricted' would itself be the required statement. A figure that the reader has to approximate, with deferred gains and distributions netted, is not the disclosure the rule requires.
The fix
- Add to Note 10 the dividend provisions of the Credit Facility (the conditions under which dividends are limited) and the retained earnings restricted or free at year end (or a statement that none is restricted); add to Note 13 'Consolidated retained earnings include $[x] million of undistributed earnings of [equity investee].'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Dividend restriction named, with no provisions and no amount | Document | Form 10-K 2025, page 72 |
| 2 | The only covenant mechanics given relate to availability and fixed charge coverage | Document | Form 10-K 2025, page 72 |
| 3 | Components of the [equity investee] investment named; undistributed amount not given | Document | Form 10-K 2025, unnumbered page |
| 4 | [equity investee] investment [n] | Document | Form 10-K 2025, unnumbered page |
| 5 | Deferred gains of [n] reduce the investment | Document | Form 10-K 2025, page 75 |
| 6 | Consolidated retained earnings [n] | Document | Form 10-K 2025, page 54 |
| 7 | Regular quarterly dividends paid in 2025 | Document | Form 10-K 2025, page 78 |
| 8 | Item 5 says a dividend limit is in operation, with no provisions and no amount | Document | Form 10-K 2025, page 26 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- The Credit Facility contains certain restrictions and covenants
- What is missing
- the pertinent provisions of the dividend restriction and the amount of retained earnings or net income restricted or free of restrictions
- Pages looked at
- p.41, [n], 64-38, 71-72, [n]
- Result
- Only the added term hits: Item 5 on p.26 says the payment of cash dividends is currently limited by the financing arrangements, which confirms a limit is in operation but gives no provision and no amount. None of the other terms hits anywhere in the filing. The risk factor on unnumbered page repeats that the Credit Facility has covenants relating to dividends, and p.24 says dividends depend on covenants among other factors; neither gives a provision or an amount.
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Our investment in [equity investee] is comprised of
- What is missing
- the amount of consolidated retained earnings that represents undistributed earnings of [equity investee]
- Pages looked at
- p.54, [n], 131-133
- Result
- None of the terms hits anywhere in the filing.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.