7.06 Wrong note cross-reference for income taxes, and superseded 'lower of cost or market' wording in the inventory policy
Company A · a US-listed consumer leisure company · Drafting slip
In brief
Item 7 and Note 1 both say the new income-tax disclosures are in the 'income tax note (Note 10)'. Income taxes are Note 9; Note 10 is Commitments and License Rights. Separately, the inventory policy says inventories are stated at 'the lower of cost or market' while they are costed first-in, first-out, for which the measure is the lower of cost and net realizable value.
The evidence, as filed
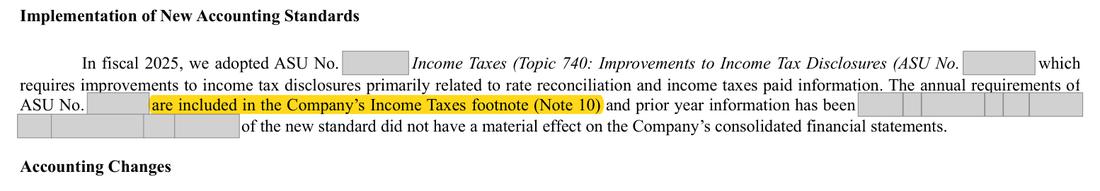
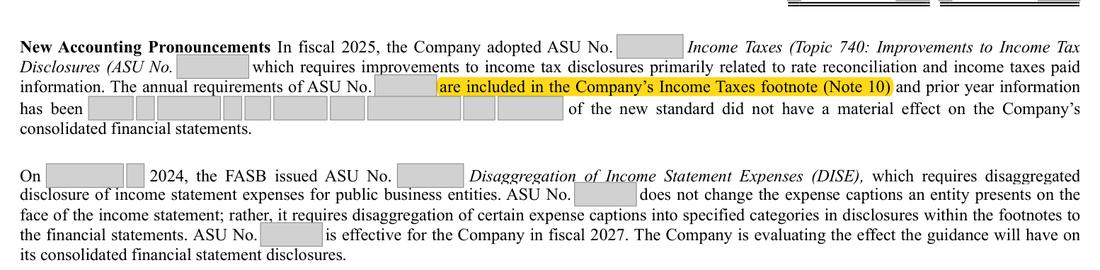
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
'income tax note (Note 10)' in Item 7 and in Note 1; inventory 'stated at the lower of cost or market' with first-in, first-out costing | 'income tax note (Note 9)'; inventory 'stated at the lower of cost and net realizable value' |
Why it matters
A reader following the cross-reference lands on the commitments note; the inventory wording describes a measure that does not apply to first-in, first-out inventories.
Exposure
Wording only; no amount affected.
Our workings
the two cross-references point to Note 10, whose heading is Commitments and License Rights; the income-tax note, with the new rate reconciliation, is headed Note 9, and the balance sheet, the statement of operations and the Note 1 tax policy all cite Note 9.
the inventory policy uses the 'lower of cost or market' phrase, which since the 2015 simplification of inventory measurement applies only to last-in, first-out and retail-method inventories; first-in, first-out inventories are measured at the lower of cost and net realizable value.
both are wording slips; nothing indicates a measurement difference.
Management’s best defense, and our reply
Management would say the note numbers changed when the notes were renumbered and the reader can find the tax note from the index, and that inventories are small and in practice written down to net realizable value. The answer: both points are accepted as cosmetic, which is why they are drafting slips, but the cross-reference is wrong in two places and the policy wording should describe the measure actually required for first-in, first-out inventories.
The fix
- Change both cross-references to 'Note 9' and the inventory policy to 'stated at the lower of cost and net realizable value'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Item 7 points to Note 10 for the income-tax disclosures | Document | Form 10-K 2025, page 49 |
| 2 | Note 1 repeats the Note 10 cross-reference | Document | Form 10-K 2025, page 64 |
| 3 | Income taxes are Note 9 | Document | Form 10-K 2025, page 78 |
| 4 | Note 10 is Commitments and License Rights | Document | Form 10-K 2025, page 81 |
| 5 | Inventory policy: 'lower of cost or market' wording with first-in, first-out costing | Document | Form 10-K 2025, page 60 |
| 6 | Prior-year inventory policy: the same superseded measure for first-in, first-out inventories | Document | Form 10-K 2024 (prior year), page 60 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.