2.02 Equity compensation plan table counts only stock options; outstanding performance and restricted stock units are left out of column (a)
Company A · a US-listed consumer leisure company · Compliance or disclosure gap
In brief
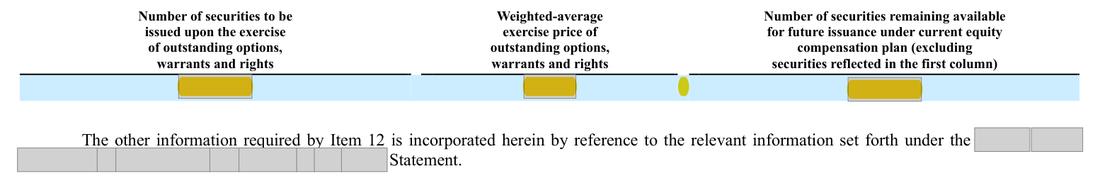
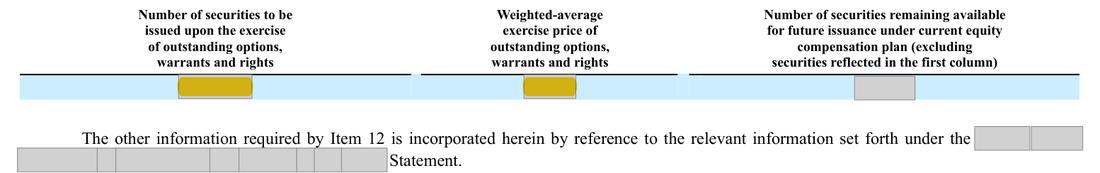
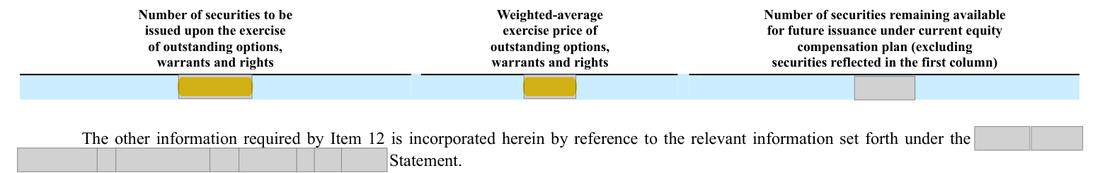
The Item 12 table shows [n] securities to be issued on exercise of outstanding options, warrants and rights, at a weighted-average price of [amount]. Both figures are the stock options alone (Note 7: [n] options outstanding at [amount]). Note 7 also shows [n] restricted stock units and [n] performance stock units outstanding, payable in common stock, which are neither in the table nor footnoted. The SEC staff's interpretation of Item 201(d) says shares issuable under performance share awards must be reported in column (a), with a footnote on column (b). The omitted units are [n]% of the column, and the prior-year table was built the same way.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Column (a) [n] = options only; restricted stock units ([n]) and performance stock units ([n]) payable in shares are omitted without a footnote, in both years. | Column (a) including all outstanding units to be settled in shares ([n] + [n] + [n] = [n]), with a footnote describing the units and stating that the weighted-average exercise price in column (b) excludes them (and, if useful, that performance units are counted at target). |
The rule
Regulation S-K Item 201(d)(2)(i)
The number of securities to be issued upon the exercise of outstanding options, warrants and rights (column (a));
Version: Text in force at the date of this review · Source: 17 CFR 229.201(d)(2)(i), as amended
SEC Division of Corporation Finance, Regulation S-K Compliance and Disclosure Interpretation, Question [n]
Shares that may be issued under performance share awards if specified targets are met ( i.e. , an award denominated in shares has been made, but no shares will be issued until the performance targets are met), and shares credited as phantom shares under a deferred compensation plan that will be issued as actual shares upon termination of employment, must be reported in column (a).
Version: Text in force at the date of this review · Source: SEC Division of Corporation Finance, Compliance and Disclosure Interpretations: Regulation S-K, Question [n] ([date])
Why it applies here. Item 201(d)(2)(i) asks in column (a) for securities to be issued upon the exercise of outstanding options, warrants and rights. The staff's Regulation S-K interpretation on performance share awards answers the grey area for full-value awards: shares that may be issued under performance share awards, and phantom shares that will be issued as actual shares, must be reported in column (a), with a footnote explaining that column (b) does not take them into account. Restricted stock units settled in shares are the same kind of award denominated in shares with no shares yet issued. By contrast, the companion interpretation on restricted stock excludes shares already issued subject to forfeiture, so the [n] restricted shares in Note 7 are rightly left out. The omission therefore concerns the units only, and it understates the dilution the table exists to show.
Why it matters
Readers using the table to gauge dilution from equity plans see [n] fewer shares than will be issued if the units vest (at target), and column (b) carries no footnote.
Exposure
No fine. The realistic consequence is a staff comment asking for the units to be added to column (a), with a footnote, in future filings.
Our workings
the Item 12 table gives [n] in column (a) and [amount] in column (b); Note 7 gives [n] options outstanding at a weighted-average exercise price of [amount], so the column is the options alone.
Note 7 shows [n] restricted stock units and [n] performance stock units outstanding at [date], both payable in common stock.
[n] + [n] = [n] units, [n]% of column (a) (workings).
| Item | Thousand units | Source |
|---|---|---|
| Options outstanding (column (a) as printed) | [n] | Note 7 |
| Restricted stock units outstanding | [n] | Note 7 |
| Performance stock units outstanding | [n] | Note 7 |
| Units not in column (a) | [n] + [n] = [n] | |
| Share of column (a) | [n] / [n] = [n]% | |
| Column (a) including the units | [n] + [n] = [n] |
Management’s best defense, and our reply
Column (a) speaks of securities issued 'upon the exercise' of options, warrants and rights; restricted and performance stock units are not exercised, so the company can read the column as limited to exercisable instruments, and column (b) cannot include them anyway. The performance units may also settle at fewer shares than target, and the units are fully described in Note 7. However, the staff's published interpretation [n] says shares issuable under performance share awards must be in column (a), with a footnote on column (b) and, where target overstates dilution, a footnote saying so; the units are shares to be issued, unlike issued restricted stock, so the company's reading is not one the staff accepts.
The fix
- Include the units in column (a) and footnote column (b): 'Includes [n] restricted stock units and [n] performance stock units (at target); the weighted-average exercise price excludes these units, which have no exercise price.'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Item 12 table: column (a) [n] at [amount] | Document | Form 10-K 2025, page 86 |
| 2 | Note 7: options outstanding [n] at [amount] - the same figures as the table | Document | Form 10-K 2025, page 73 |
| 3 | Note 7: [n] restricted stock units outstanding | Document | Form 10-K 2025, page 74 |
| 4 | Restricted stock units are settled in common stock | Document | Form 10-K 2025, page 74 |
| 5 | Note 7: [n] performance stock units outstanding | Document | Form 10-K 2025, page 75 |
| 6 | Prior-year table: column (a) equals the [n] options alone | Document | Form 10-K 2024 (prior year), page 85 |
| 7 | Note 7: [n] shares of restricted stock outstanding, already issued subject to forfeiture and rightly outside the table | Document | Form 10-K 2025, page 74 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Security Ownership of Certain Beneficial Owners and Management and Related Shareholder Matters
- What is missing
- the outstanding restricted and performance stock units in column (a) of the equity compensation plan table, or a footnote explaining their exclusion
- Pages looked at
- p.86 (Item 12 table and text), p.72-75 (Note 7)
- Result
- 'restricted stock units' and 'performance stock units' hit only p.62-63 (earnings per share policy and dilution table), p.72 (treasury share reissue) and p.74-75 (Note 7 award activity), none of which is the Item 12 table; 'warrants and rights' hits only the Item 12 column headings on p.86; 'excludes restricted' has no hit, so no footnote explains the exclusion.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.