2.01 The proxy says every director and executive officer filed Section 16 reports on time in fiscal 2025, but four Forms 4 were filed late
Company A · a US-listed consumer leisure company · Compliance or disclosure gap
In brief
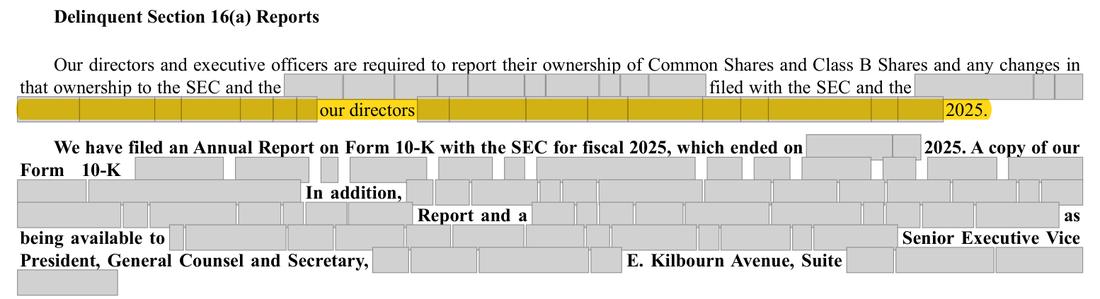
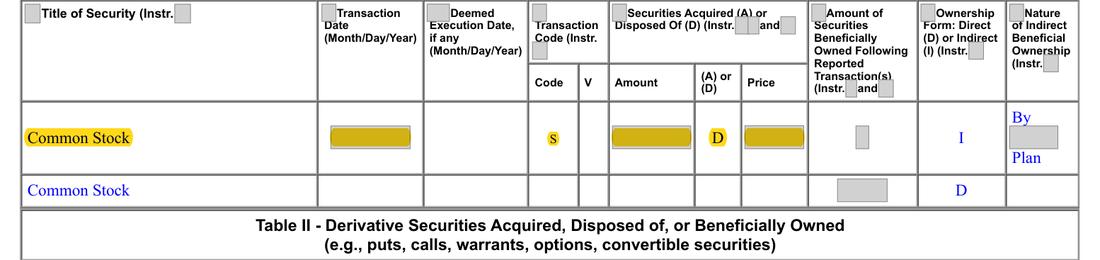
The 2026 proxy statement, which supplies Part III of this Form 10-K, states that all directors and executive officers complied with their Section 16(a) filing requirements for fiscal 2025. EDGAR shows four Forms 4 for fiscal 2025 transactions filed after the two-business-day deadline: two by the division presidents for May and [date] sales, filed [n] and 10 business days late, and two by the Chief Executive Officer and a director for a [date] share exchange, filed one business day late; those two forms carry five transaction lines between them, including a same-day gift of [n] shares by the director. Item 405 of Regulation S-K requires each late filer, the number of late reports and the number of late transactions to be named.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
'we believe that all of our directors and executive officers have complied with the requirements for fiscal 2025'; four Forms 4 for fiscal 2025 transactions filed [n], 1 and 1 business days after their due dates. | Under the caption 'Delinquent Section 16(a) Reports', each of the four reporting persons with the number of late reports (one each) and late transactions (one, one, two and three), placed under a caption that Item 10 of the Form 10-K incorporates. |
| What we checked. Every Form 3, 4 and 5 on EDGAR for the company from [date] to today (filing date against transaction date, US federal holidays excluded); the four late Forms 4 as rendered by EDGAR; the proxy statement's Item 405 paragraph and the captions Item 10 of the 10-K incorporates. | |
The rule
Regulation S-K Item 405(a)(1)
Under the caption “Delinquent Section 16(a) Reports,” identify each person who, at any time during the fiscal year, was a director, officer, beneficial owner of more than ten percent of any class of equity securities of the registrant
Version: Text in force at the date of this review · Source: 17 CFR 229.405 (eCFR, as amended to 2019; in force for fiscal 2025)
Regulation S-K Item 405(a)(2)
For each such person, set forth the number of late reports, the number of transactions that were not reported on a timely basis, and any known failure to file a required form.
Version: Text in force at the date of this review · Source: 17 CFR 229.405 (eCFR, as amended to 2019; in force for fiscal 2025)
Form 4 General Instruction 1(a)
This Form must be filed before the end of the second business day following the day on which a transaction resulting in a change in beneficial ownership has been executed
Version: Text in force at the date of this review · Source: Form 4 (SEC [n]), General Instructions (official copy, sec.official text)
Why it applies here. Item 405(a) requires identification of every reporting person who failed to file on a timely basis during the fiscal year, with the number of late reports and transactions. Four late reports covering seven transaction lines by three officers and one director fall within fiscal 2025 ([date] to [date]), so the statement that all complied is inaccurate and the Item 405 list of late filers has to be given.
Why it matters
Part III understates the Section 16 record of fiscal 2025: four late reports by three officers and one director go unnamed, and the statement that all complied is inaccurate.
Exposure
No fixed penalty for the registrant. Realistic consequence: a staff comment and a corrected list in the next proxy statement; Item 405 also allows the late reports to be listed once in the next filing.
Our workings
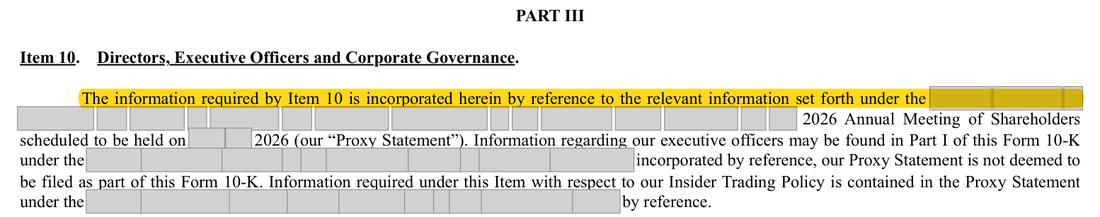
The 2026 proxy statement, under 'Other Matters', says that based on a review of reports filed and representations, all directors and executive officers complied with the Section 16(a) requirements for fiscal 2025. The Forms 4 on EDGAR show: the President of the Company venues reported a [date] sale of [n] shares held in the retirement savings plan in a Form 4 signed [date]; the President of the Company lodging properties & properties reported a [date] sale of [n] plan shares in a Form 4 signed [date]; the Chief Executive Officer and a director reported a [date] exchange of [n] shares of Common Stock for [n] shares of Class B Common Stock between them in Forms 4 filed [date]; the director's form also reports a gift of [n] shares of Common Stock on the same day, so the two forms carry two and three transaction lines. Item 10 of the 10-K incorporates the proxy proxy sections on director elections, the board and Governance'; the Item 405 paragraph sits under 'Other Matters'.
Form 4 is due before the end of the second business day after execution. The due dates and business days late are in the workings; for the two plan sales the workings also apply the most generous basis (a deemed execution date up to three business days after the trade), and both remain late.
| Reporting person (role) | Transaction | Due (2 business days) | Filed | Business days late |
|---|---|---|---|---|
| President, the Company venues | [date] sale, [n] plan shares (1 line) | [date] | [date] | [n] (on a deemed date of [date]: due [date], [n] late) |
| President, the Company lodging properties & properties | [date] sale, [n] plan shares (1 line) | [date] | [date] | [n] (on a deemed date of [date]: due [date], 7 late) |
| Chief Executive Officer | [date]: [n] Common Stock disposed and [n] Class B acquired (2 lines) | [date] | [date] | 1 |
| Director | [date]: [n] Common Stock acquired, [n] Common Stock gift, [n] Class B disposed (3 lines) | [date] | [date] | 1 |
| Total | 4 late reports; transaction lines 1 + 1 + 2 + 3 = 7 | 1 + 1 + 1 + 1 = 4 reports |
Management’s best defense, and our reply
The company may say that Item 405(b) lets it rely on the forms filed and on written representations, that the two plan sales were retirement-plan fund transfers reported once the plan administrator told the officers (and, if they were non-discretionary plan transactions, may not have needed a Form 4 at all), and that the September exchange was one business day late between two family members with no market effect. It may add that Item 405 asks only for a list, not an explanation, and that the amounts are small. The answer: the reliance permitted by Item 405(b)(1) is a review of the Forms 3 and 4 filed during the year, and those forms show the execution and signature dates on their face; even allowing the maximum deemed execution date for plan transactions the two sales were [n] and 7 business days late; the reporting persons themselves coded the plan sales 'S', a sale not exempt under the plan rules, rather than a discretionary plan transaction or a voluntary early report; and even setting the plan sales aside, the two September forms were one business day late on their face. Item 405 has no size or materiality threshold, so the statement that all complied cannot stand.
The fix
- In the 2027 proxy statement (or a note in the next Form 10-K) list the four late reports of fiscal 2025, for example: 'Due to administrative oversight, one Form 4 for each of [the four reporting persons], reporting one, one, two and three transactions respectively, was filed late'; build the Item 405 review from the EDGAR filing dates rather than representations alone; and add 'Other Matters' (or a 'Delinquent Section 16(a) Reports' caption) to the captions Item 10 incorporates.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The proxy statement's Item 405 statement for fiscal 2025 | Document | |
| 2 | President of the Company venues: sale executed [date] | Document | |
| 3 | That Form 4 was signed [date] | Document | |
| 4 | President of the Company lodging properties & properties: sale executed [date] | Document | |
| 5 | That Form 4 was signed [date] | Document | |
| 6 | Chief Executive Officer: exchange executed [date] | Document | |
| 7 | That Form 4 was signed and filed [date] | Document | |
| 8 | Director: the other side of the [date] exchange | Document | |
| 9 | That Form 4 was signed and filed [date] | Document | |
| 10 | Item 10 of the 10-K incorporates named proxy captions | Document | Form 10-K 2025, page 86 |
| 11 | Chief Executive Officer: the Class B Common Stock acquired in the same exchange (second transaction line) | Document | |
| 12 | Director: a gift of [n] shares on the same day, reported on the same late form | Document | |
| 13 | Director: the Class B Common Stock disposed of in the exchange (third transaction line) | Document |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.