1.07 Treasury stock: fiscal 2025 cash paid is [amount] less than the net movement in the statement of equity
Company A · a US-listed consumer leisure company · SEC-style question
In brief
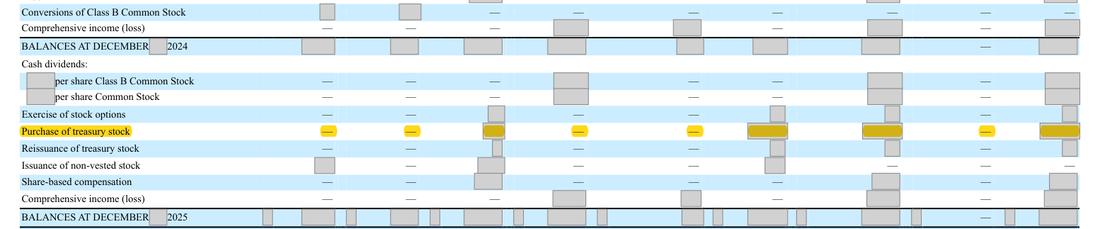
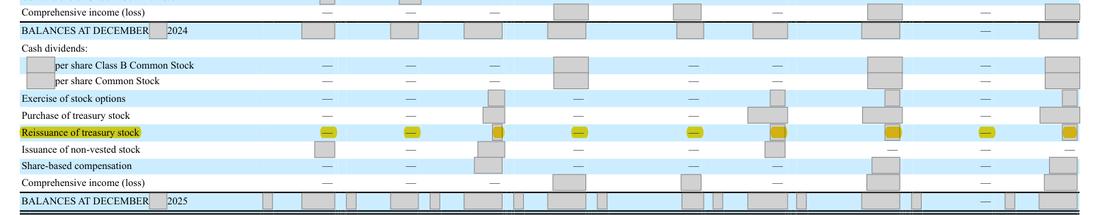
The statement of shareholders' equity records fiscal 2025 treasury stock purchases of [amount] and reissuances of [amount], a net [n]; the cash flow statement shows [n] for treasury stock transactions. The fiscal 2023 and 2024 differences ([n] and [n]) match the gap between the stock-option exercise amounts in the two statements, which points to shares tendered on option exercises, a noncash item. In fiscal 2025 the option amounts agree ([n] in both), so the [n] difference is not explained.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Fiscal 2025: equity purchases ([n]) and reissuance [n], net [n]; cash flow line ([n]); difference [n], with option exercises equal at [n] in both statements. No unsettled-repurchase or accrual disclosure. | The cash flow line agrees with the equity movements, or the fiscal 2025 difference (an unsettled trade or accrued excise tax, for example) is identified. |
The rule
FASB ASC 230-10-45 and 230-10-50-3 (classification by nature; noncash investing and financing activities)
Summary; FASB/IFRS text is copyrighted Classify cash receipts and payments as operating, investing or financing by their nature, present gross flows, include restricted cash, and disclose significant noncash activities.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 230-10-45 and 230-10-50-3 (as amended by ASU 2016-15 and ASU 2016-18), paraphrased
Why it applies here. in fiscal 2023 and 2024 the two gaps are the same amount (to within 1 of rounding), which is what happens when employees tender shares to pay an option exercise price: the tendered shares are booked as a treasury purchase and as part of the exercise, and neither leg is cash, as the line's label 'except for stock options' signals. At [n] and [n] these noncash items are not significant enough to raise a disclosure point. Fiscal 2025 is different: option amounts agree at [n], yet the treasury line is [n] lower than the net equity movement ([n]% of the line). Repurchases traded but unsettled at year end, or an excise tax on repurchases accrued into the cost of treasury stock and paid later, would produce a gap of this kind; the report does not say which.
Why it matters
A reader cannot fully tie the cash spent on repurchases in fiscal 2025 to the equity movement; the amount is small and is probably a timing item.
Exposure
A question; no requirement is shown to be breached until the company explains the difference.
Our workings
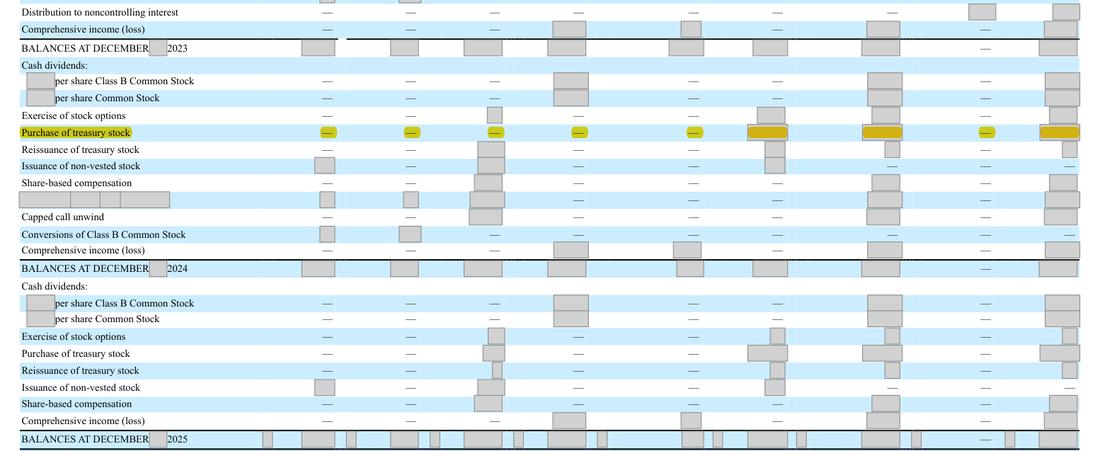
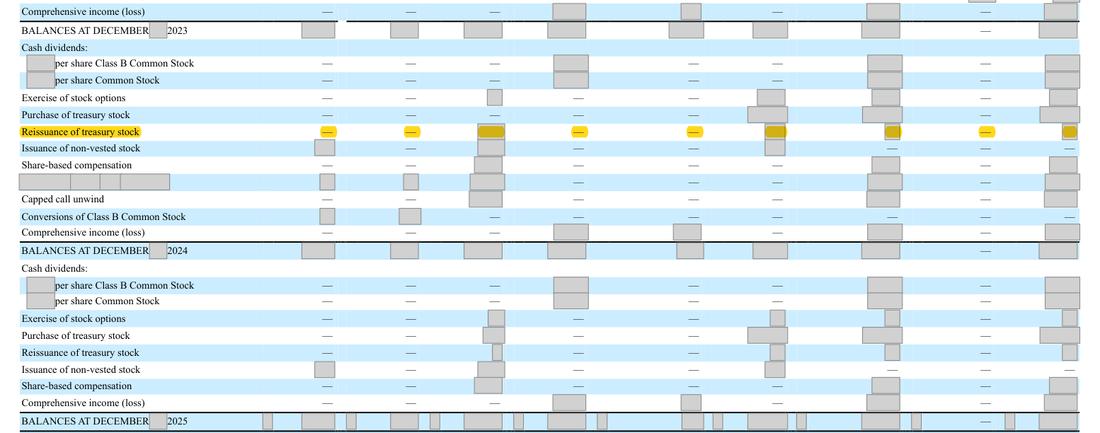
the statement of shareholders' equity shows purchase of treasury stock ([n]), ([n]) and ([n]), reissuance of treasury stock [n], and exercise of stock options [n] for fiscal 2025, 2024 and 2023. The financing section of the cash flow statement shows treasury stock transactions, except for stock options, of ([n]), ([n]) and ([n]), and exercise of stock options of [n].
the cash line is lower than the net treasury movement by [n]; the option exercise credited to equity exceeds the cash received by 0, [n] and [n].
| Year | Net treasury movement in equity | Less cash flow line | Option exercise: equity less cash |
|---|---|---|---|
| Fiscal 2025 | [n] - [n] = [n] | [n] - [n] = [n] | [n] - [n] = 0 |
| Fiscal 2024 | [n] - [n] = [n] | [n] - [n] = [n] | [n] - [n] = [n] |
| Fiscal 2023 | [n] - [n] = [n] | [n] - [n] = [n] | [n] - [n] = [n] |
| Fiscal 2025 difference against the line | [n] / [n] = [n]% |
Management’s best defense, and our reply
The finance team would say the fiscal 2023 and 2024 differences are shares tendered by employees to exercise options, a noncash exchange left out of both cash lines, as the label 'except for stock options' signals. It would add that the fiscal 2025 difference is a year-end accrual, an excise tax or an unsettled trade, of under 1% of the line. The first explanation is borne out by the figures, which is why the earlier years are not pursued; the second is plausible but the report does not identify the item, so fiscal 2025 remains a question that only the company can answer.
The fix
- State any repurchases unsettled, or excise tax accrued, at year end in Note 7, and give a noncash note for shares tendered on option exercises if they become significant.
Question for the company
What makes up the [amount] by which the fiscal 2025 treasury stock movements in the statement of shareholders' equity (purchases of [amount] less reissuances of [amount]) exceed the cash flow line of [amount]: repurchases unsettled at year end, excise tax accrued on repurchases, or another item, and where does it sit in the balance sheet?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Fiscal 2025 treasury stock purchases in the statement of shareholders' equity | Document | Form 10-K 2025, page 57 |
| 2 | Fiscal 2025 reissuance of treasury stock | Document | Form 10-K 2025, page 57 |
| 3 | Fiscal 2024 purchases | Document | Form 10-K 2025, page 57 |
| 4 | Fiscal 2024 reissuance | Document | Form 10-K 2025, page 57 |
| 5 | Fiscal 2023 purchases | Document | Form 10-K 2025, page 57 |
| 6 | Fiscal 2023 reissuance | Document | Form 10-K 2025, page 57 |
| 7 | Cash paid for treasury stock transactions in each year | Document | Form 10-K 2025, page 58 |
| 8 | Fiscal 2025 option exercises in the statement of equity: [n] | Document | Form 10-K 2025, page 57 |
| 9 | Fiscal 2024 option exercises in the statement of equity: [n] | Document | Form 10-K 2025, page 57 |
| 10 | Fiscal 2023 option exercises in the statement of equity: [n] | Document | Form 10-K 2025, page 57 |
| 11 | Cash received on option exercises: [n] | Document | Form 10-K 2025, page 58 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.