4.11 Critical accounting estimates give a sensitivity only for revenue; goodwill, first tested quantitatively in 2025, and the inventory reserve get none
Company H · a US-listed aerospace services company · SEC-style question
In brief
Item 303(b)(3) asks the critical accounting estimates discussion to say, where material and reasonably available, how much each estimate has changed and how sensitive the reported amount is to its assumptions. The revenue estimate has a sensitivity ([amount] for a 1% margin change). Goodwill of [amount] was tested quantitatively in 2025 (qualitatively in 2024), but the MD&A gives no indication of how far fair values exceed carrying amounts or how sensitive they are, and the inventory obsolescence estimate is described without the [amount] reserve or its change. The business combinations estimate is still listed although there was no acquisition in 2025.
The evidence, as filed
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
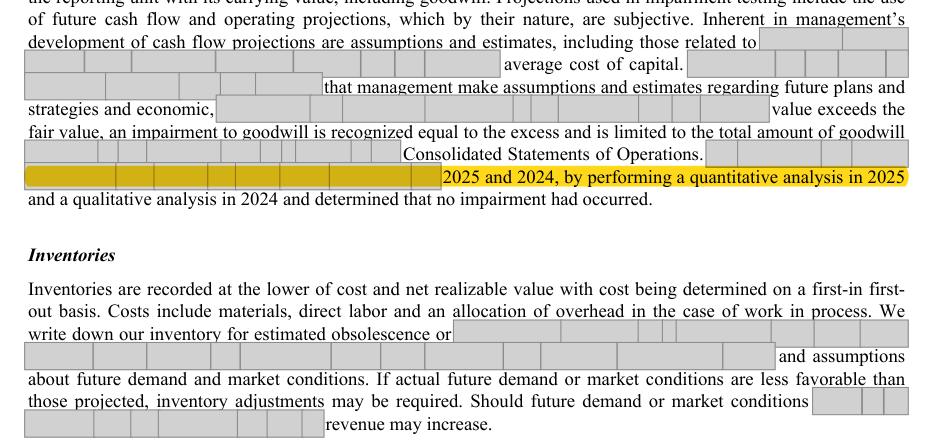
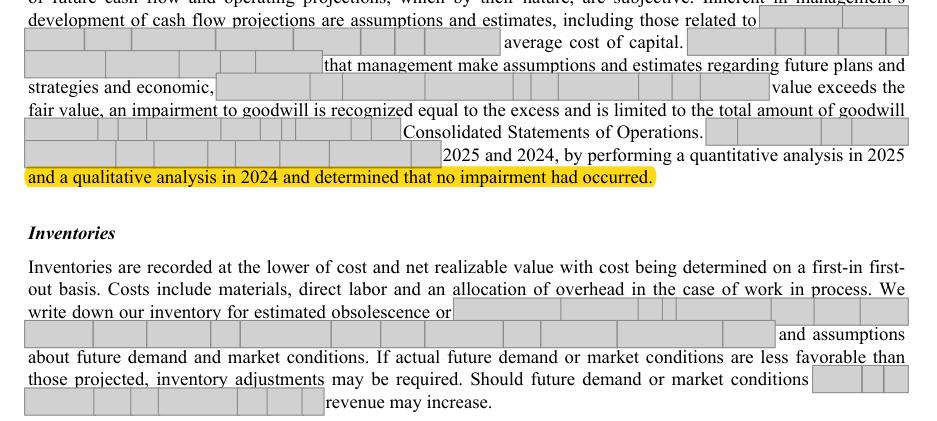
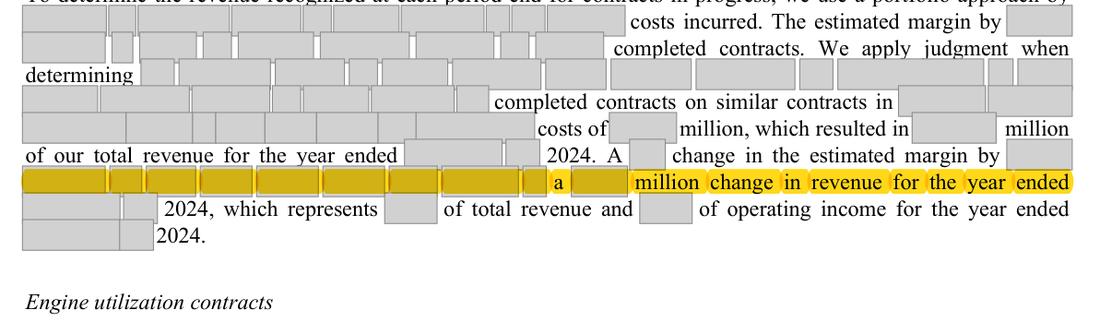
Revenue: 'A 1% change in the estimated margin by engine platform for open work orders would have resulted in a [amount] change in revenue'. Goodwill: 'by performing a quantitative analysis in 2025 and a qualitative analysis in 2024 and determined that no impairment had occurred'; no headroom, key assumption values or sensitivity. Inventories: method described (aging profiles), no amount or change. Business combinations: described generally; no acquisition in 2025. | For goodwill, a statement of whether any reporting unit's fair value is not substantially in excess of its carrying amount (and, if so, the headroom, the goodwill allocated, the key assumptions and their sensitivity), or a statement that all units are substantially in excess; for inventories, the reserve, how it moved and the sensitivity to the aging assumptions; and removal or explanation of the business combinations estimate if no longer critical. |
The rule
Regulation S-K Item 303(b)(3)
Provide qualitative and quantitative information necessary to understand the estimation uncertainty and the impact the critical accounting estimate has had or is reasonably likely to have on financial condition or results of operations to the extent the information is material and reasonably available.
Version: Text in force at the date of this review · Source: 17 CFR 229.303 (Regulation S-K Item 303), as amended by Release 33-10890
Regulation S-K Item 303, Instruction 3 to paragraph (b)
For critical accounting estimates, this disclosure must supplement, but not duplicate, the description of accounting policies or other disclosures in the notes to the financial statements.
Version: Text in force at the date of this review · Source: 17 CFR 229.303 (Regulation S-K Item 303), as amended by Release 33-10890
Why it applies here. because a quantitative test was performed, fair-value headroom by reporting unit was reasonably available; whether it was large enough that sensitivity is immaterial, and whether the inventory reserve movement reflects a change in assumptions, are matters only management can confirm, so the point is put as a question rather than a settled gap.
Why it matters
Readers cannot judge how close goodwill of [amount] is to impairment or how sensitive earnings are to the inventory reserve; missing sensitivity in critical accounting estimates is a frequent staff comment.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, critical accounting estimates drew 23 of the 1,774 numbered comments (1.3%): topic 16 of 25 by frequency.
Exposure
None while the point is a question; if headroom is not substantial the staff would expect the at-risk disclosure in future filings.
Our workings
Item 303(b)(3) defines critical accounting estimates as those with significant estimation uncertainty and a material effect, and requires qualitative and quantitative information to understand the uncertainty, including, where material and reasonably available, how much each estimate has changed and its sensitivity; Instruction 3 says the discussion must supplement, not duplicate, the policy notes.
the revenue estimate gives a sensitivity.
the goodwill estimate states that the 2025 annual test was quantitative (2024 qualitative) and found no impairment; the goodwill note adds only that each reporting unit's fair value exceeded its carrying value. Goodwill is [n] on the balance sheet.
the inventory estimate describes the aging-profile method; the reserve of [amount] (2024: [amount]) appears only in the inventory note.
no acquisition was made in 2025, yet business combinations remain a critical estimate.
goodwill [n] / [n] total assets = [n]%; the inventory reserve rose [n] - [n] = [n].
| Critical accounting estimate | Why uncertain | Change over the period quantified | Sensitivity quantified |
|---|---|---|---|
| Revenue over time (fixed price, time and materials) | Given | No | Yes: 1% margin = [amount] |
| Engine utilization contracts | Given | No | No |
| Business combinations | Given (no acquisition in 2025) | No | No |
| Goodwill ([n]; quantitative test 2025) | Given | No | No |
| Inventories (reserve [n]) | Given | No | No |
| Income taxes (valuation allowance [n] vs [n]) | Given | Yes | No |
| Goodwill share of total assets: [n] / [n] | [n]% | ||
| Inventory reserve increase: [n] - [n] | [n] | ||
| Goodwill in millions: [n] / [n] | [n] |
Management’s best defense, and our reply
Management would say sensitivity is required only to the extent material and reasonably available; the company's market capitalization is several times book equity, so goodwill headroom is not in doubt and a sensitivity would add nothing, and the inventory reserve is small against inventories of [amount]. It might add that business combinations stay listed because acquisitions are part of the strategy. Those arguments may well be right, which is why this is a question; but the staff's Financial Reporting Manual (sections [n] and [n]) asks registrants to consider stating that no reporting unit is at risk, or giving the headroom of any that is, once a quantitative test has been run, and the reserve movement is quantified only in the notes.
The fix
- Add to the goodwill estimate: 'In our [date] quantitative test, the fair value of each reporting unit exceeded its carrying amount by more than [x]%; a [n] basis point increase in the discount rate would not result in an impairment.' Add the inventory reserve, its change and a sensitivity; drop business combinations unless an acquisition is pending.
Question for the company
In the [date] quantitative goodwill test, did the fair value of each reporting unit ([segment], [segment]) exceed its carrying amount substantially, and by roughly what margin; and was the [amount] increase in the inventory reserve driven by a change in aging or demand assumptions that should be quantified as a critical estimate?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | the revenue estimate carries a quantified sensitivity | Document | Form 10-K 2025, page 65 |
| 2 | goodwill was tested quantitatively in 2025 | Document | Form 10-K 2025, page 66 |
| 3 | the goodwill estimate ends with the conclusion; no headroom or sensitivity | Document | Form 10-K 2025, page 66 |
| 4 | goodwill balance | Document | Form 10-K 2025, page 75 |
| 5 | total assets for the share of goodwill | Document | Form 10-K 2025, page 75 |
| 6 | the note says only that fair values exceeded carrying values | Document | Form 10-K 2025, page 98 |
| 7 | the inventory estimate describes the method only | Document | Form 10-K 2025, page 66 |
| 8 | the inventory reserve and its movement appear only in the note | Document | Form 10-K 2025, page 96 |
| 9 | the income tax estimate does quantify the valuation allowance and its change | Document | Form 10-K 2025, page 67 |
| 10 | no acquisition in 2025, yet business combinations remain a critical estimate | Document | Form 10-K 2025, page 60 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Goodwill
- What is missing
- any statement of fair-value headroom, at-risk reporting units, key assumption values or sensitivity for goodwill
- Pages looked at
- p.64-67 (Critical Accounting Estimates), p.96-98 (goodwill note)
- Result
- none of the terms hits anywhere in the report.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.