1.11 Cash flows: how the 2025 payment for a license acquired on credit in 2024 was classified
Company H · a US-listed aerospace services company · SEC-style question
In brief
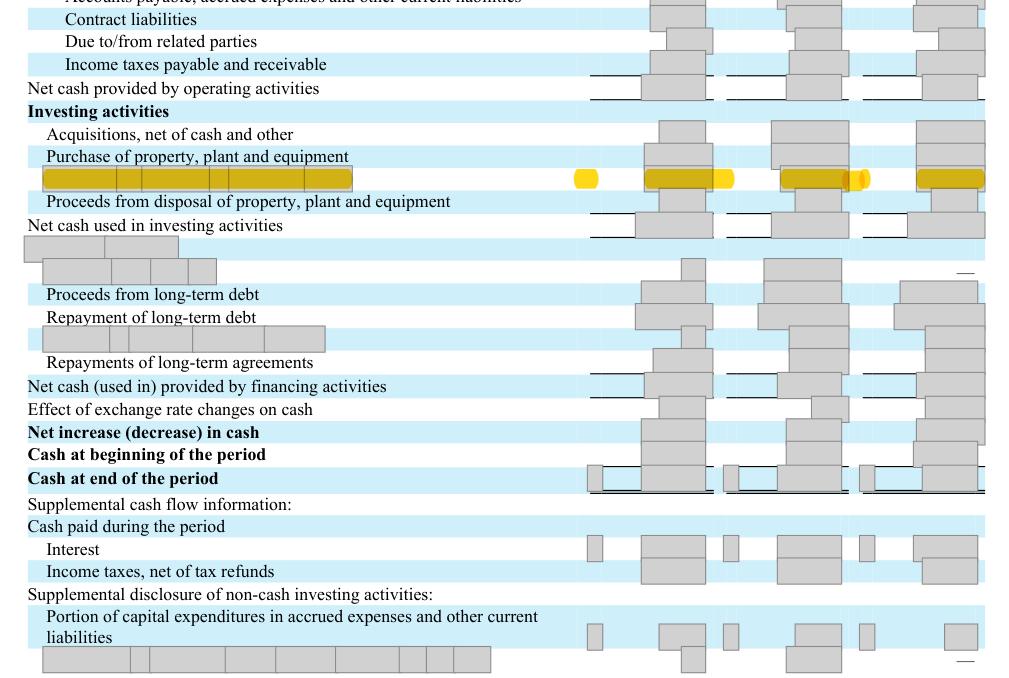
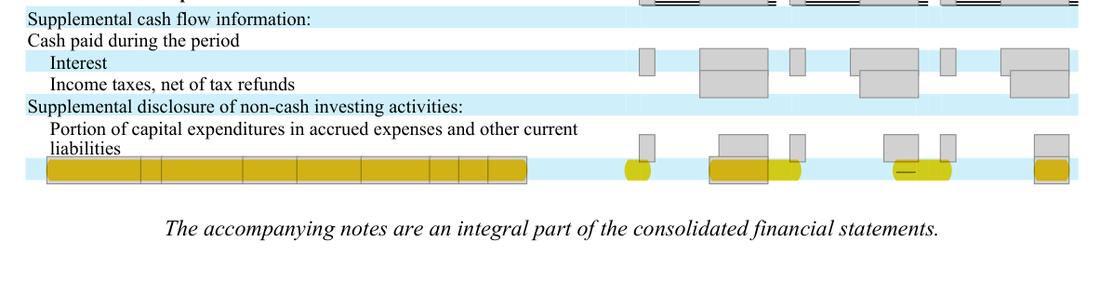
In 2024 the company acquired a licensing agreement for [n] that was unpaid at the year end and reported it as a non-cash investing activity. It paid [n] in 2025, in two instalments of [amount] in the first and second quarters according to its Forms 10-Q, and shows the payment as 'Payments for purchase of intangible assets' in investing activities. US GAAP treats payments made at or soon after purchase as investing, and principal payments to a seller that has extended credit as financing. The 10-K gives neither the acquisition date nor the payment terms, so which treatment applies cannot be told from the filing.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
2025 investing outflow 'Payments for purchase of intangible assets' ([n]), described in Item 7 as payment of the licensing agreement acquired in 2024; 2024 non-cash disclosure [n]; no acquisition date or payment terms given; other long-term agreements repaid in financing ([n]). | A statement of the license's acquisition date and payment terms, so that a reader can see whether the 2025 payment was made soon after purchase (investing) or repaid seller credit (financing), and the payment classified accordingly. |
| What we checked. Cash flow statement 2025 and 2024, supplemental non-cash disclosures, Note 9 intangible assets, Note 11 accrued liabilities, Item 7 cash flow discussion; the Forms 10-Q for the first and second quarters of 2025; the prior-year Form 10-K. | |
The rule
FASB ASC 230-10-45-13(c) and 230-10-45-15 (investing payments made at or soon after purchase; other principal payments to creditors who extended credit are financing), paraphrase
Summary; FASB/IFRS text is copyrighted Classify cash receipts and payments as operating, investing or financing by their nature, present gross flows, include restricted cash, and disclose significant noncash activities.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 230-10-45 (as amended by ASU 2016-15), paraphrase
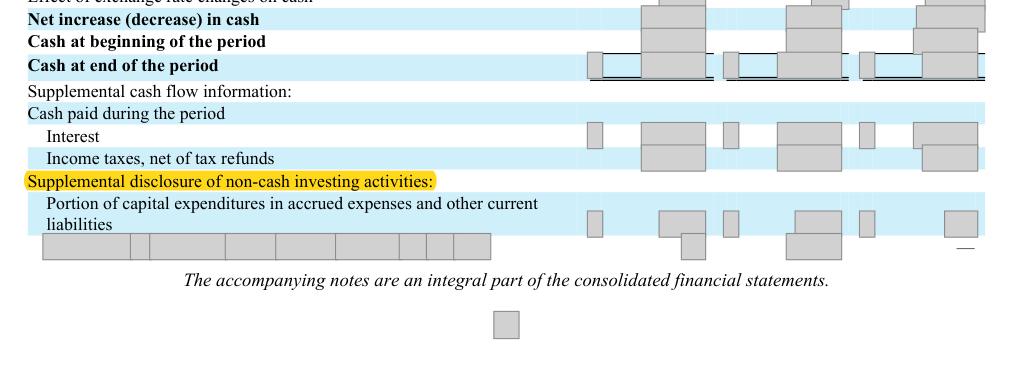
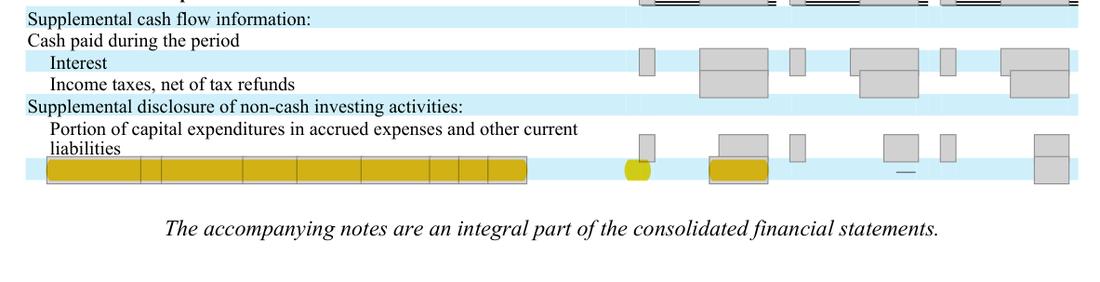
Why it applies here. the 2024 cash flow statement disclosed 'Acquisition of intangible assets, liability incurred but not paid' of [n] (prior-year Form 10-K and this one). Item 7 says the 2025 investing outflow included [amount] 'in payment during the current period of our licensing agreement acquired during the year ended [date]', and the Forms 10-Q show [amount] paid in the first quarter and [amount] by [date]. The cash flow statement shows payments for intangible assets of [n] in investing activities, while 'Repayments of long-term agreements' of [n] sit in financing activities.
Why it matters
Investing outflows, and free cash flow measures built on them, depend on this classification; the payment is [n]% of 2025 investing outflows ([n] / [n]).
Exposure
A question for management; if the seller extended credit beyond normal terms, the realistic consequence is a staff comment and reclassification in future filings.
Our workings
the payment is 8.07% of pre-tax income; classified as financing, 2025 investing outflows would be [n] rather than [n] and the financing outflow [n] rather than [n]; operating cash flow is unaffected. Assessment: a capital purchase accrued at a year end and paid in the following months is routinely shown as an investing outflow when paid, and the company treats its accrued capital expenditure the same way; the classification turns on when the license was acquired and on its payment terms, neither of which the 10-K states. The point is therefore a question for management, not a finding.
| Item | Arithmetic | Result |
|---|---|---|
| Payment as share of pre-tax income | [n] / [n] = 8.07% | 8.07% |
| Investing outflow if reclassified | [n] - [n] = [n] | [n] |
| Financing outflow if reclassified | [n] + [n] = [n] | [n] |
| Payment as share of investing outflows | [n] / [n] = 28.57% | [n]% |
| Payment less 2024 liability | [n] - [n] = [n] | [n] |
Management’s best defense, and our reply
The company may say that the license was invoiced late in 2024 and paid in the first half of 2025 on the agreed schedule, so the payment was made soon after purchase and is properly an investing outflow, in the same way as its accrued capital expenditure. It may add that OEM license payments are capital expenditure in substance and that investors expect to see them in investing activities. The answer: that may well be right, and it is why this is only a question; but the payment ran over two quarters, the 10-K gives no acquisition date or terms, and the company presents its other deferred long-term agreements in financing, so a sentence on the terms would show which treatment applies.
The fix
- State the payment terms of the licensing agreement and, if the seller extended credit beyond normal terms, present the 2025 payment as a financing outflow (for example 'Payments on deferred license obligations') with the comparative explained.
Question for the company
When was the licensing agreement acquired in 2024 and on what payment terms, and on that basis was the 2025 payment, made in two instalments in the first half of the year, a payment made soon after purchase (investing) or the repayment of credit extended by the seller (financing)?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Shown in investing activities | Document | Form 10-K 2025, page 79 |
| 2 | Investing total | Document | Form 10-K 2025, page 79 |
| 3 | Financing total | Document | Form 10-K 2025, page 79 |
| 4 | Other deferred agreements are repaid in financing | Document | Form 10-K 2025, page 79 |
| 5 | The 2024 purchase was unpaid at the year end | Document | Form 10-K 2025, page 79 |
| 6 | Item 7 links the 2025 payment to the 2024 purchase | Document | Form 10-K 2025, page 64 |
| 7 | Long-term agreements are carried as liabilities | Document | Form 10-K 2025, page 98 |
| 8 | Prior-year Form 10-K disclosed the unpaid purchase | Document | Form 10-K 2024 (prior year), page 77 |
| 9 | Pre-tax income for scale | Document | Form 10-K 2025, page 76 |
| 10 | First-quarter 2025 Form 10-Q: first instalment of the license payment | Document | |
| 11 | Second-quarter 2025 Form 10-Q: [amount] paid by [date] | Document |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Supplemental disclosure of non-cash investing activities:
- What is missing
- the payment terms of the licensing agreement acquired in 2024 and settled in 2025
- Pages looked at
- p.64, [n], 97-98
- Result
- 'payment terms' hits p.83 (customer payment terms for revenue contracts) and [n] (award agreements); 'licensing agreement' hits p.15 (competitors' OEM licenses) and [n] (Item 7 sentence quoted above, no terms); 'liability incurred but not paid' hits p.79 (the 2024 amount, no terms); 'deferred payment' has no hits.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.