1.09 Income taxes paid: state and 'other foreign' lines each exceed 5% of the total with no jurisdiction named
Company H · a US-listed aerospace services company · SEC-style question
In brief
2025 is the first year of the new income tax disclosures, which require taxes paid by federal, state and foreign, and by any individual jurisdiction paying at least 5% of the total. The 5% level is [n]. State taxes of [n] and 'other foreign jurisdictions' of [n] are each above it, yet no state or country inside them is named, although the note says [state] makes up more than half of state tax expense.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
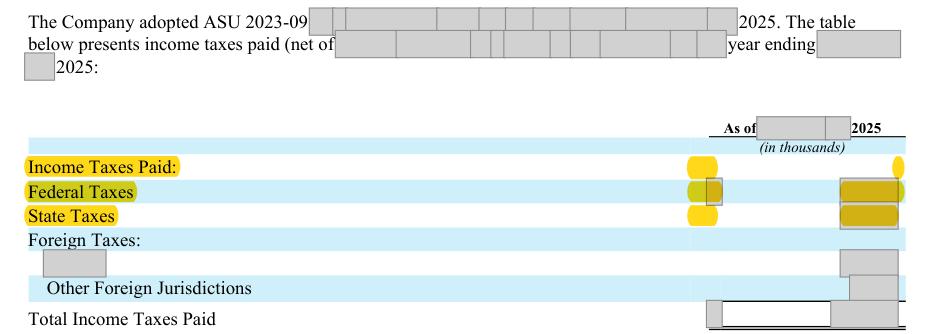
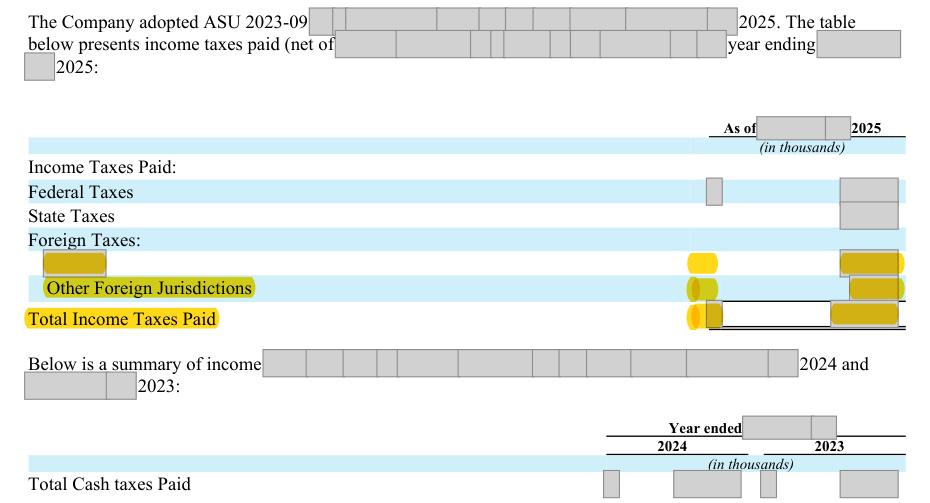
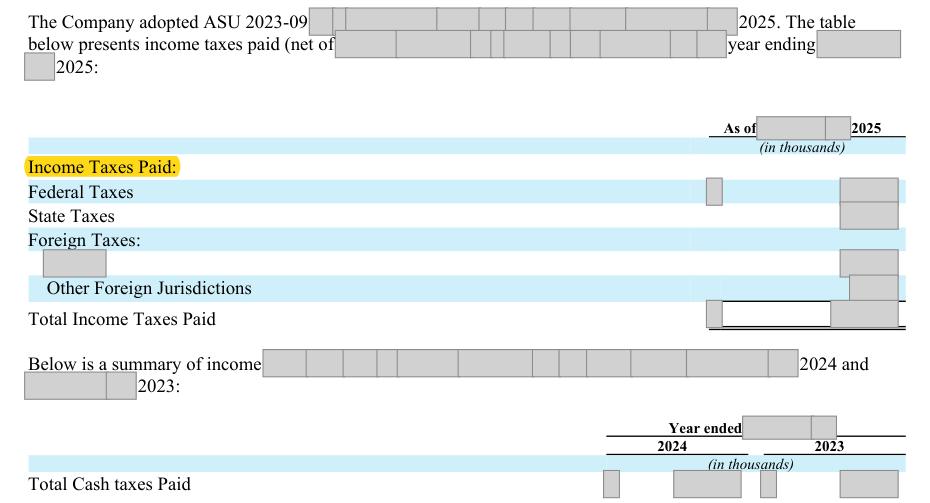
Income taxes paid 2025: Federal [n]; State [n]; [country] [n]; Other foreign jurisdictions [n]; total [n]. No individual state, and no country other than [country], is named. | Each individual jurisdiction (state or foreign country) whose taxes paid are 5% or more of [n] (that is, [n] or more) shown separately, or a statement that none within the state and other-foreign lines reaches that level. |
| What we checked. Note 14 taxes-paid table, rate reconciliation and state-jurisdiction sentence, current and deferred tax components, adoption note; the prior-year Form 10-K. | |
The rule
FASB ASC 740-10-50-22 to 50-23 (as amended by ASU 2023-09), paraphrase
Summary; FASB/IFRS text is copyrighted Disclose income taxes paid (net of refunds) by federal, state and foreign, and by any jurisdiction at least 5% of total; split pre-tax income domestic/foreign.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 740-10-50-22 and 50-23 (as amended by ASU 2023-09), paraphrase
Why it applies here. if [state]'s cash payments track its share of expense, [state] alone paid more than the 5% level and had to be named; the 'other foreign' line could also hide a country at or above the level (it would need to be about 62% of that line). Whether any single jurisdiction crosses [n] depends on payment data only the company holds, so this is put as a question.
Why it matters
In the first year of the new standard the jurisdictional detail is the point of the disclosure; leaving a state or a country above 5% inside an aggregate line is a common subject of staff comments on these disclosures.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, income taxes drew 23 of the 1,774 numbered comments (1.3%): topic 17 of 25 by frequency.
Exposure
A question for management; if a jurisdiction crosses 5%, the realistic consequence is a staff comment and a future-filings undertaking.
Our workings
the company adopted the new income tax disclosure update prospectively for 2025. Its taxes-paid table shows State [n] and Other Foreign Jurisdictions [n] without further breakdown, and the rate reconciliation note says [state] exceeds 50% of state tax expense. State tax expense is [n] current less [n] deferred.
5% of total taxes paid is [n]; both aggregated lines exceed it; [state]'s share of state tax expense is above [n].
| Test | Arithmetic | Result |
|---|---|---|
| 5% of total income taxes paid | [n] x 5% = [n] | [n] |
| State line vs threshold | [n] - [n] = [n] | above by [n] |
| Other foreign line vs threshold | [n] - [n] = [n] | above by [n] |
| State tax expense 2025 | [n] + ([n]) = [n] | [n] |
| [state] share of state expense (over 50%) | [n] x 50% = [n] | more than [n] |
| Share of 'other foreign' one country would need | [n] / [n] = 61.7% | 61.7% |
Management’s best defense, and our reply
The company may say that the 5% test is applied jurisdiction by jurisdiction on cash paid, not on expense, and that [state]'s payments in 2025 (after estimated payments, refunds and timing) fell below [n], while no single other country reached it. It may also point out that 2025 is the first year and that the categories shown follow the standard's federal, state and foreign split. The answer: that may be so, but the table gives the reader no way to know, and the note's own statement that [state] is over half of state expense makes a crossing likely; a one-line statement would settle it.
The fix
- Add each jurisdiction at or above 5% of taxes paid (for example 'State: [state] $X; other states $Y'), or state that no individual state or other foreign jurisdiction reached 5% of total income taxes paid.
Question for the company
Did any individual state (in particular [state]) or any foreign country within 'Other Foreign Jurisdictions' account for 5% or more of the [n] of income taxes paid in 2025, and if so why is it not shown separately?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Federal and state taxes paid; the state line is not broken down | Document | Form 10-K 2025, page 107 |
| 2 | Only [country] is named among foreign jurisdictions | Document | Form 10-K 2025, page 107 |
| 3 | [state] is over half of state tax expense | Document | Form 10-K 2025, page 105 |
| 4 | Current state tax expense | Document | Form 10-K 2025, page 104 |
| 5 | Deferred state tax expense | Document | Form 10-K 2025, page 104 |
| 6 | 2025 is the first year of the new disclosures | Document | Form 10-K 2025, page 90 |
| 7 | State taxes paid are shown as one amount | Document | Form 10-K 2025, page 107 |
| 8 | Foreign taxes paid outside [country] are shown as one amount, 8.11% of the total | Document | Form 10-K 2025, page 107 |
| 9 | Total income taxes paid; 5% of it is [n] | Document | Form 10-K 2025, page 107 |
| 10 | [state] is more than half of state tax expense; if its share of the [n] state payments is similar it exceeds [n], above the [n] line | Document | Form 10-K 2025, page 105 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Income Taxes Paid:
- What is missing
- any individual state or foreign country paying 5% or more of total income taxes paid
- Pages looked at
- p.90, 102-108
- Result
- '[state]' hits p.25, [n] (privacy and climate laws), 50-51 (facility locations) and [n] (share of state tax expense, not taxes paid); 'Income Taxes Paid' and 'taxes paid' hit p.22 (risk factor), [n] (adoption note) and [n] (the table itself, which names only [country]); 'individual jurisdiction' has no hits.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.