3.01 Exhibit index: three hyperlinks to incorporated exhibits are dead or point to the wrong document, including the license filed at the SEC staff's request; two were already wrong in the prior-year 10-K
Company G · a US-listed specialty pharmaceutical company · Compliance or disclosure gap
In brief
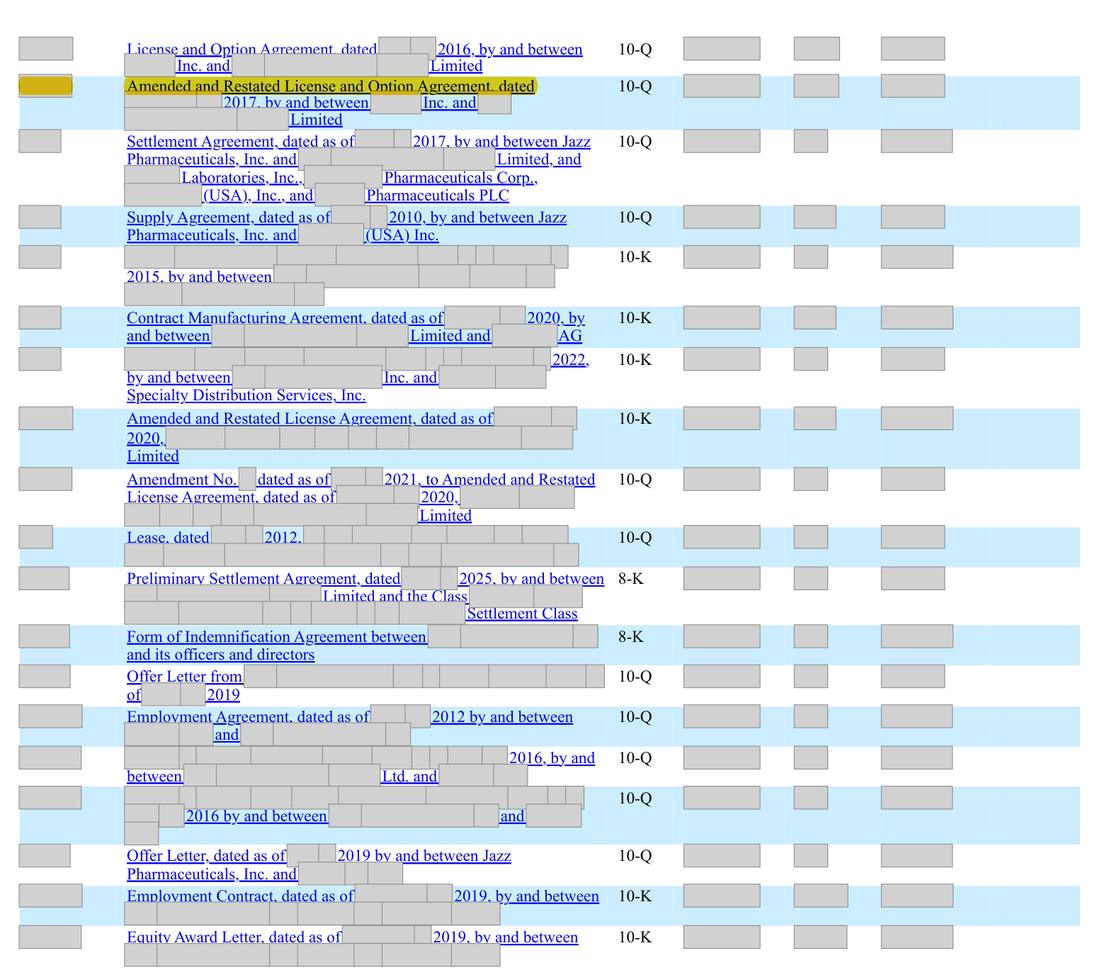
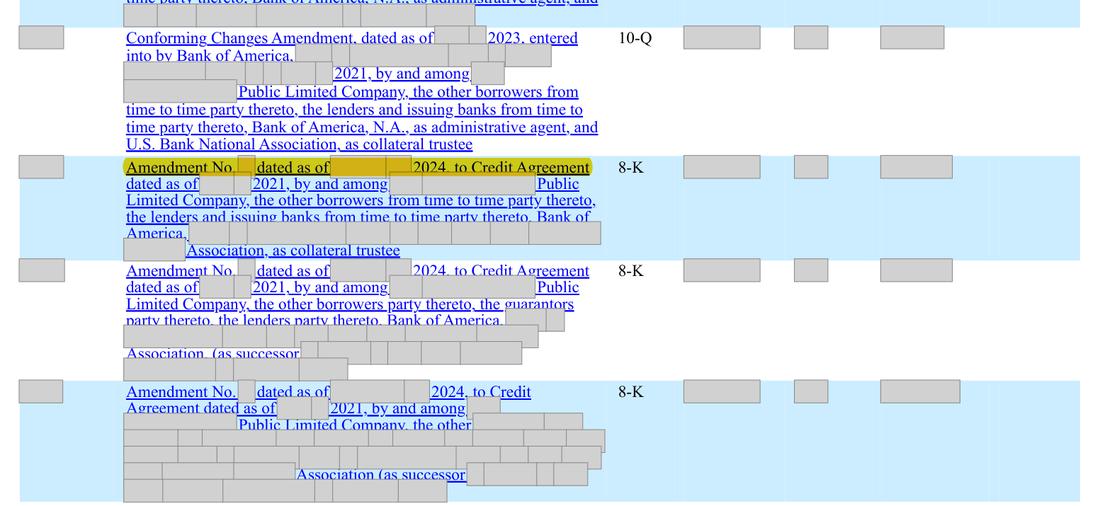
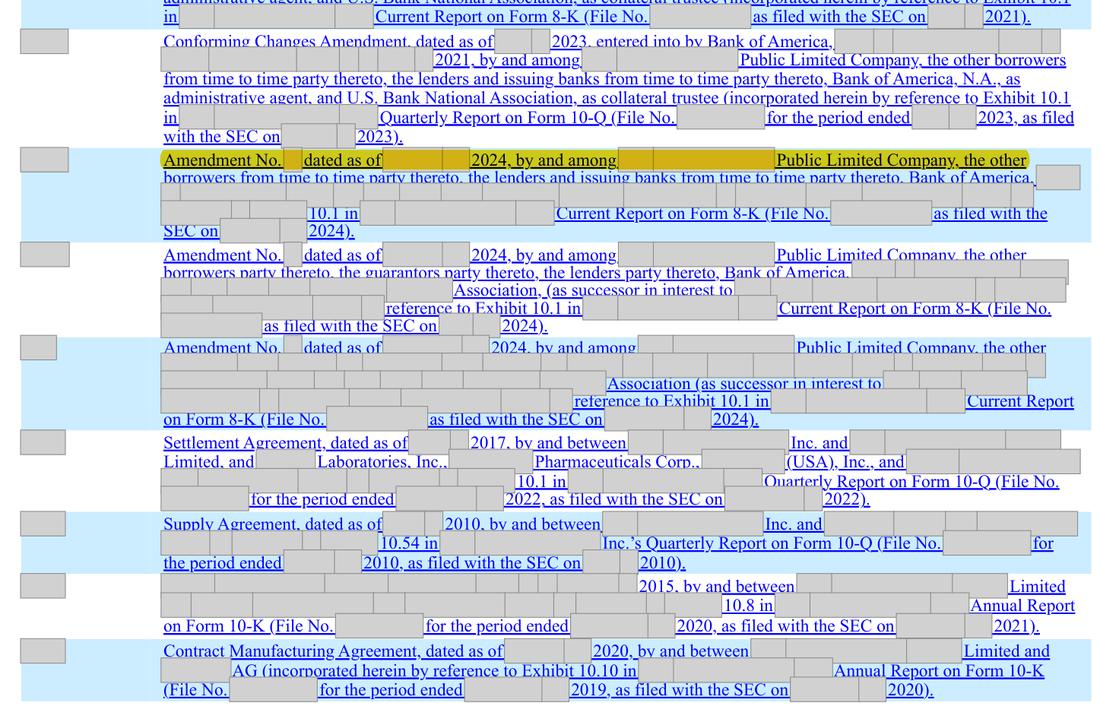
Every exhibit incorporated by reference must carry an active hyperlink to that exhibit on the Electronic Data Gathering, Analysis, and Retrieval system (EDGAR). In the filed 10-K the link for exhibit 10.2B, the restated [product] license that the company filed in [date] after an SEC staff comment, is malformed and opens a 'Not Found' page. The link for 10.1C (credit agreement Amendment No. 1) opens a different filing, the [date] Form 8-K, and the link for 10.1D opens that Form 8-K's cover document rather than its Exhibit 10.[n]. The Part III amendment of [date] repeats all three. The prior-year Form 10-K (fiscal 2024) already linked 10.1C and 10.1D to the [date] Form 8-K and its cover document.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Exhibit index rows 10.2B, 10.1C and 10.1D are correctly described by form, filing date and exhibit number, but their hyperlinks do not open the exhibit: 10.2B is a broken address, 10.1C opens the [date] Form 8-K, 10.1D opens a Form 8-K cover document; the prior-year Form 10-K had the same 10.1C and 10.1D links | Each incorporated exhibit hyperlinked to the exhibit itself: 10.2B to Exhibit 10.[n]B of the Form 10-Q filed [date]; 10.1C to Exhibit 10.[n] of the Form 8-K filed [date]; 10.1D to Exhibit 10.[n] of the Form 8-K filed [date] |
| What we checked. Every row of the exhibit index: the hyperlink in the filed document opened and compared with the exhibit list of the filing the row names | |
The rule
Regulation S-K Item 601(a)(2)
Each exhibit identified in the exhibit index (other than an exhibit filed in eXtensible Business Reporting Language or an exhibit that is filed with Form ABS-EE) must include an active link to an exhibit that is filed with the registration statement or report or, if the exhibit is incorporated by reference, an active hyperlink to the exhibit separately filed on EDGAR.
Version: Text in force at the date of this review · Source: 17 CFR 229.601(a)(2), Regulation S-K (eCFR, as amended by Release 33-10322)
Why it applies here. One-click access fails for three rows. Exhibit 10.[n]B matters most: the staff asked for the [product] license in its letter of [date], Jazz filed it, and the 10-K's route to it is broken. The prior-year 10-K had the same faulty links for 10.1C and 10.1D.
Why it matters
- Readers following the index to the [product] license, an exhibit the SEC staff specifically asked for, reach an error page; two credit-agreement rows open the wrong document.
- No penalty in practice; the realistic outcome is a staff comment asking for the links to be corrected in the next exhibit index. The same links went unchanged into the [date] amendment.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, exhibits and certifications drew 41 of the 1,774 numbered comments (2.3%): topic 13 of 25 by frequency.
Exposure
No penalty in practice for an inaccurate hyperlink on its own; the realistic consequence is a staff comment asking for the links to be corrected in the next filing that carries an exhibit index.
Our workings
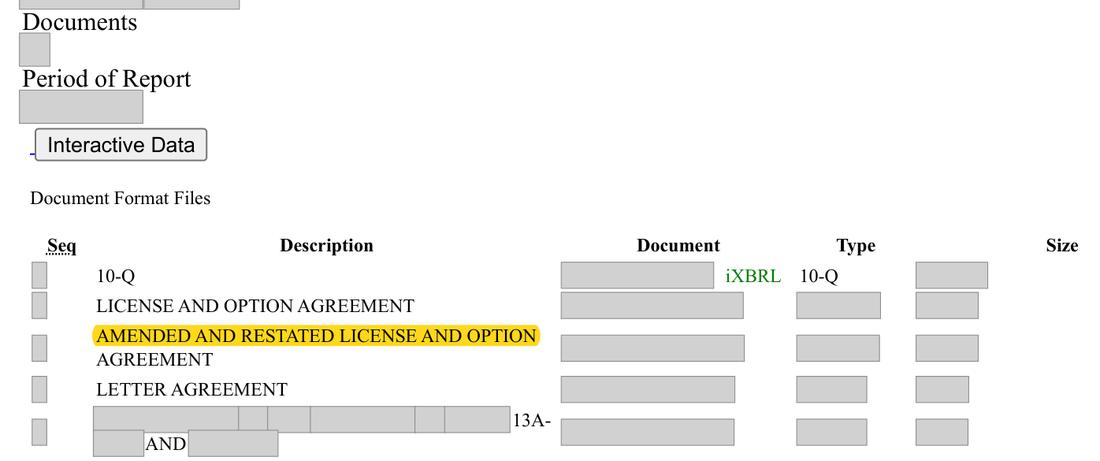
the exhibit index lists 10.2B, the Amended and Restated License and Option Agreement with [counterparty] of [date], as incorporated from Exhibit 10.[n]B of the Form 10-Q filed on [date], and 10.1C and 10.1D, Amendments No. 1 and No. 2 to the credit agreement, as incorporated from Exhibit 10.[n] of the Forms 8-K filed on [date] and [date]. The EDGAR filing index of that Form 10-Q lists the restated license as Exhibit 10.[n]B, and each Form 8-K lists its amendment as Exhibit 10.[n]. In the filed [n] document, the hyperlink behind row 10.2B joins two web addresses into one and EDGAR answers 'Not Found'; the hyperlink behind 10.1C opens the [date] [n], not the [date] one; the hyperlink behind 10.1D opens the [date] [n] cover document, not its exhibit (extra workings). The other rows open the exhibit named. The Part III amendment's exhibit index carries the same three links, and the prior-year [n] already linked 10.1C to the [date] [n]
none; the test is whether each link opens the exhibit named.
the descriptions are right, so a reader can still find each document by search, but the rule's purpose, one-click access to the exhibit, fails for these three rows. Exhibit 10.[n]B matters most: it was filed because the SEC staff asked, in its letter of [date], for the [product] license to be filed, and the company undertook to file it with its [date] Form 10-Q; the filing was made, but the 10-K's route to it is broken.
| Exhibit | Named source | Where the hyperlink goes | Result |
|---|---|---|---|
| 10.2B | Form 10-Q filed [date], Exhibit 10.[n]B | malformed address (two addresses joined) | Not Found |
| 10.1C | Form 8-K filed [date], Exhibit 10.[n] | Form 8-K filed [date], cover document | wrong filing |
| 10.1D | Form 8-K filed [date], Exhibit 10.[n] | the same Form 8-K, cover document | not the exhibit |
| Exhibit | 10-K ([date]) | Part III amendment ([date]) | Prior-year 10-K ([date]) |
|---|---|---|---|
| 10.2B | broken | broken (same address) | not listed (filed in 2025) |
| 10.1C | [date] Form 8-K | [date] Form 8-K | [date] Form 8-K |
| 10.1D | [date] Form 8-K cover | [date] Form 8-K cover | [date] Form 8-K cover |
Management’s best defense, and our reply
The company can say that each row names the right form, filing date and exhibit number, every document is on EDGAR, and a reader loses nothing but a click; an inaccurate hyperlink, on its own, does not make a filing deficient or require an amendment. The 10.2B fault is a mechanical conversion error, not a failure to file the exhibit the staff asked for. However, Item 601(a)(2) makes an active link to the incorporated exhibit part of the exhibit index itself, the same three links went unchanged into the Part III amendment two months later, and one of them was already wrong a year earlier, so the point stands as a low-severity compliance gap to be corrected in the next exhibit index.
The fix
- Re-point the three links in the next exhibit index: 10.2B to Exhibit 10.[n]B of the Form 10-Q filed [date], 10.1C to Exhibit 10.[n] of the Form 8-K filed [date], 10.1D to Exhibit 10.[n] of the Form 8-K filed [date]; add a link-open test to the filing checklist.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Exhibit index row 10.2B: the restated [product] license, named as incorporated from the Form 10-Q filed [date] | Document | Form 10-K 2025, page 112 |
| 2 | EDGAR filing index of the [date] Form 10-Q: the restated license is on file as Exhibit 10.[n]B, so a working link was available | Document | |
| 3 | Exhibit index row 10.1C, named as incorporated from the Form 8-K filed [date] | Document | Form 10-K 2025, page 111 |
| 4 | [date] Form 8-K: Amendment No. 1 is its Exhibit 10.[n], the document the 10.1C link should open | Document | |
| 5 | Exhibit index row 10.1D, named as incorporated from the Form 8-K filed [date] | Document | Form 10-K 2025, page 111 |
| 6 | [date] Form 8-K: Amendment No. 2 is filed as a separate Exhibit 10.[n], which the 10.1D link does not open | Document | |
| 7 | Part III amendment of [date]: the same row, carrying the same broken link | Document | |
| 8 | SEC staff letter of [date]: the request that led to the license being filed | Document | |
| 9 | Company response of [date]: the undertaking, delivered with the [date] Form 10-Q | Document | |
| 10 | Exhibit 10.[n]C in the fiscal 2024 exhibit index: Amendment No. 1 to the credit agreement | Document | Form 10-K 2024 (prior year), page 107 |
| 11 | The row names the Form 8-K filed on [date] as the source; its hyperlink in the filed document opens the Form 8-K filed on [date] instead | Document | Form 10-K 2024 (prior year), page 107 |
| 12 | Exhibit 10.[n]D names Exhibit 10.[n] of the Form 8-K filed on [date]; its hyperlink opens that Form 8-K's cover document, not the exhibit | Document | Form 10-K 2024 (prior year), page 107 |
| 13 | The [date] Form 8-K is the filing that carries Amendment No. 1, the document the 10.1C link should open | Document | |
| 14 | The [date] Form 8-K, which both the 10.1C and 10.1D links open at its cover document, carries Amendment No. 2 | Document |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.