1.05 Income tax note: the contested [country] tax assessments of about [amount] disappear from the 10-K without any word on how they ended
Company G · a US-listed specialty pharmaceutical company · SEC-style question
In brief
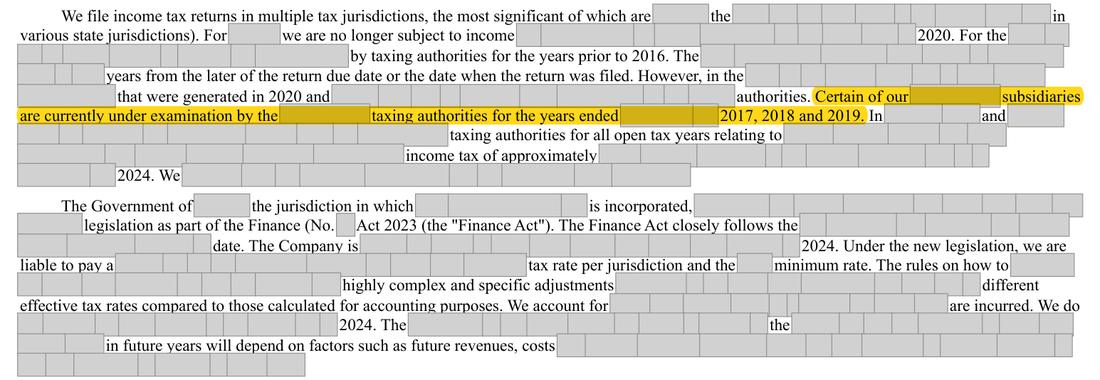
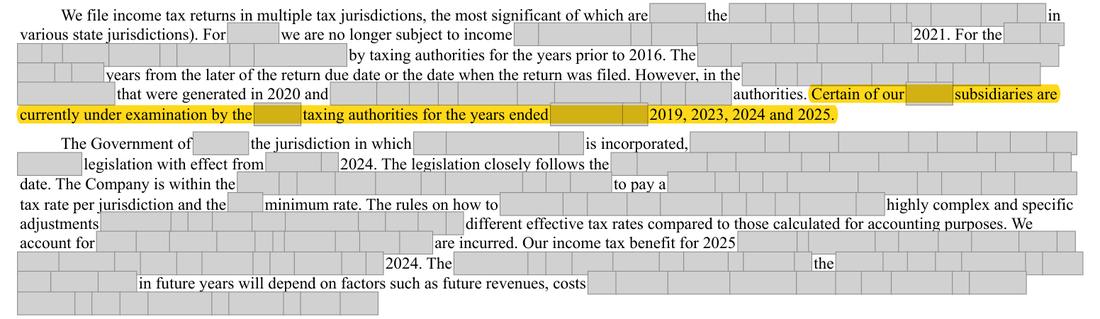
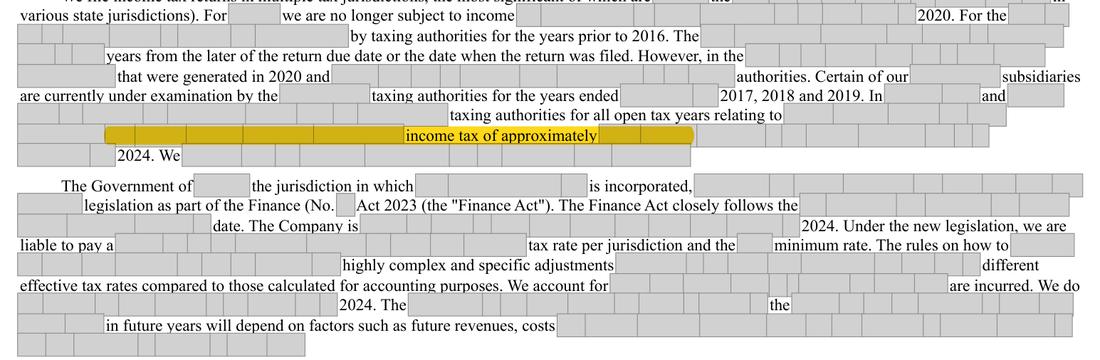
The prior-year 10-K said certain [country] subsidiaries were under examination for 2017 to 2019 and that assessment notices proposed about [amount] of additional tax, which the company was contesting vigorously. The current 10-K does not mention [country] at all: its list of examinations names only [country], and the 2025 roll-forward of unrecognized tax benefits shows no settlement with taxing authorities. Whether the assessments were won, settled, dropped or are still open is not said.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Fiscal 2025 10-K: no mention of the [country] examination or of the assessment notices proposing about [amount] that the prior-year 10-K said were being contested; 2025 shows no settlements with taxing authorities | A sentence on the outcome (settled, withdrawn, decided, or still contested, with the years still open), or confirmation that [country] is no longer a jurisdiction with open examinations |
The rule
Exchange Act Rule 12b-20
In addition to the information expressly required to be included in a statement or report, there shall be added such further material information, if any, as may be necessary to make the required statements, in the light of the circumstances under which they are made not misleading.
Version: Text in force at the date of this review · Source: 17 CFR 240.12b-20 (eCFR, as in force 2024-2025)
Why it applies here. either the matter ended in 2025 in a way the note does not report (for example by withdrawal or a decision), or it remains open and has been dropped from the description of examinations. The standard asks for the tax years that remain subject to examination by major tax jurisdictions; having named [country] and the amount in one year, silence the next leaves a reader unable to tell whether the exposure was removed.
Why it matters
A reader told last year of a contested [amount] tax assessment cannot tell from the current 10-K whether that exposure has ended or remains.
Exposure
No penalty; at most a staff comment asking for the status and a sentence in future filings.
Our workings
the prior-year 10-K's tax note said certain [country] subsidiaries were under examination for the years ended [date], 2018 and 2019; that assessment notices received in [date] and [date] proposed additional [country] income tax of approximately [amount]; and that the company disagreed and was contesting them vigorously. The fiscal 2025 10-K's corresponding paragraph lists the open years for [country], the U.K. and the U.S. and an [country] examination, and nowhere mentions [country], the assessments or their amount; its roll-forward of unrecognized tax benefits shows no decrease for settlements with taxing authorities in 2025.
Management’s best defense, and our reply
The matter may have closed in 2025 within existing reserves, or [country] may no longer be a major tax jurisdiction for the company, and the standard asks only for open years in major jurisdictions and for unrecognized tax benefits in aggregate, not for the outcome of each assessment. A proposed assessment of about [amount] is modest against the group's tax balances. However, the prior-year 10-K chose to single the matter out with an amount, the 2025 roll-forward shows no settlement, and the current 10-K neither reports an outcome nor says the years remain open, so the reader cannot tell which of these applies; only management can.
The fix
- Add one sentence to the tax note, e.g. 'In 2025 the [country] assessments for 2017-2019 were [withdrawn / settled for $x million / remain under appeal].'
Question for the company
What happened in 2025 to the [country] examination of 2017-2019 and the assessment notices proposing about [amount] of additional tax: were they withdrawn, settled or decided, at what cost, and if they remain open, why does the current 10-K no longer mention them?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Prior-year 10-K (F-50): [country] examination of 2017-2019 disclosed | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 2 | Prior-year 10-K (F-50): assessment notices propose about [amount] of additional tax | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 3 | Prior-year 10-K (F-50): the company says it is contesting the assessments | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
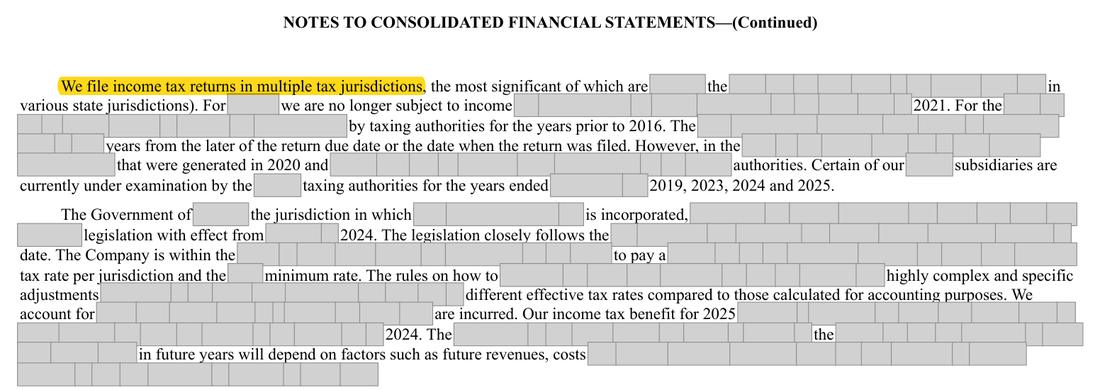
| 4 | Fiscal 2025 10-K (F-47 / F-48): the examinations paragraph now names only [country] | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 5 | Fiscal 2025 10-K (F-47): no settlement with taxing authorities recorded in 2025 | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- We file income tax returns in multiple tax jurisdictions
- What is missing
- the outcome or current status of the [country] examination and of the assessment notices of about [amount] that the prior-year 10-K said were being contested
- Pages looked at
- Fiscal 2025 10-K p.160-167 (Note 21 Income Taxes and Schedule II) and p.71-72 (tax risk factors); third-quarter 2025 Form 10-Q tax note
- Result
- Only 'transfer pricing' hits, on p.71: a general risk factor that tax authorities may challenge the company's structure and transfer pricing arrangements; it names no jurisdiction, examination or assessment. '[country]', 'tax assessment', 'assessment notice' and '[n]' do not appear anywhere in the fiscal 2025 10-K.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.