1.01 The single-segment note gives no significant segment expenses or other segment items, in both years since the new segment standard
Company G · a US-listed specialty pharmaceutical company · Compliance or disclosure gap
In brief
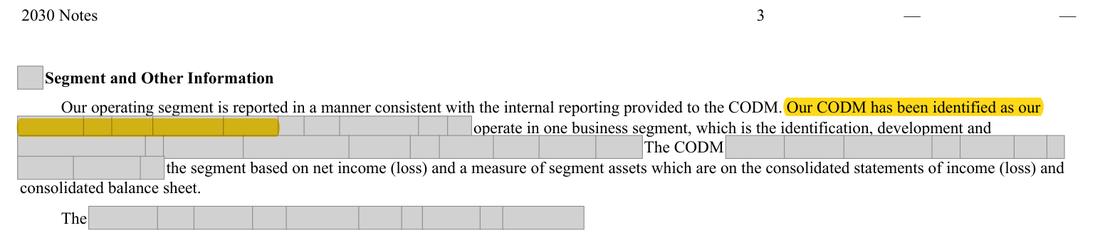
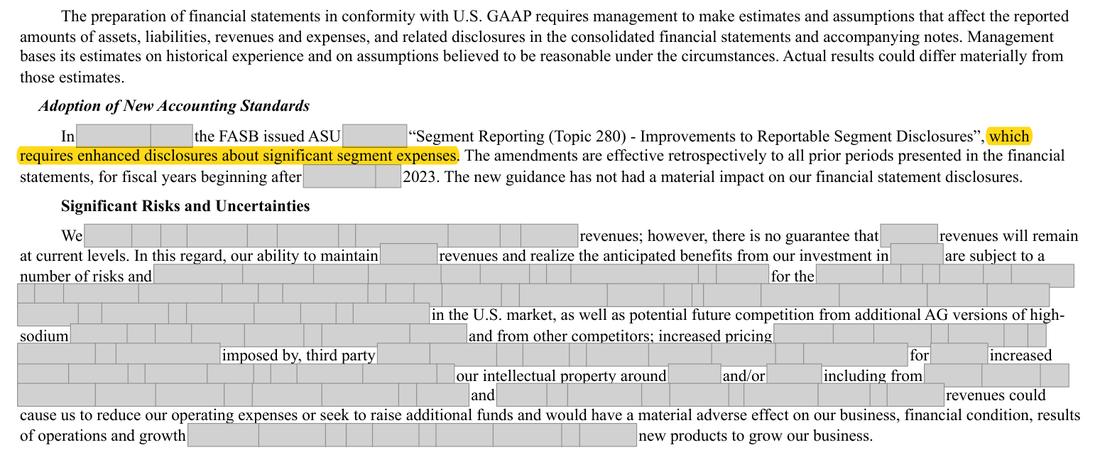
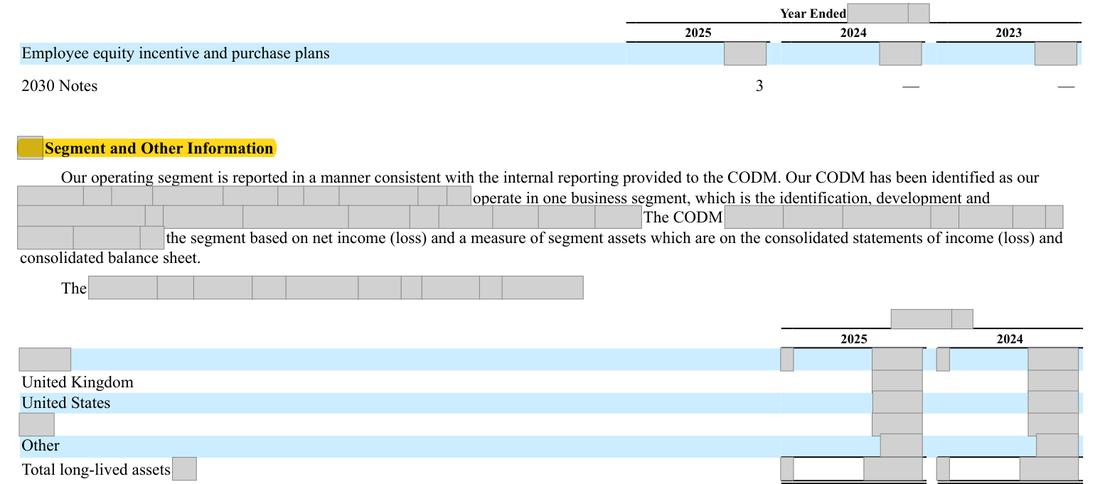
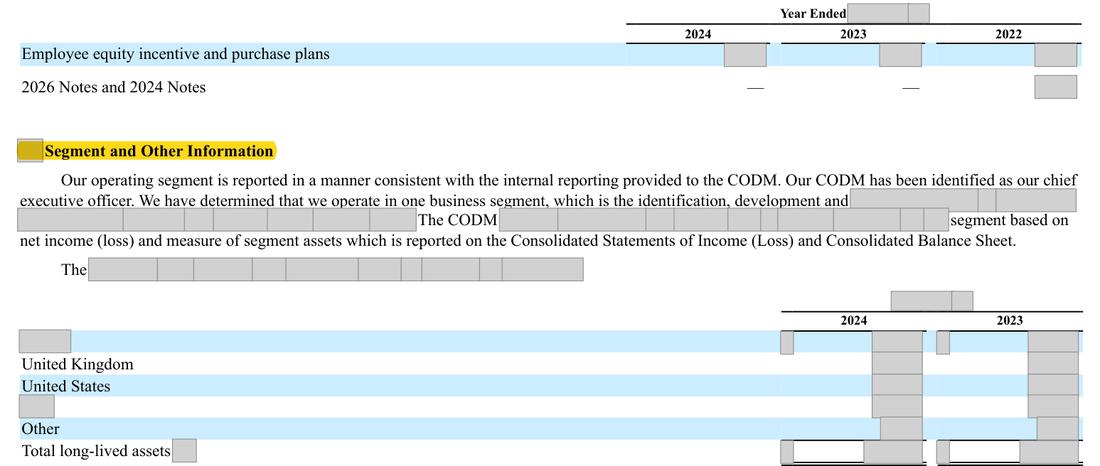
Note 17 names the chief operating decision maker (CODM) and says the CODM uses consolidated net income (loss) and segment assets. It gives no significant segment expense categories or amounts, no 'other segment items' and does not say which expense information the CODM receives. Accounting Standards Update (ASU) 2023-07 requires these for a single-segment company, and the fiscal 2024 note had the same gap: on adopting the standard the company said it had not had a material impact on its disclosures, and the note has not changed since.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Note 17 (fiscal 2025 and fiscal 2024): CODM identified as the President and Chief Executive Officer; measure = net income (loss) and segment assets 'on the consolidated statements'; no expense categories, no amounts, no other segment items. | For the one reportable segment and each year presented: the significant expense categories and amounts regularly provided to the CODM, an 'other segment items' amount with a description of what it contains, and how the CODM uses net income (loss) in assessing performance and allocating resources. |
| What we checked. Note 17 and the Management's Discussion and Analysis (MD&A) expense discussion in both [n]-Ks; whole-report search for the segment-expense wording; the SEC staff comment letter and the company's reply on the fiscal 2024 Form 10-K | |
The rule
ASC 280-10-50-26A to 50-26C (significant segment expenses and other segment items; paraphrase, the Codification text is copyrighted)
Summary; FASB/IFRS text is copyrighted Per reportable segment, disclose significant expense categories regularly provided to the CODM within segment profit, plus the amount and nature of other segment items.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 280-10-50-26A to 50-26C (as amended by ASU 2023-07); paraphrase
Regulation S-X Rule 4-01(a)(1)
Financial statements filed with the Commission which are not prepared in accordance with generally accepted accounting principles will be presumed to be misleading or inaccurate, despite footnote or other disclosures
Version: Text in force at the date of this review · Source: Regulation S-X, 17 CFR 210.4-01(a)(1) (eCFR, as amended)
Why it applies here. Three of the elements the standard asks for are absent in both years since adoption. Saying the measure is on the face of the income statement does not identify which expense categories the CODM receives; accounting-firm summaries of SEC staff remarks at the [date] AICPA conference report that a cross-reference to the primary statements is not enough for a single-segment company.
Why it matters
- Investors cannot see which costs management uses to run the business, the information the new segment standard was written to give them.
- Segment reporting under the new standard is among the most frequent SEC staff comment topics on 2024 and 2025 Forms 10-K; a comment asking which expense information the CODM receives, with an undertaking for future filings, is the realistic outcome. No fine applies.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, segment reporting drew 191 of the 1,774 numbered comments (10.8%): topic 4 of 25 by frequency.
The SEC staff has raised this with other companies
The SEC staff asked Sezzle whether the income statement captions were the only expense information its CODM received, and asked Corcept Therapeutics, a single-segment pharmaceutical company, to confirm it would give the ASU 2023-07 segment disclosures.
Exposure
A staff comment letter asking which expense information the CODM receives and requiring the disclosure in future filings; no fine applies.
Our workings
The company adopted ASU 2023-07 for fiscal 2024 and said in the prior-year 10-K's accounting policies note: 'The new guidance has not had a material impact on our financial statement disclosures.' In both years Note 17 says the company has one business segment, names the CODM, and states that the CODM assesses performance and allocates resources on net income (loss) and a measure of segment assets that are on the consolidated statements. The MD&A in this 10-K breaks research and development expense into four categories that management manages by.
The matrix in the workings tests each element of the amended segment standard in the Accounting Standards Codification (ASC) against both notes: the CODM title is given, the use of the measure is one sentence, and the significant expense categories, the other segment items and the identification of the expense information the CODM receives are absent in both years.
Under ASU 2023-07 a public entity with a single reportable segment gives all the segment-reporting disclosures, including the significant expenses regularly provided to the CODM and the other segment items (the Codification paragraphs cited under the law). Saying that the profit measure is on the face of the income statement does not identify which expense categories the CODM receives; Accounting-firm summaries of SEC staff remarks at the [date] AICPA conference report the view that, for a single-segment entity, a cross-reference to the primary statements is not enough. The staff's review of the fiscal 2024 Form 10-K raised a royalty rate and a license exhibit, not segment reporting, so the point has not been considered and closed by the staff. Segment reporting under the new standard is among the most frequent staff comment themes for calendar 2024 and 2025 [n]-Ks.
| Requirement (ASC 280 as amended by ASU 2023-07) | Fiscal 2025 (this 10-K) | Fiscal 2024 (prior 10-K) | Status |
|---|---|---|---|
| CODM title or position | Given, financial-statement pages (printed F-n; see folios) | Given, financial-statement pages (printed F-n; see folios) | Given |
| How the CODM uses the reported measure | One sentence, financial-statement pages (printed F-n; see folios) | One sentence, financial-statement pages (printed F-n; see folios) | Partial |
| Significant expense categories and amounts regularly provided to the CODM | Not given | Not given | Absent |
| Other segment items: amount and description | Not given | Not given | Absent |
| Which expense information the CODM receives (single segment) | Not given | Not given | Absent |
| Revenue by product and customers at 10% or more (entity-wide) | Given, financial-statement pages (printed F-n; see folios) | Given, financial-statement pages (printed F-n; see folios) | Given |
Management’s best defense, and our reply
Management would argue that with one segment managed on a consolidated basis, the significant segment expenses are simply the expense captions on the face of the consolidated statement of income, which the note points to, so repeating them adds nothing. They could add that the auditor accepted the note in both years and that the staff reviewed the fiscal 2024 Form 10-K and raised no segment comment. However, ASU 2023-07 requires the expense categories regularly provided to the CODM to be disclosed in the segment note itself, and the note does not even say that the CODM receives the face captions rather than a finer breakdown, while the MD&A shows research and development is managed in four categories. A staff review that raises no comment is not acceptance, and accounting-firm summaries of the staff's [date] conference remarks report that a cross-reference to the primary statements is not enough for a single-segment entity, so the defense answers presentation but not the missing identification.
The fix
- Add to Note 17, for each year presented, a table running from total revenues through each significant expense category the CODM regularly receives and an 'other segment items' line (with a description) to net income (loss), and say how the CODM uses net income (loss), for example in budget-to-actual reviews and in allocating research and commercial spend.
Note 17, Segment and Other Information, page F-37: after the CODM sentence
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Note 17 (F-37) names the CODM | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 2 | The only description of the measure; no expense information is given | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 3 | MD&A shows management tracks expenses by category | Document | Form 10-K 2025, page 94 |
| 4 | Prior-year 10-K: the new segment standard was adopted for fiscal 2024 | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 5 | Prior-year Note 17 has the same wording and no expense disclosure | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 6 | The 2025 segment note names the CODM | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 7 | The profit measure is stated, but no expense categories or other segment items follow | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 8 | The 2024 note used the same wording with no expense categories | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 9 | On adopting the amended standard in the 2024 report the Company said its disclosures barely changed | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 10 | The staff reviewed the 2024 Form 10-K in 2025; the reply addresses a royalty-rate comment only, none on segments | Document |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- [n]. Segment and Other Information
- What is missing
- Significant segment expense categories and amounts, other segment items and their description, and which expense information the CODM receives
- Pages looked at
- p.91-94, 121-122, 155-156
- Result
- 'CODM' hits only p.4 (the glossary) and financial-statement pages (printed F-n; see folios) (the two sentences quoted, which name the CODM and the measure); 'segment expenses', 'significant segment expense', 'other segment items' and 'regularly provided' have no hits in this 10-K.
Absence check
- Document
- Form 10-K 2024 (prior year)
- Where it would appear
- [n]. Segment and Other Information
- What is missing
- The same segment expense disclosures for fiscal 2024
- Pages looked at
- Form 10-K 2024 (prior year) p.128, 158-159
- Result
- 'segment expenses' hits only financial-statement pages (printed F-n; see folios) (the policy note describing the standard being adopted); 'CODM' hits p.4 (glossary) and financial-statement pages (printed F-n; see folios) (the sentences naming the CODM); the other terms have no hits.
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- [n]. Segment and Other Information
- What is missing
- the significant segment expenses regularly provided to the chief operating decision maker (CODM), the amount and nature of other segment items, and which expense information the CODM receives
- Pages looked at
- financial-statement pages (printed F-n; see folios) (Note 17), financial-statement pages (printed F-n; see folios) (statement of income), p.128-134 (Note 2), financial-statement pages (printed F-n; see folios) (Note 18)
- Result
- None of the five terms hits anywhere in the 10-K.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.