5.08 Item 1B answered 'Not applicable', and three slips in the MD&A tables and text
Company F · a US-listed networking equipment company · Drafting slip
In brief
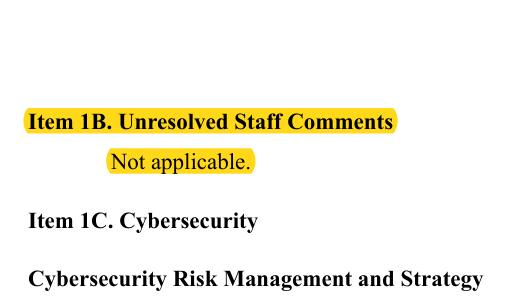
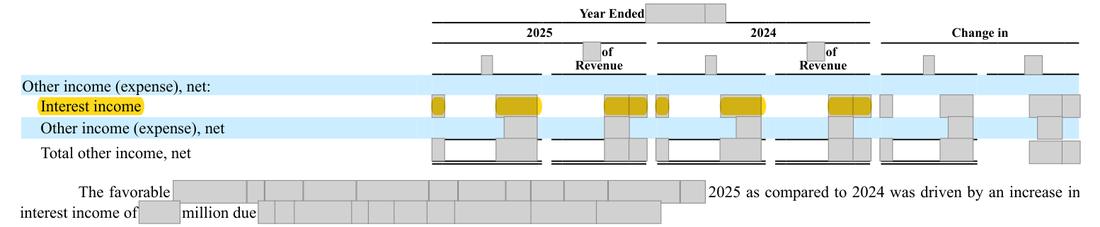
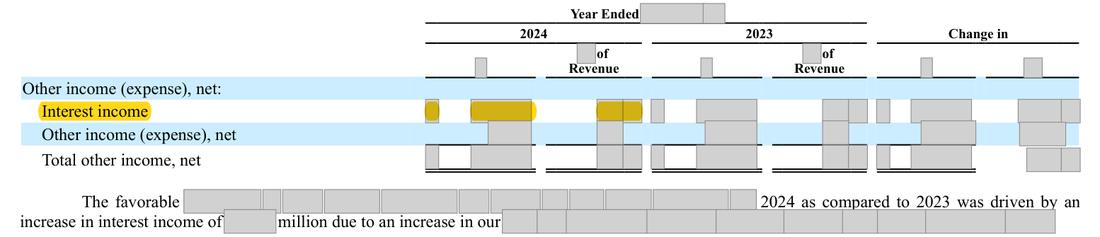
Item 1B is answered 'Not applicable.' although the company is a large accelerated filer, to which the item applies; with no open staff comments the answer is 'None'. In the 2024 comparison table the interest-income line shows [n]% of revenue, while the 2025 table and the prior-year 10-K show [n]% for the same 2024 figure. The cash-flow summary labels the 2025 decrease of ([n]) 'Net increase', and a stray full stop follows '[acquired business].' in the investing narrative. The prior-year Form 10-K gave the same 'Not applicable.' answer to Item 1B.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Item 1B: 'Not applicable.'; 2024 interest income at [n]% of revenue in one table and [n]% in another; 'Net increase' label on a ([n]) decrease; '[acquired business]. and purchases' | Item 1B: 'None.'; [n]% in both tables; label 'Net increase (decrease)' as in the cash-flow statement; '[acquired business] and purchases' |
The rule
Form 10-K, Part I, Item 1B (Unresolved Staff Comments)
If the registrant is an accelerated filer or a large accelerated filer, as defined in Rule 12b-2 of the Exchange Act
Version: Text in force at the date of this review · Source: SEC Form 10-K, General Instructions and Items (as amended)
Why it applies here. each is a transcription or label slip; none changes a reported amount.
Why it matters
No reported amount is affected; the Item 1B wording misdescribes the item's application to the company and could draw a staff comment on the next review.
Exposure
Drafting only; no figure in the statements changes.
Our workings
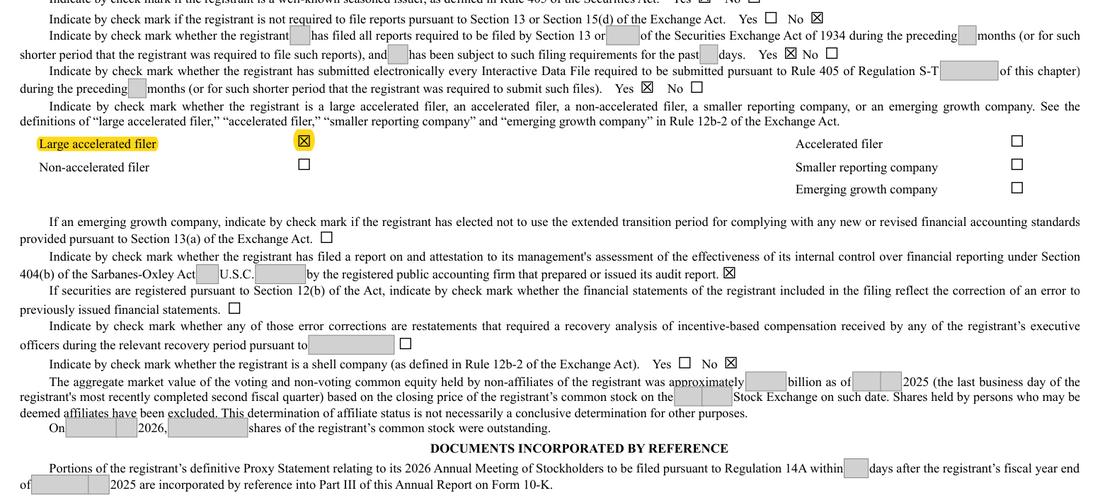
the cover page ticks 'Large accelerated filer' and Item 1B reads 'Not applicable.' (the prior-year 10-K used the same words). The staff's review of the fiscal 2023 10-K was completed on [date], so no comment was open at the 180-day point before the 2025 year end and nothing is owed under Item 1B.
the [n]-vs-2024 table prints 2024 interest income at [n]% of revenue; the [n]-vs-2023 table two pages later prints the same [n] at [n]%; the prior-year 10-K printed [n]%.
the MD&A cash-flow table calls the ([n]) line 'Net increase' while the statement calls it 'NET INCREASE (DECREASE)'.
Management’s best defense, and our reply
The company would say Item 1B has nothing to report, so 'Not applicable' and 'None' tell the reader the same thing, and the other slips are visible as such to any reader of the tables. It may add that the prior-year 10-K used the same Item 1B wording without staff comment. However, 'Not applicable' states that the item does not apply to the registrant, which is wrong for a large accelerated filer, and a comparative percentage that differs between two tables of the same report is a correction, not a judgment.
The fix
- Item 1B: replace 'Not applicable.' with 'None.'; print [n]% for 2024 interest income in the [n]-vs-2023 table; relabel the summary line 'Net increase (decrease) in cash, cash equivalents and restricted cash'; delete the full stop after '[acquired business]'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The cover page states the company is a large accelerated filer | Document | Form 10-K 2025, unnumbered page |
| 2 | Slip 1: Item 1B answered 'Not applicable' although the item applies to a large accelerated filer | Document | Form 10-K 2025, page 47 |
| 3 | The [n]-vs-2024 table shows 2024 interest income of [n] at [n]% of revenue | Document | Form 10-K 2025, page 56 |
| 4 | Slip 2: the [n]-vs-2023 table shows the same [n] at [n]% | Document | Form 10-K 2025, page 58 |
| 5 | The prior-year 10-K printed [n]% for 2024 interest income | Document | Form 10-K 2024 (prior year), page 60 |
| 6 | Slip 3: the MD&A summary labels a decrease 'Net increase' | Document | Form 10-K 2025, page 59 |
| 7 | The cash-flow statement labels the same line 'Net increase (decrease)' | Document | Form 10-K 2025, page 72 |
| 8 | Slip 4: stray full stop after '[acquired business]' mid-sentence | Document | Form 10-K 2025, page 59 |
| 9 | Prior-year Item 1B gives the same 'Not applicable' answer | Document | Form 10-K 2024 (prior year), page 51 |
| 10 | Prior-year cover page ticks large accelerated filer, a filer to which Item 1B applies | Document | Form 10-K 2024 (prior year), unnumbered page |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.