2.01 Item 9B in both years reports one trading plan for the Chief Executive Officer; later Forms 4 refer to a second plan for family trusts adopted the same day
Company F · a US-listed networking equipment company · SEC-style question
In brief
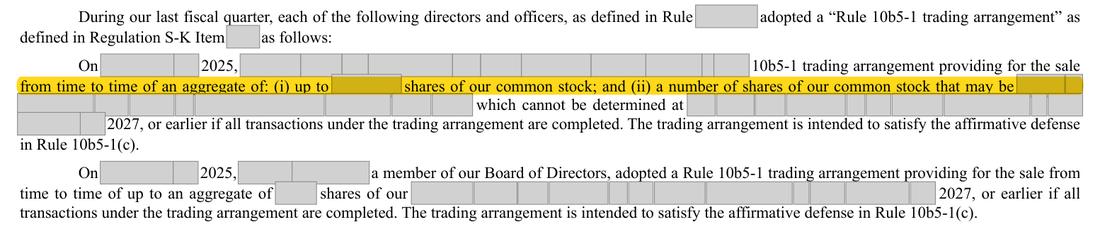
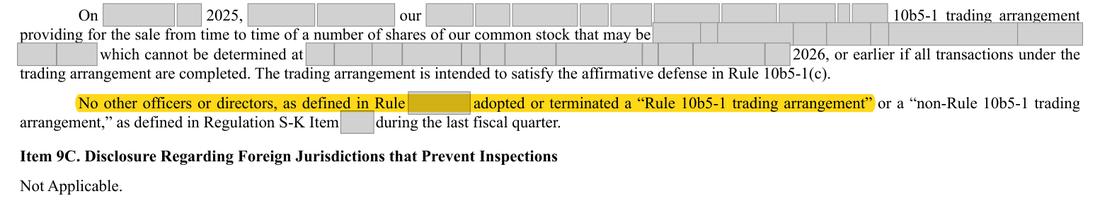
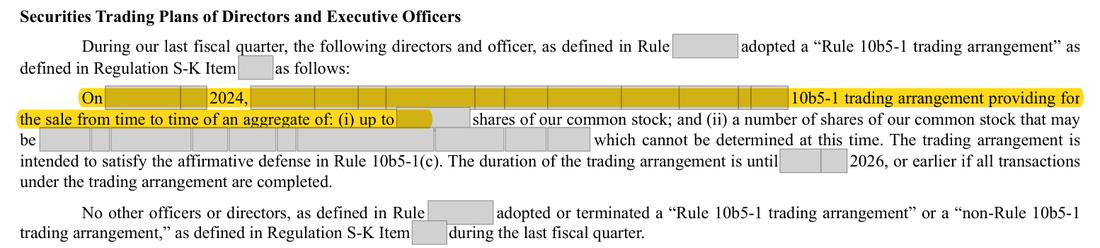
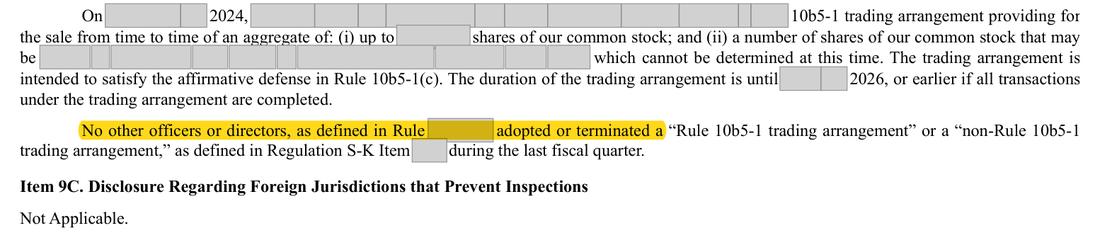
Item 9B says the Chief Executive Officer adopted one Rule 10b5-1 trading arrangement on [date], for up to [n] shares plus shares earned under performance-based units. Forms 4 filed in [date] report sales by the children's trusts, of which the Chief Executive Officer is trustee, under a separate plan 'entered into by the reporting person for the benefit of the reporting person's relatives' on the same date. Item 9B does not say whether the disclosed arrangement includes that plan. The prior-year Form 10-K shows the same pattern: its Item 9B describes one arrangement adopted by the Chief Executive Officer on [date] for up to [n] shares and says no other was adopted, while the Form 4 for sales on [date] cites a second plan of that date entered into for the benefit of relatives.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Item 9B: one arrangement adopted [date] for up to [n] shares plus performance-unit shares; nothing on a plan for the trusts | Either a statement that the disclosed arrangement and its [n]-share aggregate cover the trusts' plan, or the trusts' plan disclosed with its own date, duration and aggregate number of shares |
The rule
Regulation S-K Item 408(a)(1)
Disclose whether, during the registrant's last fiscal quarter (the registrant's fourth fiscal quarter in the case of an annual report), any director or officer (as defined in § 240.16a-1(f) of this chapter) adopted or terminated:
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.408 (eCFR text as in force for fiscal 2025)
Regulation S-K Item 408(a)(2)
The aggregate number of securities to be purchased or sold pursuant to the trading arrangement.
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.408 (eCFR text as in force for fiscal 2025)
SEC Division of Corporation Finance, Regulation S-K Compliance and Disclosure Interpretation 133A.02
Item 408(a) applies to any Rule 10b5-1 trading arrangement or non-Rule 10b5-1 trading arrangement covering securities in which an officer or director has a direct or indirect pecuniary interest that is reportable under Section 16 that the officer or director has made the decision to adopt or terminate.
Version: Text in force at the date of this review · Source: SEC Division of Corporation Finance, Regulation S-K Compliance and Disclosure Interpretations, Question 133A.02
Why it applies here. there appear to be two plans adopted on the same day. The disclosure requirement covers any arrangement in securities in which the officer has a reportable pecuniary interest that the officer decided to adopt. Whether the trusts' plan is caught, and whether the [n] aggregate already includes it, cannot be told from the report.
Why it matters
If the trusts' plan is a separate arrangement within the requirement, Item 9B understates the arrangements adopted in the quarter and the aggregate number of shares that may be sold under them.
Exposure
No penalty on the facts known. If the answer shows a separate covered arrangement, the realistic consequence is a staff comment and disclosure of it in the next periodic report.
Our workings
Item 9B (p.96, p.96) reports that on [date] the Chief Executive Officer adopted a Rule 10b5-1 trading arrangement for the sale of up to [n] shares and an undetermined number of performance-unit shares, and states that no other officer or director adopted or terminated an arrangement in the quarter. A Form 4 filed on [date] reports sales by two trusts for the officer's children 'pursuant to a Rule 10b5-1 trading plan entered into by the reporting person for the benefit of the reporting person's relatives on [date]', and, in a separate footnote, sales by a family trust under 'a Rule 10b5-1 trading plan adopted by the reporting person on [date]'. The same Form 4 says the officer is trustee of the children's trusts with shared voting and investment control, and reports those holdings. The Form 4 filed on [date] carries the same two footnotes, and the Inline XBRL of the 10-K tags only the three fourth-quarter arrangements that Item 9B lists.
Management’s best defense, and our reply
Management would say the Chief Executive Officer signed one set of plan documents on [date] covering the officer's own accounts and the trusts, and that the [n]-share aggregate in Item 9B already counts the trusts' shares. It could also argue that the officer disclaims beneficial ownership of the trusts' shares, so the trusts' plan is not one in which the officer has a pecuniary interest and is outside the requirement. Either answer would close the point, but neither can be read from the report: the Forms 4 describe two plans, and the Item 9B text describes one, so the question stands until the company confirms which.
The fix
- Confirm whether the [n]-share aggregate covers the trusts' plan; if it does not and the plan is covered, disclose it in the next Form 10-Q with its adoption date, duration and aggregate number of shares, for example: 'On [date], our Chief Executive Officer, as trustee, also adopted a Rule 10b5-1 trading arrangement on behalf of trusts for the benefit of family members, providing for the sale of up to [number] shares, until [date].'
Question for the company
Does the Rule 10b5-1 arrangement reported in Item 9B as adopted by the Chief Executive Officer on [date] (up to [n] shares plus performance-unit shares) include the plan adopted the same day for the benefit of the officer's relatives that later Forms 4 refer to? If it is a separate arrangement, why was it not reported in Item 9B?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Item 9B: one arrangement for the Chief Executive Officer, with its aggregate | Document | Form 10-K 2025, page 96 |
| 2 | Item 9B: no other arrangement adopted in the quarter | Document | Form 10-K 2025, page 96 |
| 3 | Form 4 of [date]: sales by the children's trusts under a plan for relatives adopted on [date] | Document | |
| 4 | Same Form 4: the family trust's sales under the officer's own plan of the same date | Document | |
| 5 | Same Form 4: the officer is trustee of the selling trusts | Document | |
| 6 | The prior-year Item 9B describes one Rule 10b5-1 arrangement for the chief executive officer, adopted on [date], for up to [n] shares | Document | Form 10-K 2024 (prior year), page 104 |
| 7 | The prior-year Item 9B states no other arrangement was adopted in the fourth quarter of 2024 | Document | Form 10-K 2024 (prior year), page 104 |
| 8 | The chief executive officer's Form 4 for sales on [date] cites a second plan of the same date, entered into for the benefit of her relatives | Document | |
| 9 | The same Form 4 cites, separately, the plan adopted by the reporting person on [date] (the one Item 9B describes) | Document | |
| 10 | The shares sold under the relatives' plan are held in trusts of which the chief executive officer is co-trustee | Document |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.