1.05 The segment note now names only two significant segment expenses where last year it named five
Company F · a US-listed networking equipment company · SEC-style question
In brief
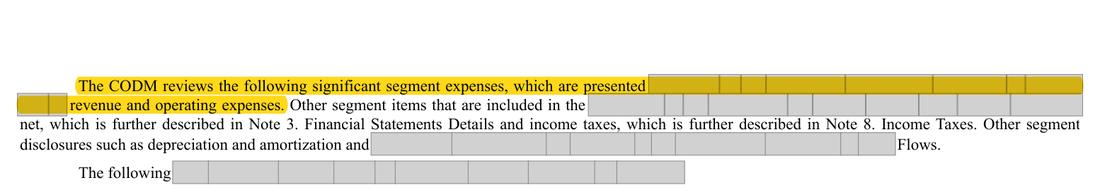
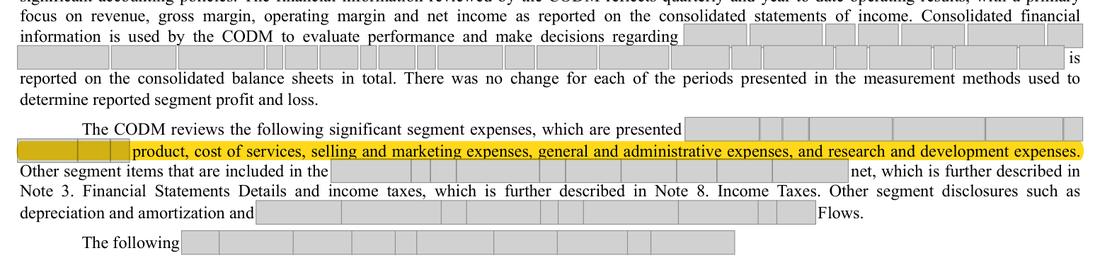
Note 9 says the chief operating decision maker (CODM) reviews two significant segment expenses: cost of revenue and operating expenses. The prior-year Form 10-K said the same CODM reviews five: cost of product, cost of services, selling and marketing, general and administrative, and research and development. Nothing in the note explains the change. The note should say which expense categories the CODM is regularly given.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Note 9: significant segment expenses are 'cost of revenue and operating expenses', with no amounts in the note and no explanation of the change from the five captions named in the prior-year note | The expense categories the CODM is regularly provided with, named as in the CODM package (the five income-statement captions if that is still what the CODM receives), or a statement that the CODM package changed in 2025 |
The rule
ASC 280-10-50-26A to 50-26C (as amended by ASU 2023-07)
Summary; FASB/IFRS text is copyrighted Per reportable segment, disclose significant expense categories regularly provided to the CODM within segment profit, plus the amount and nature of other segment items.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 280-10-50-26A to 50-26C (as amended by ASU 2023-07); paraphrase
Why it applies here. either the CODM package changed in 2025 (two totals instead of five captions), which the note does not say, or the CODM still receives the five captions and the note now describes them in a more aggregated way than the segment standard asks for. The note gives no amounts for either category; it relies on the face of the income statement. Context: in 2024 the SEC staff asked the company what information is provided to its CODM, and the staff's [date] public remarks said that for single-segment entities a cross-reference to the primary statements is not enough and that broad expense labels draw comment.
Why it matters
A reader cannot tell whether the CODM's information changed in 2025 or whether the description was simply shortened. Segment disclosures for single-segment companies are a current staff focus, and a description of significant expenses as two broad totals is the pattern the staff has questioned.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, segment reporting drew 191 of the 1,774 numbered comments (10.8%): topic 4 of 25 by frequency.
Exposure
No penalty. If the answer shows the description is incomplete, the realistic consequence is an SEC staff comment and an undertaking to revise the note in future filings.
Our workings
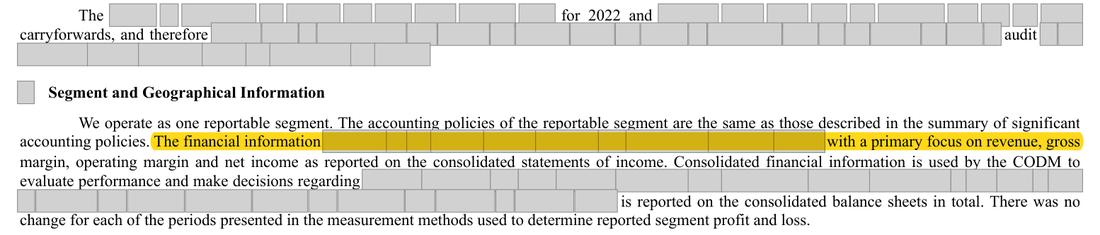
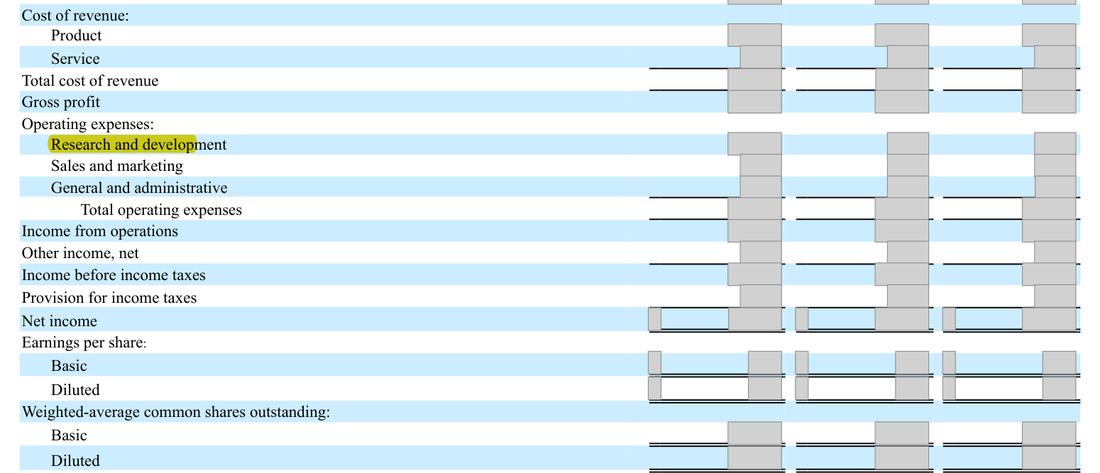
the fiscal 2025 note (p.94, p.94) names 'cost of revenue and operating expenses' as the significant segment expenses. The fiscal 2024 note (prior-year Form 10-K, p.101) named cost of product, cost of services, selling and marketing, general and administrative, and research and development. Both notes say the CODM reviews quarterly and year-to-date results 'as reported on the consolidated statements of income', and the 2025 statement of income still shows all five captions separately.
Management’s best defense, and our reply
Management would say that cost of revenue and operating expenses are exactly the totals on the face of the income statement, that every component is presented there, and that the CODM reviews that statement, so nothing the CODM sees is hidden. It could add that a single-segment company managed on a consolidated basis may point to the primary statements, and that the staff closed its 2024 review of the single-segment conclusion without asking for more. However, the note itself says the CODM reviews 'significant segment expenses' and names only two totals this year where it named five last year, with no reason given; whichever is right, the two notes cannot both describe the same CODM package. The question is therefore a fair one and the answer will settle it.
The fix
- Name the expense categories the CODM is regularly given, for example: 'The CODM regularly reviews cost of product, cost of services, research and development, sales and marketing, and general and administrative expenses, which are presented separately on the consolidated statements of income', and say so if the CODM package changed in 2025.
Question for the company
Which expense categories was the chief operating decision maker regularly provided with in 2025: the five income-statement captions named in the fiscal 2024 note, or only total cost of revenue and total operating expenses? If the five captions, will the note name them again; if the package changed, will the note say so?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Fiscal 2025 note names two significant segment expenses | Document | Form 10-K 2025, page 94 |
| 2 | The CODM reviews the results as reported on the consolidated statements of income | Document | Form 10-K 2025, page 93 |
| 3 | The 2025 statement of income still presents research and development, sales and marketing and general and administrative as separate captions | Document | Form 10-K 2025, page 69 |
| 4 | Fiscal 2024 note named five significant segment expenses | Document | Form 10-K 2024 (prior year), page 101 |
| 5 | The SEC staff has already asked the company what information its CODM receives | Document |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.