7.03 MD&A defines Free Cash Flow as a non-GAAP measure but the 10-K never presents it
Company E · a US-listed home furnishings retailer · Drafting slip
In brief
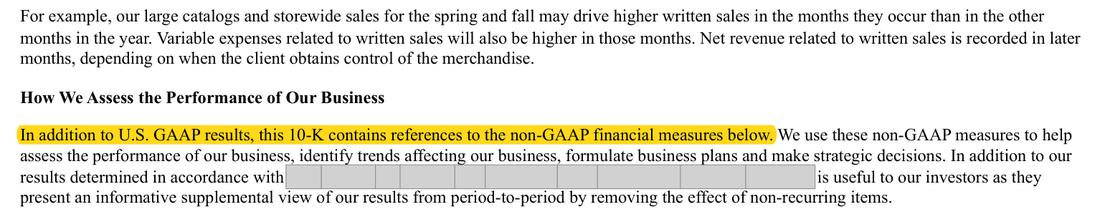
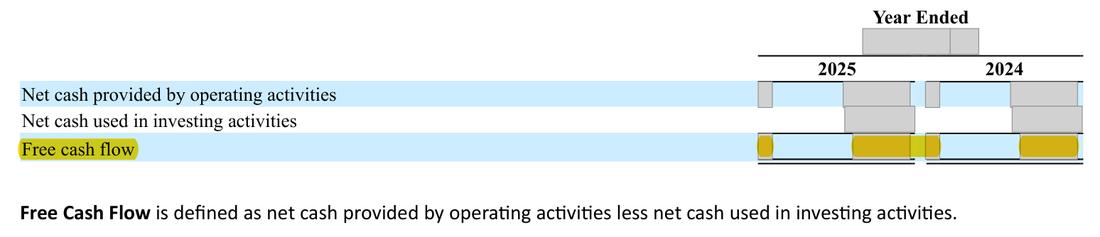
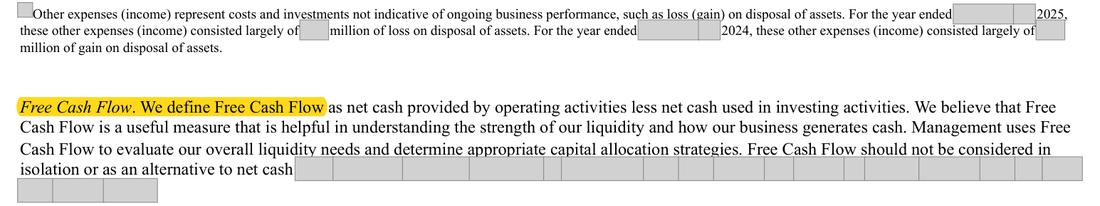
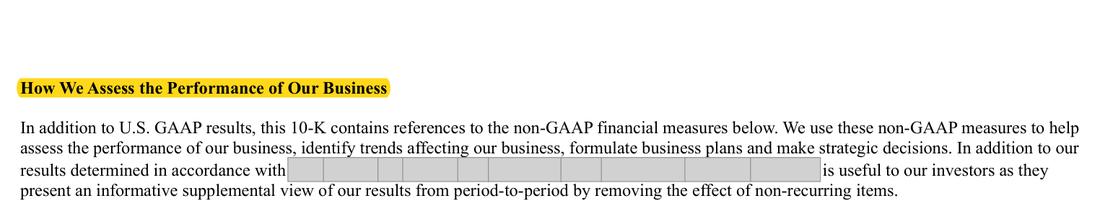
The MD&A says the 10-K contains references to the non-GAAP measures listed, and the list now includes Free Cash Flow with its definition and a statement of how management uses it. No Free Cash Flow amount or reconciliation follows anywhere in the 10-K. The earnings release furnished the same day does present it, at [amount] for 2025 with a reconciliation. The definition is either a leftover from the release or the measure was meant to be shown.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Free Cash Flow is defined as a non-GAAP measure in the 10-K, with no amount; the earnings release shows Free cash flow of [amount] | Either present Free Cash Flow with the most directly comparable GAAP measure and a reconciliation, or delete the definition from the 10-K |
The rule
Regulation S-K Item 10(e)(1)(i)(B)
A reconciliation (by schedule or other clearly understandable method), which shall be quantitative for historical non-GAAP measures presented
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.10, as amended to the date of filing
Why it applies here. because no amount is shown, the Item 10(e) conditions are not engaged, so this is a drafting point; but a reader is told the report contains a measure it does not contain.
Why it matters
The MD&A tells readers the report contains a non-GAAP liquidity measure that it does not present.
Exposure
No amount is presented, so no non-GAAP presentation condition is breached.
Our workings
the MD&A introduces the non-GAAP measures it contains, and after EBITDA and adjusted EBITDA defines Free Cash Flow as net cash provided by operating activities less net cash used in investing activities. The 10-K presents EBITDA and adjusted EBITDA with a reconciliation but gives no Free Cash Flow figure. The earnings release of [date] reconciles operating cash flow to Free cash flow of [amount] for 2025. The prior-year Form 10-K defined only EBITDA and adjusted EBITDA.
Management’s best defense, and our reply
The company would say the definition is harmless: it explains a term used in the earnings release and investor presentation, and with no figure in the 10-K there is nothing for Item 10(e) to regulate. That is correct as to compliance, which is why this is only a drafting point; however, the introductory sentence tells readers the 10-K contains the measure, which it does not.
The fix
- Delete the Free Cash Flow paragraph from the next Form 10-K, or present the amount with net cash provided by operating activities shown first and a reconciliation.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | the 10-K says it contains the measures defined below | Document | Form 10-K 2025, page 44 |
| 2 | Free Cash Flow is defined, after the adjusted EBITDA reconciliation, with no amount | Document | Form 10-K 2025, page 46 |
| 3 | the earnings release presents and reconciles Free cash flow | Document |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Free Cash Flow. We define Free Cash Flow
- What is missing
- a Free Cash Flow amount and its reconciliation to net cash provided by operating activities
- Pages looked at
- p.42-50 (MD&A incl. liquidity and cash flows)
- Result
- 'Free Cash Flow' hits p.44 (a statement that the measures are not intended to be measures of free cash flow) and p.46 (the definition itself); '[n]' hits p.50, the decrease in operating lease liabilities, which is unrelated; '[n]' and '[n]' have no hits.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.