4.06 Risk factors say the auditor is unable to express an opinion on internal control, but the auditor's report gives an adverse opinion
Company E · a US-listed home furnishings retailer · Presentation point
In brief
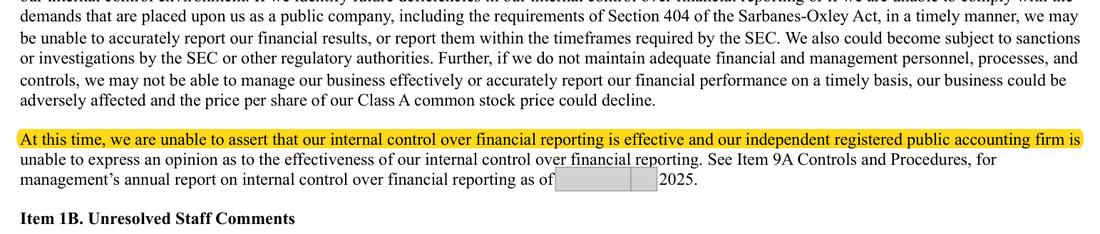
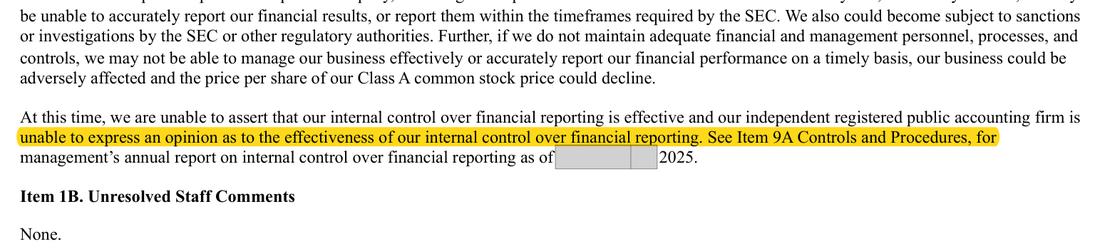
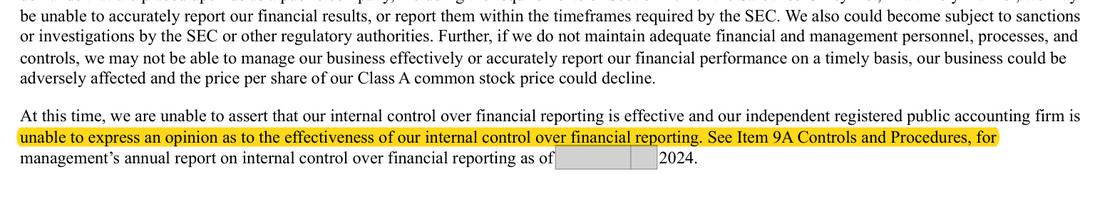
The last paragraph of the internal control risk factor says the independent registered public accounting firm 'is unable to express an opinion as to the effectiveness' of internal control over financial reporting (ICFR). The auditor's report in the same Form 10-K does express an opinion: an adverse one, stating that the Company did not maintain effective ICFR as of [date]. The same sentence was carried in the prior-year Form 10-K, where the auditor had also given an adverse opinion.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Item 1A (p.37): the auditor 'is unable to express an opinion as to the effectiveness' of ICFR; auditor's report (p.53): 'Also in our opinion, the Company did not maintain, in all material respects, effective internal control' | Item 1A states the actual position: management concluded that ICFR was not effective as of [date] and the independent registered public accounting firm issued an adverse opinion on ICFR because material weaknesses existed |
| What we checked. Item 1A internal control risk factor against the auditor's report, Item 9A management's report, and the same passages in the prior-year Form 10-K | |
The rule
Exchange Act Rule 12b-20
there shall be added such further material information, if any, as may be necessary to make the required statements, in the light of the circumstances under which they are made not misleading
Version: Text in force at the date of this review · Source: 17 CFR 240.12b-20 (eCFR text as of the law pack date)
Regulation S-K Item 308(b)
is an accelerated filer or a large accelerated filer (as defined in § 240.12b-2 of this chapter), provide the registered public accounting firm's attestation report on the registrant
Version: Text in force at the date of this review · Source: 17 CFR 229.308(b) (eCFR text as of the law pack date)
Why it applies here. 'unable to express an opinion' is the language of a disclaimer of opinion, a different form of report from the adverse opinion actually issued; the sentence is a template carried forward and no longer matches the attestation. The company is an accelerated filer, so Item 308(b) requires the attestation report, and it was given. Nothing is omitted - the correct position is in Item 9A and the auditor's report - so the point is an internal inconsistency, not a missing disclosure; Rule 12b-20 is engaged because a statement about the auditor's report that the report itself contradicts can mislead a reader of Item 1A who does not follow the cross-reference.
Why it matters
A reader of Item 1A is told the auditor could not form a view on internal control when the auditor in fact concluded that internal control was not effective; the risk factor understates the definiteness of the adverse finding. The sentence has now been carried unchanged into two consecutive annual reports.
Exposure
No fixed penalty. The realistic consequence is a staff comment asking the company to conform the risk factor to the attestation report, and a future-filings undertaking.
Our workings
the risk factor on p.37 says the auditor is unable to express an opinion on the effectiveness of ICFR. The auditor's report on p.53 contains an opinion on ICFR, and that opinion is adverse ('did not maintain, in all material respects, effective internal control over financial reporting as of [date]'). Item 9A (p.83) records management's conclusion that ICFR 'was not effective'.
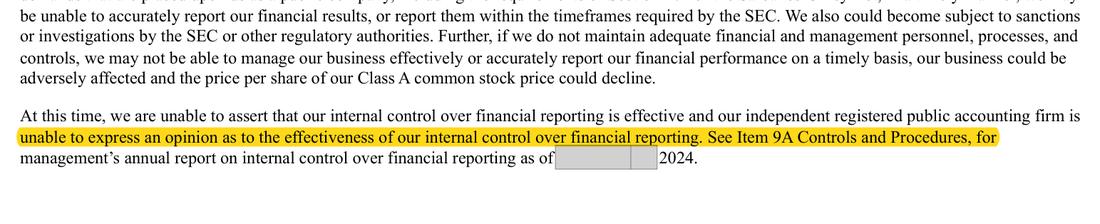
the fiscal 2024 Form 10-K carried the identical risk-factor sentence (p.41) while its auditor's report (p.55) also gave an adverse ICFR opinion.
| Place | What it says about the ICFR opinion | Year |
|---|---|---|
| Item 1A, p.37 | auditor 'unable to express an opinion' | fiscal 2025 |
| Auditor's report, p.53 | adverse: 'did not maintain ... effective internal control' | fiscal 2025 |
| Item 9A, p.83 | management: ICFR 'was not effective' | fiscal 2025 |
| Prior-year Item 1A, p.41 | auditor 'unable to express an opinion' | fiscal 2024 |
| Prior-year auditor's report, p.55 | adverse: 'did not maintain ... effective internal control' | fiscal 2024 |
Management’s best defense, and our reply
The finance team would say the sentence is a short risk-factor pointer, not the attestation itself: it sends the reader straight to Item 9A, where management's report and the auditor's adverse attestation are set out in full, so no investor reading the filing is misled about the internal control position. They would add that 'unable to express an opinion as to the effectiveness' was meant in plain words - the auditor cannot opine that controls are effective - which is true. The answer: in an auditor's report, 'unable to express an opinion' is the language of a disclaimer, which is a different report from the adverse opinion actually issued, and Item 1A is read on its own by many investors. A cross-reference points to the correct statement but does not correct an inaccurate one, and the same template sentence has now survived two years in which the auditor gave adverse opinions.
The fix
- Replace the sentence with: 'As of [date], management concluded that our internal control over financial reporting was not effective, and our independent registered public accounting firm issued an adverse opinion on the effectiveness of our internal control over financial reporting. See Item 9A.'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Item 1A paragraph on the current position of ICFR and the auditor | Document | Form 10-K 2025, page 37 |
| 2 | Item 1A says the auditor is unable to express an opinion on ICFR | Document | Form 10-K 2025, page 37 |
| 3 | the auditor's report gives an adverse opinion on ICFR as of [date] | Document | Form 10-K 2025, page 53 |
| 4 | Item 9A: management concluded ICFR was not effective | Document | Form 10-K 2025, page 83 |
| 5 | prior-year Form 10-K carried the same sentence | Document | Form 10-K 2024 (prior year), page 41 |
| 6 | prior-year auditor's report was also an adverse ICFR opinion | Document | Form 10-K 2024 (prior year), page 55 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.