2.01 A director determined to be independent had a consulting agreement with the Company that the independence discussion does not describe
Company E · a US-listed home furnishings retailer · SEC-style question
In brief
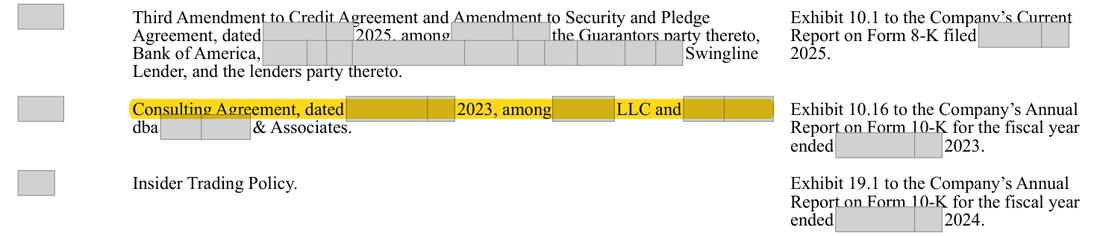
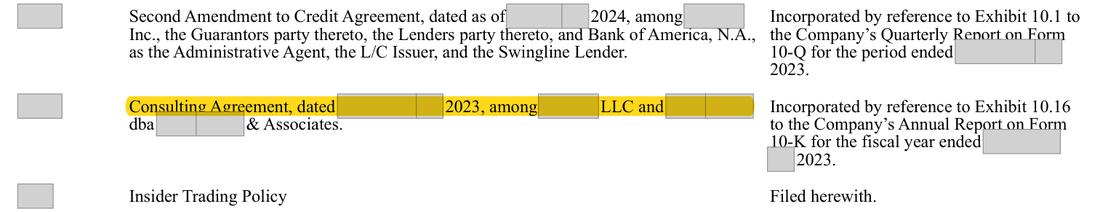
Exhibit 10.[n] is a consulting agreement of [date] between the Company's operating subsidiary and one of its non-employee directors, paying [amount] a week and ending when fees reach [amount], a cap set so as not to disqualify the director as independent under Nasdaq rules. The board has determined that director to be independent, and the independence discussion incorporated into Item 13 does not mention the arrangement. The 2025 director compensation table shows no other compensation for him, so nothing appears to have been paid in 2025; we ask what was paid earlier, whether the agreement has ended, and why it is not described.
The evidence, as filed
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Consulting agreement of [date] with a director, still listed as a material contract; fee capped at [amount]; no other compensation for that director in the 2025 director compensation table; director determined independent; no description of the arrangement in the independence discussion. | A description, by category, of the consulting arrangement as a relationship the board considered in finding the director independent, with the amounts paid under it and whether it has ended. |
The rule
Regulation S-K Item 407(a)(3)
For each director and nominee for director that is identified as independent, describe, by specific category or type, any transactions, relationships or arrangements not disclosed pursuant to Item 404(a)
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.407(a)(3) (eCFR current text)
Why it applies here. a paid consulting arrangement priced to stay one dollar under the Nasdaq compensation bright line is precisely a relationship the board must consider when it determines independence. Whether fees were paid in 2023 or 2024, whether the cap was reached and whether the agreement, still listed as a material contract, has ended cannot be seen from the filings, so the point is a question.
Why it matters
Shareholders voting on directors and reading the committee independence statements cannot see that a director determined to be independent had a consulting agreement with the Company designed around the independence threshold, or what was paid under it.
Exposure
A question for the board; if the arrangement was considered, the realistic outcome is a staff comment asking for the Item 407(a)(3) description in the next proxy statement.
Our workings
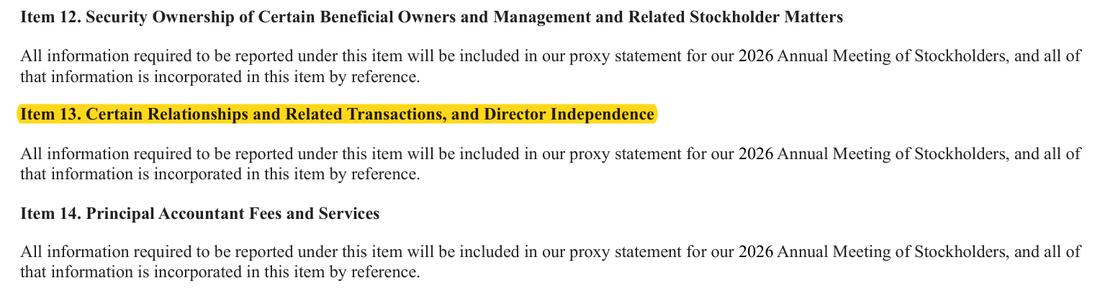
the exhibit index lists a consulting agreement dated [date] between the Company, LLC and a non-employee director, incorporated from the 2023 Form 10-K. The agreement pays [amount] per week and terminates when fees reach [amount], a cap the agreement states is set so as not to [wording masked]. The director signs this Form 10-K as a director, and the proxy statement incorporated into Items 10 and 13 lists him among the directors the board determined to be independent. The proxy does not describe the consulting arrangement. Law: Item 407(a)(3) asks, for each director identified as independent, for a description by category of any transaction, relationship or arrangement not disclosed under Item 404(a) that the board considered in determining independence.
the director compensation table for 2025 in the proxy statement shows no other compensation for this director, so nothing appears to have been paid under the agreement in 2025.
| Term of the agreement | Figure |
|---|---|
| Weekly fee | [amount] |
| Fee cap | [amount] |
| Weeks of service to reach the cap | [n] / [n] = [n] |
| Nasdaq compensation bright line (cap plus one dollar) | [n] + 1 = [n] |
Management’s best defense, and our reply
The Company can argue that the cap keeps payments below the [amount] bright line and below the Item 404(a) threshold, that the agreement is publicly filed as an exhibit, and that Item 407(a)(3) needs only a description by category, which a board may regard as unnecessary for a small, completed engagement. The 2025 director compensation table, which shows no other compensation for the director, supports that the work was finished before 2025. Those points have weight, so this is a question; but the rule asks for a description of any arrangement the board considered, and an arrangement priced one dollar under the bright line, still listed as a material contract, is one the board must have considered.
The fix
- In the next proxy statement, describe under director independence the consulting agreement, the services, the amounts paid under it and the board's consideration of it; remove the exhibit from the index if the agreement has ended and no longer needs to be filed.
Question for the company
What was paid under the consulting agreement with the non-employee director in 2023 and 2024 (the 2025 director compensation table shows no other compensation), has the agreement ended, and did the board consider it in finding the director independent; if so, why does the independence discussion incorporated into Item 13 not describe it under Item 407(a)(3)?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | the consulting agreement with a director is listed as a material contract | Document | Form 10-K 2025, page 91 |
| 2 | the consultant signs the Form 10-K as a director | Document | Form 10-K 2025, page 95 |
| 3 | the weekly consulting fee | Document | |
| 4 | the fee cap is set by reference to the independence bright line | Document | |
| 5 | proxy statement: the director is determined independent | Document | |
| 6 | proxy statement director compensation table for 2025: no other compensation for the director | Document | |
| 7 | the column headings of the 2025 director compensation table | Document |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Item 13. Certain Relationships and Related Transactions, and Director Independence
- What is missing
- a description of the consulting arrangement with the director as a relationship considered in the independence determination
- Pages looked at
- p.87-88, [n]
- Result
- 'Consulting Agreement' hits only p.91 (the exhibit index entry); '[name]' hits p.91 (the exhibit) and p.95 (his signature as director); 'consult' hits p.3, 6 and [n] (design consultants), p.37 (cybersecurity advisers), p.69 and [n] (equity awards to consultants) and p.91 (the exhibit); 'independent director' hits only p.34 (a risk factor on controlled-company rules). None describes the arrangement in the independence discussion, and the proxy statement incorporated into Item 13 does not mention it either.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.