1.06 The 2025 PSU grant added a relative-TSR goal valued by Monte Carlo simulation, but none of the valuation assumptions are given
Company E · a US-listed home furnishings retailer · SEC-style question
In brief
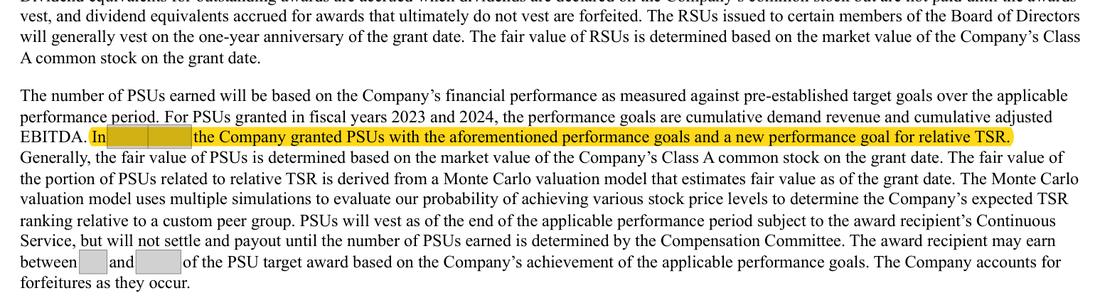
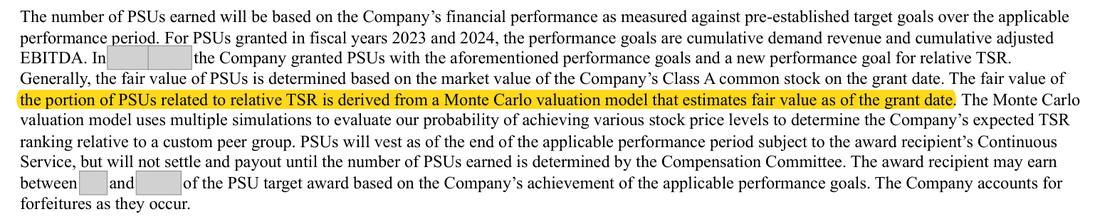
In [date] the company granted PSUs with a new relative total shareholder return (TSR) goal, and Note 8 says that portion is valued with a Monte Carlo model. The note does not give the expected volatility, risk-free rate, expected term, dividend yield or the way the peer group enters the model. The 2025 PSU grant carried [n] units at a weighted grant-date fair value of [amount] (about [n], 4.89% of pre-tax income); how much of that is the TSR slice is not stated.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Note 8 names the Monte Carlo model for the relative-TSR portion of the [date] PSUs and describes it in general terms; no assumption used in it is disclosed. | For the year of grant, the significant assumptions used in the Monte Carlo valuation (expected volatility of the company and the peer group, risk-free rate, performance period, dividend yield, correlation), or a statement of why they are not significant. |
The rule
FASB ASC 718-10-50-1 to 50-2, including 50-2(f) (paraphrase; the Codification text is copyrighted)
Summary; FASB/IFRS text is copyrighted Disclose share-based arrangement terms, fair-value methods and assumptions, award activity, compensation cost and tax effects, and unrecognised cost with weighted-average recognition period.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 718-10-50-2 (as amended by ASU 2016-09)
Why it applies here. the share-based payment Topic asks for a description of the method and of the significant assumptions used in the year to estimate fair value; with a market condition the volatility and correlation inputs drive the value directly. Whether the TSR slice is large enough for its assumptions to be significant depends on its share of the [n], which only management knows, so the point is a question rather than a settled gap.
Why it matters
Readers cannot judge how the market-condition element of executive PSUs was valued, and the note may fall short of the Topic's assumption disclosure if the TSR slice is material.
Exposure
None while the point is open; if the TSR slice proves significant, a staff comment asking for the assumptions in future filings is the realistic outcome. No figure in the statements changes.
Our workings
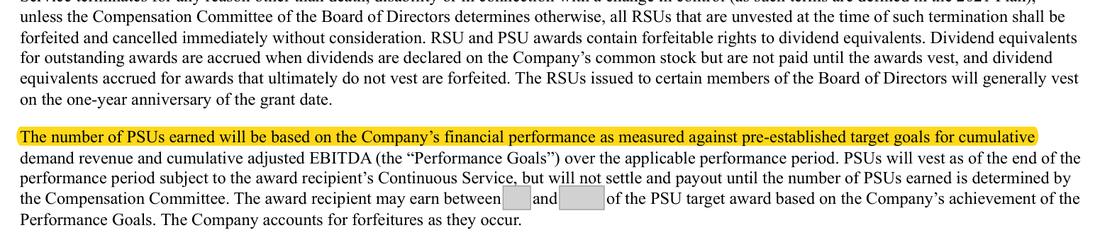
Note 8 says the [date] PSU grant added a relative TSR goal to the cumulative demand revenue and adjusted EBITDA goals, that the TSR portion is valued by a Monte Carlo model of the company's expected TSR ranking against a custom peer group, and that [n] PSUs were granted at a weighted grant-date fair value of [amount]. The policy note repeats the model name. Neither page, nor any other page of the 10-K, gives an input to the model.
[n] x [amount] = about [n] of grant-date value, [n] / [n] = 4.89% of pre-tax income; PSU expense for 2025 was [n].
| Item | Figure |
|---|---|
| PSUs granted in 2025 x weighted grant-date fair value | [n] x [n] = [n] dollars, about [n] |
| Grant value as % of pre-tax income | [n] / [n] = 4.89% |
| PSU expense recognized in 2025 | [n] |
| Monte Carlo assumptions disclosed (volatility, risk-free rate, term, dividend yield, peer group basis) | none |
Management’s best defense, and our reply
The TSR goal is one of three goals on a single PSU grant whose total grant-date value is about [n], under 5% of pre-tax income, and the PSU charge for 2025 was [n]. Materiality applies to disclosure as much as to measurement, and the company could fairly judge that the inputs to a small slice of one grant would leave every reader's view unchanged. The proxy statement filed in [date] also says the three PSU metrics are weighted approximately equally, so the relative-TSR slice is only about a third of that grant. Its auditor could also point out that the grant-date fair value per unit and the award activity are already disclosed, which is what a reader most needs.
The fix
- Add to Note 8 a short table for the relative-TSR PSUs granted in the year: grant-date fair value per unit, expected volatility (company and peer group), risk-free rate, performance period and dividend yield.
Question for the company
What grant-date fair value was assigned to the relative-TSR portion of the [date] PSU grant, what expected volatility (company and peer group), risk-free rate, performance period and dividend yield were used in the Monte Carlo valuation, and on what basis were those assumptions judged not significant enough to disclose?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The [date] PSU grant added a relative TSR goal | Document | Form 10-K 2025, page 76 |
| 2 | The TSR portion is valued with a Monte Carlo model | Document | Form 10-K 2025, page 76 |
| 3 | PSUs granted in 2025 and their weighted grant-date fair value | Document | Form 10-K 2025, page 76 |
| 4 | PSU expense recognized in 2025 | Document | Form 10-K 2025, page 76 |
| 5 | Pre-tax income used to size the grant | Document | Form 10-K 2025, page 78 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
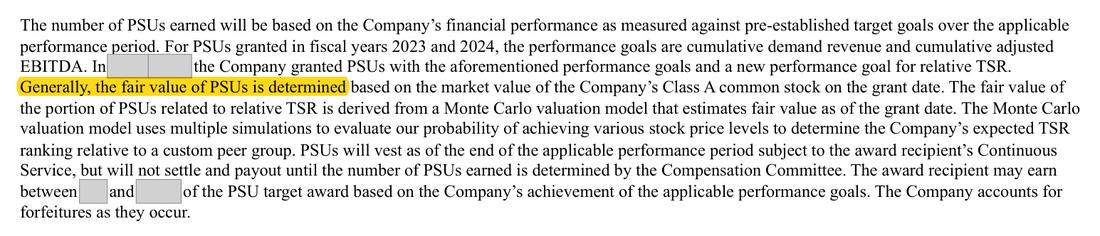
- Generally, the fair value of PSUs is determined
- What is missing
- the significant assumptions used in the Monte Carlo valuation of the relative-TSR portion of the 2025 PSU grant
- Pages looked at
- p.69-70 (policy), 78-80 (Note 8)
- Result
- 'Monte Carlo' hits only p.69 (policy) and p.76 (this paragraph), both naming the model without inputs; 'peer group' hits only p.76 (this paragraph); 'volatility' hits p.13, [n], all risk-factor or results narrative about market and demand volatility, not a valuation input; 'expected volatility', 'risk-free', 'expected term' and 'dividend yield' have no hits.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.