5.01 The explanation of how the headquarters lease discount rate was set, promised to the SEC staff in 2024 and given in the 2024 10-K, is no longer in the leases note
Company D · a US-listed cloud communications software company · SEC-style question
In brief
Answering a 2024 staff comment, the company said that from the 2024 Form 10-K it would state that the headquarters lease excludes its two renewal options and explain how the lease discount rate was determined. The 2024 10-K gave both, including the estimated rate of [n]%. The 2025 leases note keeps the renewal-option sentence for the [amount] lease liability but drops the discount-rate explanation; only the general policy that the company 'generally uses its incremental borrowing rate' remains.
The evidence, as filed
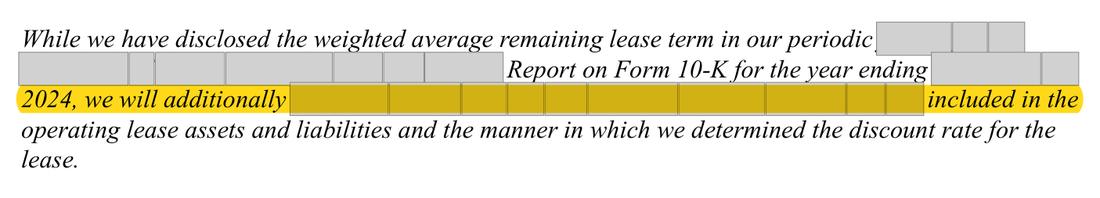
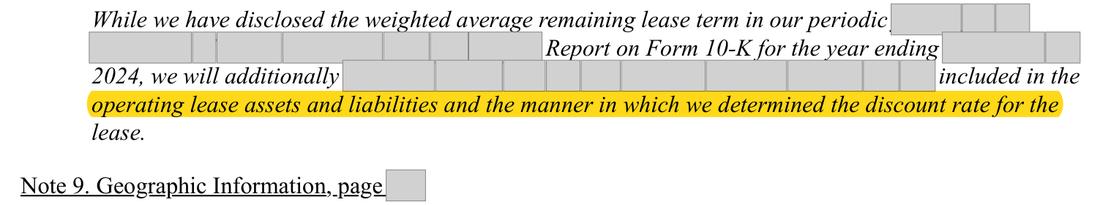
4 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Corporate Headquarters paragraph states that the [amount] lease liability excludes the two ten-year renewal options; the paragraph explaining the discount rate (stated yield rejected, incremental borrowing rate built up from a risk-free rate and a secured-credit premium, [n]%) given in the 2024 note is not repeated | Either the discount-rate explanation kept for as long as the headquarters lease is presented, as undertaken to the staff, or a decision that the undertaking was a one-time clarification, documented |
The rule
Exchange Act Rule 12b-20
In addition to the information expressly required to be included in a statement or report, there shall be added such further material information, if any, as may be necessary to make the required statements, in the light of the circumstances under which they are made not misleading.
Version: Text in force at the date of this review · Source: Exchange Act Rule 12b-20, 17 CFR 240.12b-20, as amended
Why it applies here. the general policy on p.94 states the company generally uses its incremental borrowing rate, which addresses the discount-rate determination at the level of all leases; the topic's disclosure of significant judgments lists the discount rate as an example rather than a mandate. Whether the 2024 undertaking was meant to continue is a question only management can answer.
Why it matters
A staff review comparing the two years would see an undertaking delivered once and then withdrawn without explanation, and could reopen the point.
Exposure
A question; at most a staff comment and a renewed undertaking, no penalty
Our workings
the company's letter to the staff of [date] says that, beginning with the Form 10-K for 2024, it would '[wording masked] excluded 'and the manner in which we determined the discount rate for the lease'. The 2024 10-K leases note carried both. The 2025 note carries the renewal-option sentence but goes straight from the lease description to the amounts recognized; the stated-yield and incremental-borrowing-rate explanation is not there.
none.
Management’s best defense, and our reply
The company would say the [date] response offered the extra wording 'for the avoidance of doubt', that it was delivered in the 2024 10-K as promised, and that the staff closed its review on that basis. It would add that the discount-rate policy on p.94 continues to state that the incremental borrowing rate is used, that the headquarters lease began in 2023 and its rate is settled history, and that the leases topic only lists the discount rate as a judgment that may be disclosed. That case is tenable, which is why the point is put as a question; the counter-point is that the response said 'beginning with', which reads as a continuing commitment, and the lease is by far the largest the company has.
The fix
- Restore after the Corporate Headquarters paragraph: 'The Company determined the stated yield in the lease was not calculated as required by ASC 842 and used its incremental borrowing rate, estimated at [n]% from a risk-free rate for a similar term plus a secured-credit risk premium.'
Question for the company
In [date] the company told the SEC staff that, beginning with the 2024 Form 10-K, it would explain how the discount rate for the headquarters lease was determined; the 2024 10-K did so and the 2025 10-K does not. Was the paragraph removed deliberately, and does the company regard the undertaking as continuing for as long as the headquarters lease is presented?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The undertaking to the staff, from the 2024 Form 10-K onward | Document | |
| 2 | The undertaking covers the discount-rate method | Document | |
| 3 | 2025 note keeps the renewal-option statement | Document | Form 10-K 2025, page 108 |
| 4 | General lease policy on the discount rate, the only discount-rate method statement in the 2025 report | Document | Form 10-K 2025, page 94 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Corporate Headquarters
- What is missing
- the explanation of how the headquarters lease discount rate was determined (stated yield rejected, incremental borrowing rate estimate and its result)
- Pages looked at
- p.93-94 (lease policy), p.107-108 (Leases note)
- Result
- 'incremental borrowing rate' and 'IBR' hit p.94 only: the general policy sentence that the company generally uses its incremental borrowing rate for all leases, not the headquarters determination; 'IBR' also hits p.16 inside an unrelated word. 'stated yield', '[n]', 'risk premium' and 'risk-free rate' have no hits.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.