4.02 The full-year 2025 earnings release headlines record Adjusted EBITDA and free cash flow without the GAAP measures, the pattern the SEC staff raised in 2024
Company D · a US-listed cloud communications software company · Compliance or disclosure gap
In brief
The release furnished on the day the 10-K was filed opens with 'Record fourth quarter Adjusted EBITDA and free cash flow' and an outlook of '[n]% Adjusted EBITDA growth'; neither the headline nor the chief financial officer's quote gives net loss or operating cash flow. The guidance paragraph drops the reconciliation of forward-looking Adjusted EBITDA and non-GAAP earnings per share without stating the probable significance of the item it cannot estimate. Item 10(e)(1)(i) applies to earnings releases through Instruction 2 to Item 2.02, and in [date] the staff commented on this same prominence point in the company's release.
The evidence, as filed
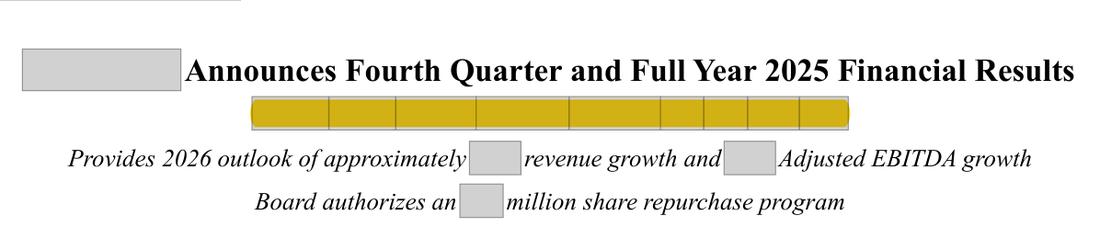
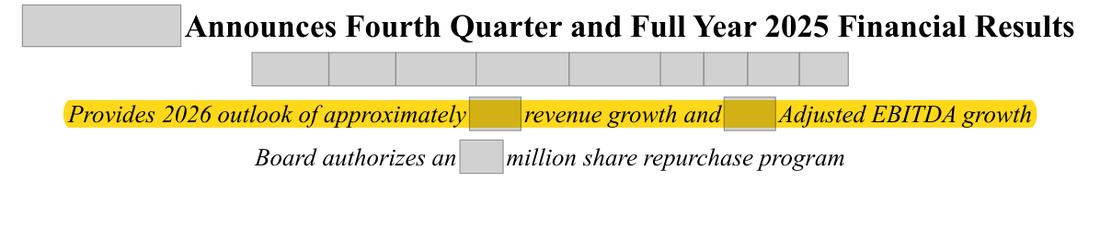
3 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Headline: 'Record fourth quarter Adjusted EBITDA and free cash flow' and '[n]% Adjusted EBITDA growth' outlook; quote: 'record quarterly results for Adjusted EBITDA'; no GAAP measure in either; forward-looking reconciliation not provided, with the reason (stock-based compensation) but not its probable significance | Each headline or quote that names a non-GAAP measure also gives the most directly comparable GAAP measure (net loss; net cash provided by operating activities) with equal or greater prominence; the guidance paragraph states reliance on the unreasonable-efforts exception, the unavailable item and its probable significance |
| What we checked. Release headline, quotes, highlights table, guidance paragraph and reconciliations; every full-year figure in the release statements and reconciliations was tied to the 10-K (no difference) | |
The rule
Form 8-K, Item 2.02, Instruction 2
The requirements of paragraph (e)(1)(i) of Item 10 of Regulation S-K (17 CFR 229.10(e)(1)(i)) shall apply to disclosures under this Item 2.02.
Version: Text in force at the date of this review · Source: Form 8-K General Instructions and Items, as amended
Regulation S-K Item 10(e)(1)(i)(A) and (B)
A presentation, with equal or greater prominence, of the most directly comparable financial measure or measures calculated and presented in accordance with Generally Accepted Accounting Principles (GAAP);
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.10(e), as amended
SEC Division of Corporation Finance, Non-GAAP Financial Measures C&DI Question [n](a)
Presenting a non-GAAP measure before the most directly comparable GAAP measure or omitting the comparable GAAP measure altogether, including in an earnings release headline or caption that includes a non-GAAP measure.
Version: Text in force at the date of this review · Source: SEC Compliance and Disclosure Interpretations, Non-GAAP Financial Measures, updated [date]
SEC Division of Corporation Finance, Non-GAAP Financial Measures C&DI Question [n](a), fifth example
Describing a non-GAAP measure as, for example, “record performance” or “exceptional” without at least an equally prominent descriptive characterization of the comparable GAAP measure.
Version: Text in force at the date of this review · Source: SEC Compliance and Disclosure Interpretations, Non-GAAP Financial Measures, updated [date]
SEC Division of Corporation Finance, Non-GAAP Financial Measures C&DI Question [n](b)
A measure would be considered more prominent than the comparable GAAP measure if it is presented without disclosing reliance upon the exception, identifying the information that is unavailable, and its probable significance in a location of equal or greater prominence.
Version: Text in force at the date of this review · Source: SEC Compliance and Disclosure Interpretations, Non-GAAP Financial Measures, updated [date]
Why it applies here. Instruction 2 to Item 2.02 of Form 8-K applies Item 10(e)(1)(i) of Regulation S-K, including the equal-or-greater-prominence condition, to a furnished earnings release. The staff interpretation lists, as examples of undue prominence, a headline that includes a non-GAAP measure without the comparable GAAP measure, and describing a non-GAAP measure as 'record' without an equally prominent characterization of the GAAP measure; both are present. Its companion interpretation treats a forward-looking non-GAAP measure as more prominent when the unavailable information is not identified with its probable significance. The 2024 undertaking covered the highlights table only; the headline and quote fall outside it and repeat the point the staff raised.
Why it matters
A staff comment on the next release or periodic report, with a further undertaking; repeated after a closed comment on the same point, it weakens the company's record with the staff.
Exposure
Staff comment letter and future-releases undertaking; no fixed penalty
Our workings
the release (Exhibit 99.[n] to the Form 8-K of [date]) carries two sub-headlines, 'Record fourth quarter Adjusted EBITDA and free cash flow' and 'Provides 2026 outlook of approximately [n]% revenue growth and [n]% Adjusted EBITDA growth'. The chief financial officer's quote describes 'record quarterly results for Adjusted EBITDA and free cash flow'. The highlights table below them does present net loss and net cash provided by operating activities, which is what the company undertook to the staff in [date]. The guidance paragraph says the forward-looking Adjusted EBITDA and non-GAAP earnings per share are not reconciled 'because stock-based compensation cannot be reasonably calculated or predicted at this time'.
none; every full-year figure in the release agrees with the 10-K.
| Staff example of undue prominence | Where it appears in the release | Comparable GAAP measure given alongside? |
|---|---|---|
| Non-GAAP measure in a headline without the GAAP measure | Sub-headlines 1 and 2 (Adjusted EBITDA, free cash flow, Adjusted EBITDA growth outlook) | No |
| Non-GAAP measure described as 'record' | Sub-headline 1 and the chief financial officer's quote | No |
| Forward-looking non-GAAP without the probable significance of the unavailable item | Guidance paragraph | Reason given, significance not given |
| Highlights table (the 2024 undertaking) | Page 1 of the release | Yes: net loss and operating cash flow shown |
Management’s best defense, and our reply
The company would say the release is furnished, not filed, that the headline uses no figures for the non-GAAP measures, and that the highlights table directly beneath presents net loss and operating cash flow exactly as it undertook to the staff in [date], which the staff accepted when it closed the review. It would add that the forward-looking exception is claimed with its reason, stock-based compensation, which is how most issuers word it. The answer: Instruction 2 to Item 2.02 makes the prominence condition apply to furnished releases, the staff's published examples name both a headline that includes a non-GAAP measure without the GAAP measure and a 'record' description of a non-GAAP measure, and the undertaking about the table does not cure the headline and quote; the probable-significance element of the forward-looking exception is not stated.
The fix
- Lead the headline with GAAP results (for example 'Revenue of [amount]; net loss of [amount]; net cash from operations of [amount]') before any Adjusted EBITDA or free cash flow, characterize the GAAP measures with equal prominence in quotes, and add to the guidance paragraph: 'stock-based compensation, which we expect to be significant, is the principal reconciling item that cannot be estimated'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Sub-headline names two non-GAAP measures as records with no GAAP measure | Document | |
| 2 | Sub-headline gives a forward-looking non-GAAP growth rate | Document | |
| 3 | The chief financial officer's quote characterizes the non-GAAP measures as records; no GAAP measure is characterized | Document | |
| 4 | Forward-looking reconciliation not provided; exception claimed | Document | |
| 5 | The unavailable item is named, its probable significance is not | Document | |
| 6 | The staff raised the prominence of Adjusted EBITDA and free cash flow in the company's 2024 release | Document | |
| 7 | The company's undertaking covered the highlights table | Document | |
| 8 | Later release (second quarter 2026) keeps the pattern: a record non-GAAP margin in the headline with no GAAP margin | Document |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.