1.04 Interest income is netted into 'Interest expense, net' and 'Other (expense) income, net' is never analyzed, so neither interest income nor the foreign exchange result appears in the statements
Company D · a US-listed cloud communications software company · Compliance or disclosure gap
In brief
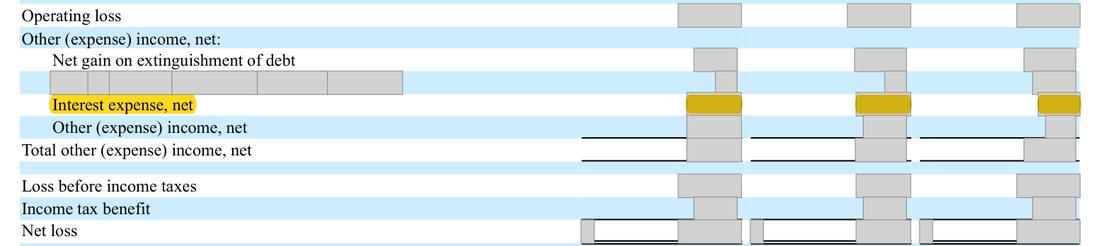
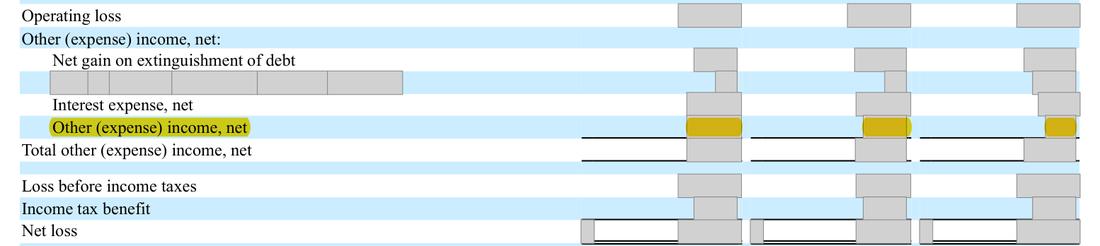
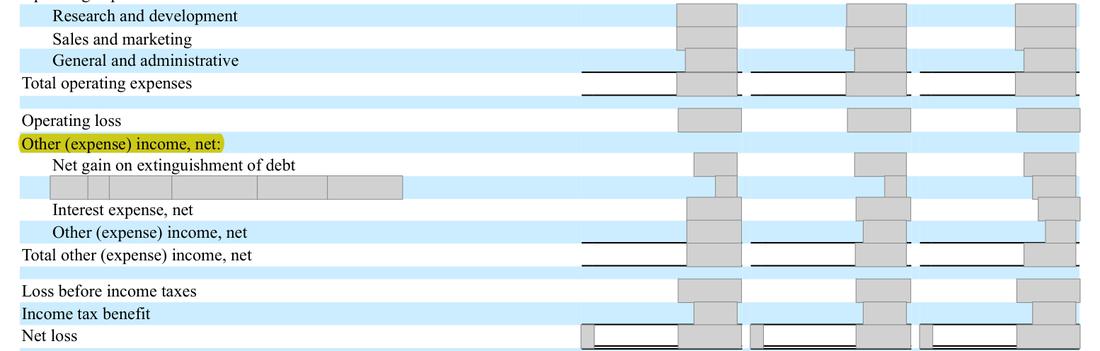
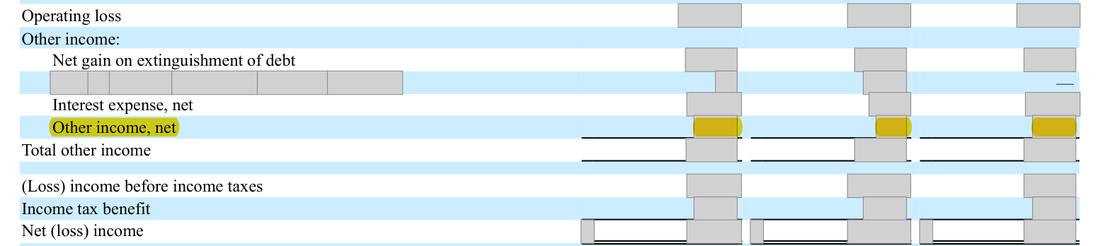
The statements of operations show 'Interest expense, net' of [amount] and 'Other (expense) income, net' of [amount] for 2025 ([amount] income for 2024). Interest on the convertible notes alone was [amount], so at least [amount] of interest income has been netted into the interest line, and the notes give interest income only for marketable securities ([amount]). Neither line is analyzed in the notes; the 2025 foreign exchange loss of [amount] appears only in a non-GAAP footnote in MD&A, and the 2024 income of [amount] is not explained anywhere.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
'Interest expense, net' ([n]) / ([n]) / ([n]) and 'Other (expense) income, net' ([n]) / [n] / [n], with no note analyzing either; interest income stated only for marketable securities ([amount]); foreign exchange result stated only in a non-GAAP footnote for 2025 ([amount]). | Interest income on cash, cash equivalents and securities stated separately from interest expense, and the material components of other (expense) income (foreign exchange transaction and remeasurement gains and losses, other items), including the aggregate foreign exchange transaction result, stated in the statements or a note for each of the three years. |
The rule
Regulation S-X Rule 5-03, caption 7 (Non-operating income)
Non-operating income. State separately in the statement of comprehensive income or in a note thereto amounts earned from (a) dividends, (b) interest on securities, (c) profits on securities (net of losses), and (d) miscellaneous other income. ... Material amounts included under miscellaneous other income shall be separately stated in the statement of comprehensive income or in a note thereto, indicating clearly the nature of the transactions out of which the items arose.
Version: Text in force at the date of this review · Source: Regulation S-X, 17 CFR 210.5-03 (eCFR, as amended)
Regulation S-X Rule 5-03, caption 9 (Non-operating expenses)
Material amounts included under miscellaneous income deductions shall be separately stated in the statement of comprehensive income or in a note thereto, indicating clearly the nature of the transactions out of which the items arose.
Version: Text in force at the date of this review · Source: Regulation S-X, 17 CFR 210.5-03 (eCFR, as amended)
Why it applies here. Regulation S-X asks for interest on securities and material items of miscellaneous non-operating income and deductions to be stated separately with their nature, in the statement or a note, and the foreign currency standard asks for the aggregate transaction gain or loss of each period in the financial statements or notes. Against a loss before income taxes of [n] these items are not small, and none of the amounts is in the statements or notes.
Why it matters
Readers cannot see how much the Company earns on its [amount] of cash or how much currency movements cost it, and the policy note and MD&A describe interest income in two different places; the realistic outcome is a staff comment and expanded disclosure.
Exposure
Staff comment letter and a future-filings undertaking; no restatement.
Our workings
the statements of operations present 'Interest expense, net' and 'Other (expense) income, net' for three years within the section headed other (expense) income, net. Note 7 gives total interest expense on the convertible notes of [n] for 2025. MD&A describes the interest line as interest expense net of interest income. The policy on marketable securities says their interest income is reported within other (expense) income, net, and Note 2 gives that interest as [amount] for 2025; no figure is given for interest on cash and cash equivalents. The foreign currency policy says transaction and remeasurement gains and losses are in other (expense) income, net, but no amount is given in the financial statements; MD&A's non-GAAP footnote mentions [amount] of foreign exchange charges for 2025 only.
[n] - [n] = [n], the least interest income netted into the interest line; the other (expense) income line swung by [n] + [n] = [n] between 2024 and 2025 and was [n] / [n] = 7.7% of the 2025 loss before income taxes and [n] / [n] = 30.2% of the 2024 loss.
| Test | 2025 | 2024 |
|---|---|---|
| Interest expense on convertible notes (Note 7) | [n] | [n] |
| 'Interest expense, net' (statement of operations) | [n] | [n] |
| Least interest income netted into the interest line | [n] - [n] = [n] | [n] - [n] = [n] |
| 'Other (expense) income, net' | ([n]) | [n] |
| Swing in other (expense) income | [n] + [n] = [n] | |
| Other (expense) income as % of loss before income taxes | [n] / [n] = 7.7% | [n] / [n] = 30.2% |
| Composition given in the financial statements | interest on marketable securities [amount] only | [amount] only |
Management’s best defense, and our reply
Management would say the amounts are small against revenue of [amount], that interest income on marketable securities is disclosed in Note 2, and that the 2025 foreign exchange charge is quantified in MD&A. They might also say presenting interest net is common for a company that is a net borrower, and that the policy places interest income in the other (expense) income section, where the net interest line sits. However, the S-X captions and the foreign currency standard call for the amounts in the financial statements or notes, not in a non-GAAP footnote; the items are large against a loss before income taxes of [n]; and the 2024 income of [n] (30.2% of that year's loss before tax) is explained nowhere.
The fix
- Show 'Interest income' and 'Interest expense' as separate lines (or analyze 'Interest expense, net' in a note), and add a note: 'Other (expense) income, net consists of: foreign currency transaction and remeasurement gains (losses) $X; other $Y', for each year.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Interest is presented net on the face for all three years | Document | Form 10-K 2025, page 85 |
| 2 | The other (expense) income line, unanalysed: a loss of [n] in 2025 after income of [n] in 2024 | Document | Form 10-K 2025, page 85 |
| 3 | Loss before income taxes, the base for the size test | Document | Form 10-K 2025, page 85 |
| 4 | Interest on the convertible notes alone exceeds the net interest line | Document | Form 10-K 2025, page 112 |
| 5 | MD&A confirms interest income is netted into the interest line | Document | Form 10-K 2025, page 67 |
| 6 | The policy places interest income in other (expense) income instead | Document | Form 10-K 2025, page 93 |
| 7 | The only interest income figure given: marketable securities only | Document | Form 10-K 2025, page 103 |
| 8 | Foreign exchange remeasurement gains and losses sit in other (expense) income, with no amount | Document | Form 10-K 2025, page 98 |
| 9 | The 2025 foreign exchange loss appears only in a non-GAAP footnote in MD&A | Document | Form 10-K 2025, page 74 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Other (expense) income, net:
- What is missing
- interest income stated separately from interest expense, and the components (foreign exchange result and other items) of other (expense) income, net, for each year
- Pages looked at
- p.85, [n] (images); whole 10-K text
- Result
- 'currency loss' does not occur. 'interest income' hits p.67 (MD&A: interest line is net of interest income, no amount), [n] (Item 7A: fluctuations not significant, no amount) and [n] (policy). 'transaction gains' hits p.98 (policy only). 'foreign exchange' hits p.47 (risk factor), [n] and [n] (non-GAAP footnote: [amount] for 2025 only, outside the financial statements) and [n] (policy). 'other (expense) income' hits p.65 (MD&A table), [n] (Item 7A), 87 (the statement), [n] (policies), [n] (interest on marketable securities, [amount]) and [n] (segment note, no amounts); none analyses the line for any year.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.