1.02 Interest paid is reported net of interest received, so the cash-flow supplement does not give the interest the Company actually paid
Company D · a US-listed cloud communications software company · Compliance or disclosure gap
In brief
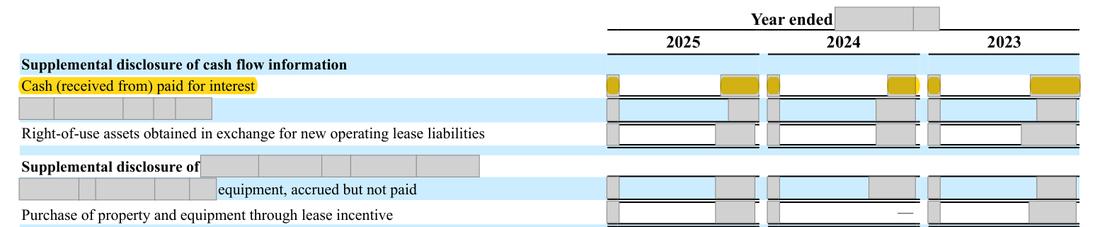
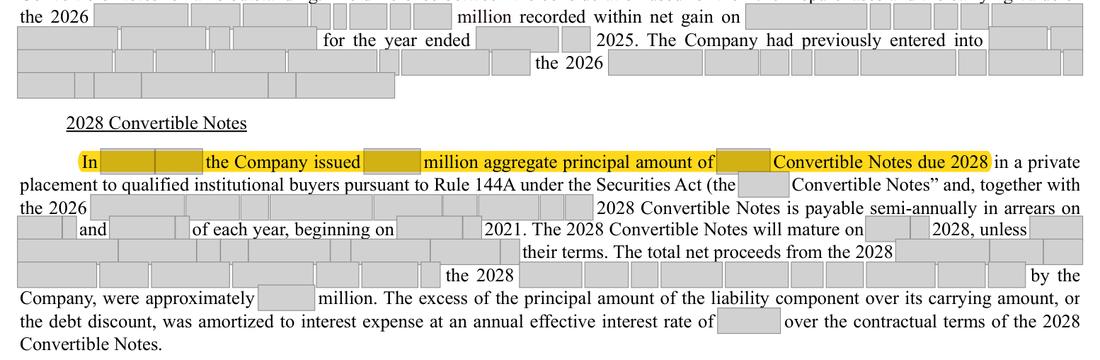
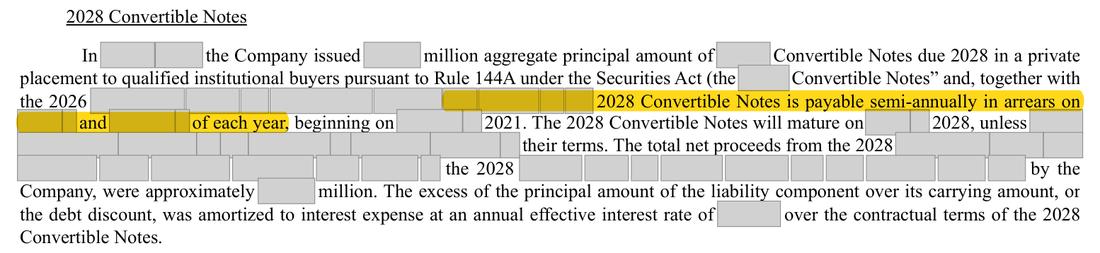
The supplemental cash-flow line reads 'Cash (received from) paid for interest' and shows a net receipt of [amount] for 2025 and [amount] for 2023. The Company cannot have paid less than nothing: the coupon on the [amount] [n]% notes due 2028 alone is [amount] a year, payable each April and October. The line therefore nets interest received against interest paid, which the cash-flow standard does not allow for this disclosure.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
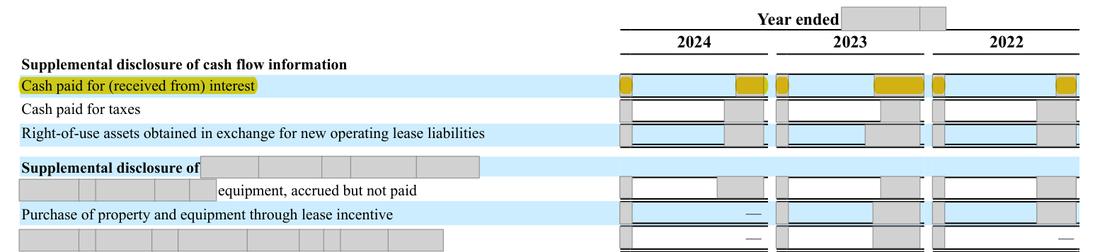
Supplemental line 'Cash (received from) paid for interest': ([n]) for 2025, [n] for 2024, ([n]) for 2023 (the 2025 10-K); the 2024 10-K labelled the same line 'Cash paid for (received from) interest'. | The amount of interest paid (net of amounts capitalized), at least the [n] contractual coupon on the 2028 notes for each year, with interest received not offset against it. |
The rule
FASB ASC 230-10-45-10 to 45-17; 230-10-50-2 (interest paid, net of amounts capitalized)
Summary; FASB/IFRS text is copyrighted Classify cash receipts and payments as operating, investing or financing by their nature, present gross flows, include restricted cash, and disclose significant noncash activities.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 230 (as amended by ASU 2016-15 and ASU 2016-18), paraphrased
Regulation S-X Rule 4-01(a)(1)
Financial statements filed with the Commission which are not prepared in accordance with generally accepted accounting principles will be presumed to be misleading or inaccurate, despite footnote or other disclosures, unless the Commission has otherwise provided.
Version: Text in force at the date of this review · Source: Regulation S-X, 17 CFR 210.4-01 (eCFR, as amended)
Why it applies here. the line is a net figure of interest paid less interest received (the label itself says 'received from'). The cash-flow standard asks for the amount of interest paid, net only of interest capitalized; interest received is an operating inflow in its own right and is not an offset to this disclosure. The figure for every year presented is therefore not the required amount, and for 2025 and 2023 it shows the wrong sign.
Why it matters
A reader cannot see the cash cost of the Company's debt from the statements; the line understates interest paid by at least [n] in 2025 and [n] in 2023 and reverses its sign. A staff comment asking for the gross figure in future filings is the realistic outcome.
Exposure
Staff comment letter and a future-filings undertaking; no restatement expected because the error sits in a supplemental disclosure and is small.
Our workings
the supplemental disclosure on the cash-flow statement shows a net receipt of [n] for 2025 and [n] for 2023 and a payment of [n] for 2024 (thousands). Note 7 says interest on the 2028 convertible notes ([amount], [n]%) is payable semi-annually on [date] and [date], and records contractual interest expense on those notes of [n] (2025), [n] (2024) and [n] (2023). The 2026 notes also carried a cash coupon.
the 2028 coupon alone is [n] x [n]% = [n] a year in cash; the gap between that minimum and the reported figure for 2025 is [n] + [n] = [n], which is the least amount of interest received that has been netted into the line.
| Item | 2025 | Basis |
|---|---|---|
| Reported 'Cash (received from) paid for interest' | ([n]) | cash-flow statement, supplemental |
| Minimum cash coupon on the 2028 notes | [n] x [n]% = [n] | note 7: [n]% notes, interest payable [date] and [date] |
| Contractual interest expense on the 2028 notes (cross-check) | [n] | note 7 table |
| Least interest received netted into the line | [n] + [n] = [n] | minimum paid less reported net |
| Difference: reported less minimum interest paid | -182 - [n] = -[n] | thousands |
| Share of loss before income taxes | [n] / [n] = 8.6% | statement of operations |
| 2024: reported 'Cash (received from) paid for interest' | [n] | cash-flow statement, supplemental (2024 column) |
| 2024: understatement against the minimum coupon | [n] - [n] = -559 | reported less correct; [n] understated |
| 2024: share of loss before income taxes | [n] / [n] = 6.2% | statement of operations |
| Item | 2023 |
|---|---|
| Reported 'Cash paid for (received from) interest' | ([n]) |
| Contractual interest expense on the 2028 notes | [n] |
| Least interest received netted into the line | [n] + [n] = [n] |
Management’s best defense, and our reply
Management would say the label 'Cash (received from) paid for interest' tells the reader plainly that the figure is net, so nobody is misled, and that the amounts are small against operating cash flow of [amount]. They might add that interest received on cash balances is economically linked to the cost of the convertible notes. However, the standard asks for one specific figure, interest paid, net only of interest capitalized; an honest label does not turn a net figure into the required one, and here the netting changes the sign of the disclosure in two of the three years. The size argument goes to severity, which is why this is graded low, not to whether the figure is the one required.
The fix
- Present 'Cash paid for interest' as the gross amount paid (for 2025 at least the [n] coupon on the 2028 notes plus the [n]-note coupon and facility fees) and, if wished, show interest received on a separate line.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The supplemental line nets interest received: a net receipt of [n] (2025) and [n] (2023) | Document | Form 10-K 2025, page 89 |
| 2 | The 2028 notes carry a [n]% cash coupon on [amount] | Document | Form 10-K 2025, page 110 |
| 3 | The coupon falls due twice within every calendar year | Document | Form 10-K 2025, page 110 |
| 4 | Contractual interest on the 2028 notes is [n] / [n] / [n] for 2025 / 2024 / 2023 | Document | Form 10-K 2025, page 112 |
| 5 | The 2024 10-K presented the same net figure (2023: net receipt of [n]) | Document | Form 10-K 2024 (prior year), page 93 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.