1.06 The 2025 restructuring charge is disclosed without the required reconciliation of the restructuring liability
Company C · a US-listed specialty healthcare products company · SEC-style question
In brief
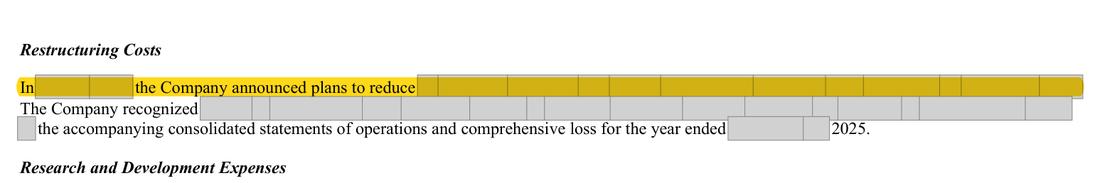
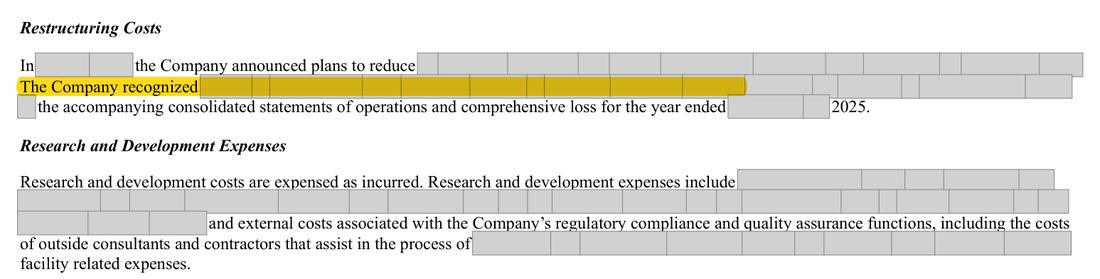
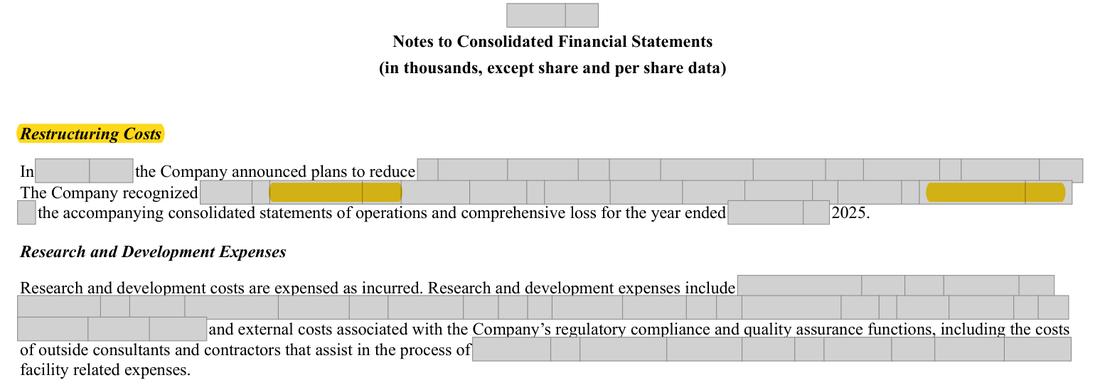
In [date] the company announced a plan to cut operating expenses, completed it by [date] and charged [amount] of restructuring costs, mainly one-time severance. The note gives the description, timing, amount and income-statement line, but no reconciliation of the restructuring liability (opening balance, charges, amounts settled, closing balance) and no statement of what, if anything, was still owed at [date]. The charge is 2.8% of the pre-tax loss, so the point is small, but the reconciliation is a specific requirement for the year a plan starts.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Restructuring costs of [amount] described (plan, timing, severance, income-statement line). No liability reconciliation and no year-end liability figure anywhere in the report. | A short reconciliation (or one sentence) showing costs charged of [amount], amounts settled in the year and the liability at [date], even if nil. |
| What we checked. Restructuring policy paragraph, statement of operations, management's discussion, segment note, accrued expenses note, whole-report search, later quarterly reports | |
The rule
ASC 420-10-50-1 (exit or disposal cost obligations: disclosure)
Summary; FASB/IFRS text is copyrighted For exit or disposal activities, disclose description, expected completion, total, period and cumulative costs by major type and segment, and a liability rollforward.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 420-10-50-1 (as in force for fiscal 2025); summary wording of the study's US GAAP law pack
Why it applies here. for an exit or disposal activity, the Codification requires, in the period the activity starts and until it is complete, the total cost expected and incurred by major type and a reconciliation of the beginning and ending liability. Because the plan was completed within the year, the reconciliation may well end at nil, which is why the point is put as a question rather than a finding.
Why it matters
Readers cannot see whether any severance remained unpaid at the year end or confirm that the plan is fully settled. The realistic result is a staff comment asking for the reconciliation, or a one-line confirmation in the next Form 10-K.
Exposure
A question for management; the amounts charged are not in question.
Our workings
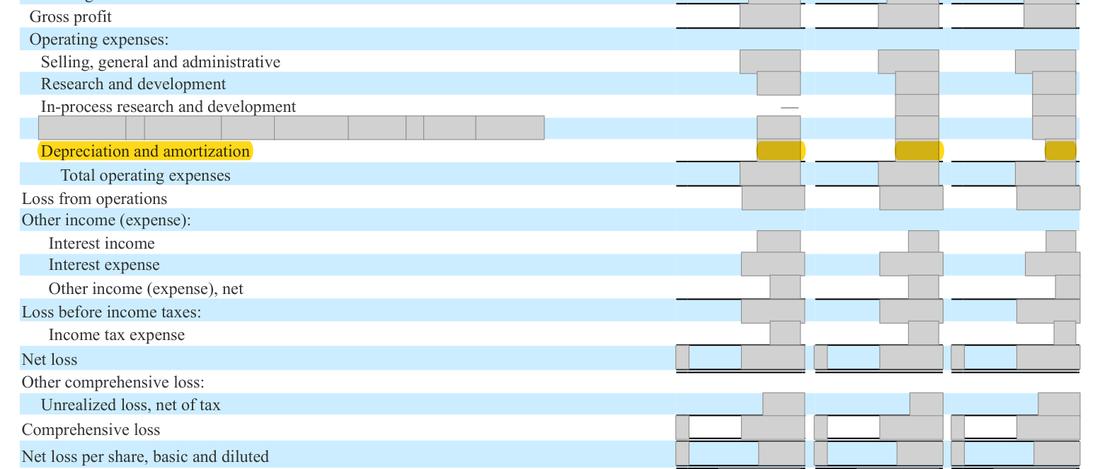
the note states that the plan was announced in [date], completed by [date] and gave rise to [amount] of restructuring costs, mainly one-time severance benefits, shown on the statement of operations line 'Restructuring costs'. Management's discussion repeats the charge (rounded to millions) and its cause; the segment note includes the charge in other segment items. Nothing in the report states the liability recognized, the amounts settled or any balance outstanding at the year end; the accrued expenses note has no restructuring line.
the charge is 2.8% of the pre-tax loss of [amount].
| Item | Computation | Source |
|---|---|---|
| Restructuring costs, 2025 | [n] | Note 2 and statement of operations |
| Share of pre-tax loss | [n] / [n] = 2.8% | computed |
Management’s best defense, and our reply
The finance team may say the charge is small (under 3% of the pre-tax loss and about half a percent of revenue), the plan began and finished within one quarter, and the severance was settled before the year end, so a reconciliation from nil to nil would add nothing; materiality allows an immaterial disclosure to be left out. They may add that management's discussion and the segment note already explain the charge. However, the year-end balance is not stated anywhere, so a reader cannot confirm that nothing remained owing, and the Codification asks for the reconciliation in the period the activity starts. A single sentence would meet the requirement, which is why the point is a low-severity question.
The fix
- Add: 'Restructuring costs of [amount] were charged in 2025; $[x] was settled in cash during the year and $[y] remained accrued at [date].' (or 'no liability remained').
Question for the company
How much of the [amount] restructuring charge was settled during 2025 and what liability, if any, remained at [date]? Was the reconciliation left out on materiality grounds?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Plan announced [date] and completed by [date] | Document | Form 10-K 2025, page 76 |
| 2 | Charge of [amount], mainly one-time severance | Document | Form 10-K 2025, page 76 |
| 3 | Pre-tax loss of [amount] for 2025, the materiality benchmark | Document | Form 10-K 2025, page 49 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Restructuring Costs
- What is missing
- the reconciliation of the restructuring liability (charges, amounts settled, balance at [date]) or a statement that no liability remained
- Pages looked at
- p.49, [n]
- Result
- 'restructuring liabilit' and 'restructuring accrual' have no hits. 'severance' hits only p.76 (this paragraph). 'separation benefits' hits only p.51 (management's discussion: amount and cause). 'restructur' also hits p.12 and [n] (risk factors on curtailment or restructuring of operations), p.49 and [n] (management's discussion: the [amount] charge), p.63 (statement of operations line) and p.95 (segment note: the charge sits in other segment items). None gives the liability, the amounts settled or the year-end balance.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.