7.02 Drafting slips in the income tax and segment notes
Company B · a US-listed transportation and logistics company · Drafting slip
In brief
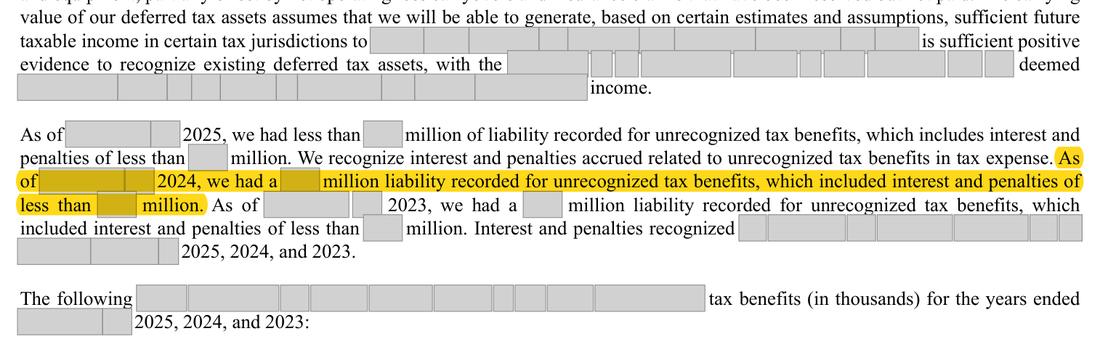
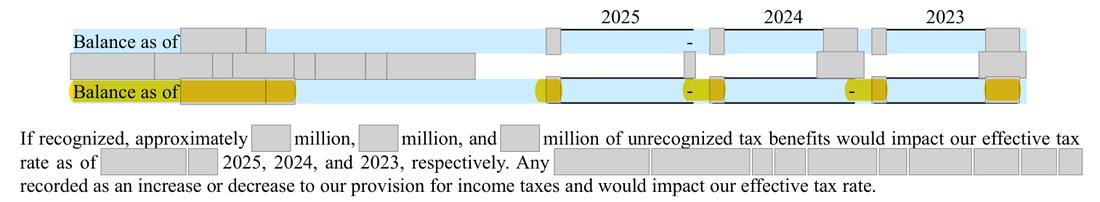
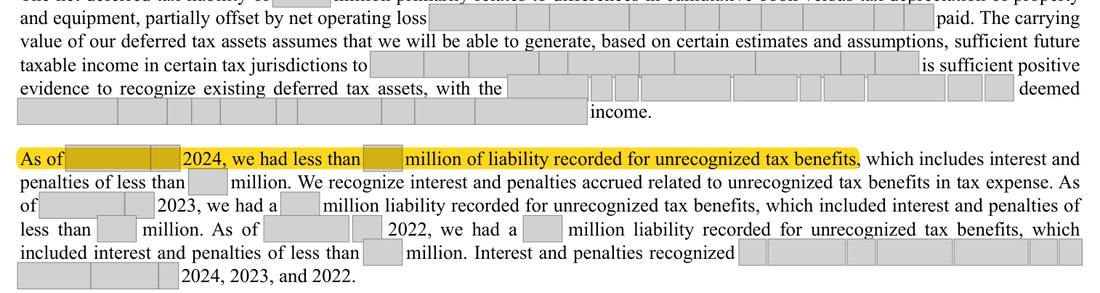
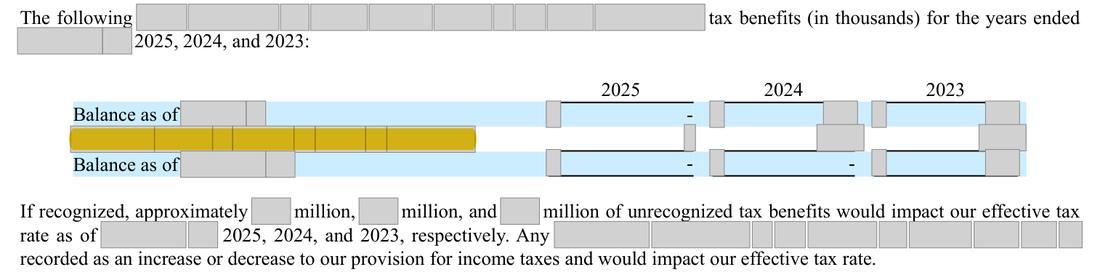
Four slips: the 2024 liability for unrecognized tax benefits is described as '[amount]' although the roll-forward shows nil and the 2024 report said 'less than [amount]'; 'statue of limitations' should read 'statute of limitations'; 'de minimus' should read 'de minimis'; and the segment row headed 'Gain on disposition of property and equipment, net' carries losses ([n] and [n] in 2025), where the income statement uses 'Loss (gain) on disposition'.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Note 12: '[amount] liability' at the end of 2024 against a nil roll-forward balance; 'statue of limitations'; 'de minimus'. Note 17: a 'Gain' row showing [n] and [n] that are losses. | 'less than [amount]' (as in the 2024 report); 'statute of limitations'; 'de minimis'; the segment row headed 'Loss (gain) on disposition of property and equipment, net', as on the income statement. |
Why it matters
None beyond the reader's confidence in the note.
Exposure
Drafting only.
Our workings
These are wording slips that change no audited figure. The 2024 sentence contradicts both the roll-forward on the same page and the 2024 report's own sentence; the segment label contradicts the sign of the amounts under it and the income statement caption.
Management’s best defense, and our reply
Management would say these are small wording errors that no reader would rely on, and that the roll-forward table, not the sentence, is the authoritative figure. They would also say the segment row is understood from its signs. However, the sentence and the label each contradict a figure printed beside them, and correcting them costs nothing.
The fix
- Correct the four items in the fiscal 2026 Form 10-K.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | 2024 liability described as [amount] | Document | Form 10-K 2025, unnumbered page |
| 2 | the roll-forward shows nil at the end of 2024 | Document | Form 10-K 2025, unnumbered page |
| 3 | the 2024 report's own wording | Document | Form 10-K 2024 (prior year), unnumbered page |
| 4 | 'statue' for 'statute' | Document | Form 10-K 2025, unnumbered page |
| 5 | 'de minimus' for 'de minimis' | Document | Form 10-K 2025, unnumbered page |
| 6 | a 'Gain' row carrying losses | Document | Form 10-K 2025, unnumbered page |
| 7 | the income statement caption | Document | Form 10-K 2025, page 55 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.