6.03 Exhibit 21 and the consolidation note name different subsidiaries: [subsidiary] in the note only, the Company Logistics Holdings, Inc. in the exhibit only
Company B · a US-listed transportation and logistics company · SEC-style question
In brief
Note 1 to the financial statements says the consolidated statements include [subsidiary], a [state] corporation, as a wholly owned subsidiary; Exhibit 21 does not list that company. Exhibit 21 lists the Company Logistics Holdings, Inc., a [state] corporation, which the note does not name. Both companies appear as parties to the [date] amendment of the credit agreement listed in the exhibit index, so both seem to exist. The prior-year 10-K shows the same difference.
The evidence, as filed
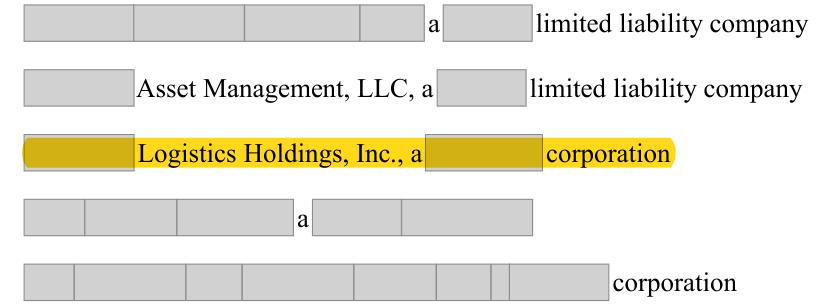
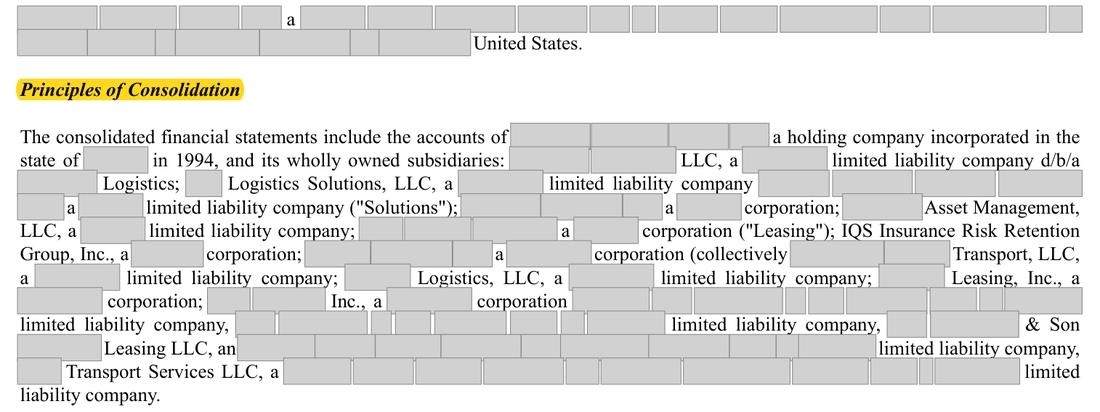
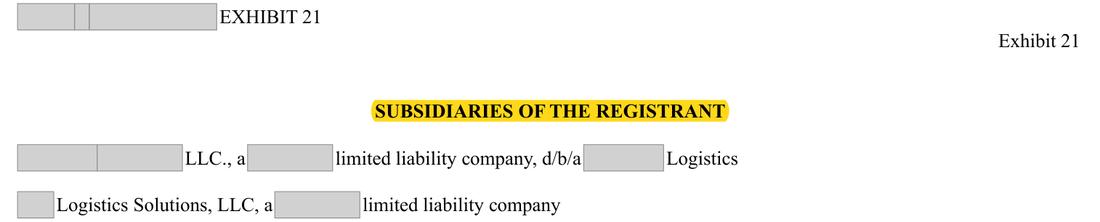
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Note 1 (Principles of Consolidation): wholly owned subsidiaries include '[subsidiary], a [state] corporation'; the Company Logistics Holdings, Inc. not named. Exhibit 21: lists 'the Company Logistics Holdings, Inc., a [state] corporation'; [subsidiary] not listed. The [numbered] Amendment to the credit agreement ([date]) in the exhibit index names both as parties. Same position in the fiscal 2024 10-K and its Exhibit 21. | Exhibit 21 lists every subsidiary, or omits only subsidiaries that together are not a significant subsidiary; and the consolidation note and Exhibit 21 describe the same group, or the difference is explained (for example a merger, a renaming or a dormant entity). |
The rule
Regulation S-K Item 601(b)(21)(i)
List all subsidiaries of the registrant, the state or other jurisdiction of incorporation or organization of each, and the names under which such subsidiaries do business
Version: Text in force at the date of this review · Source: 17 CFR 229.601(b)(21)(i) (eCFR)
Regulation S-K Item 601(b)(21)(ii)
The names of particular subsidiaries may be omitted if the unnamed subsidiaries, considered in the aggregate as a single subsidiary, would not constitute a significant subsidiary as of the end of the year covered by this report
Version: Text in force at the date of this review · Source: 17 CFR 229.601(b)(21)(ii) (eCFR)
Why it applies here. either [subsidiary] is a subsidiary that Exhibit 21 leaves out, or it no longer exists (merged or renamed) and the note carries a stale name, in which case the note also leaves out the Company Logistics Holdings, Inc. Item 601(b)(21)(ii) allows particular subsidiaries to be left out of Exhibit 21 when, taken together, they would not be a significant subsidiary, so the omission may be permitted; the documents do not say which reading is right. No computation is involved.
Why it matters
Readers, lenders and regulators who use Exhibit 21 as the list of group companies get a list that does not match the companies the financial statements say are consolidated; if [subsidiary] is a borrower or guarantor under the credit facility, its absence from Exhibit 21 understates the group the lenders rely on.
Exposure
No penalty; if the omitted entity is significant the staff would ask for a corrected Exhibit 21 in the next 10-K.
Our workings
the consolidation note lists the wholly owned subsidiaries by name and state, including [subsidiary] ([state]). Exhibit 21 lists the subsidiaries by name and state, including the Company Logistics Holdings, Inc. ([state]), and does not list [subsidiary] The credit-agreement amendment of [date] in the exhibit index names both companies as parties. The fiscal 2024 10-K has the same note wording and the same Exhibit 21 list for these two entities.
Management’s best defense, and our reply
Management could say that Item 601(b)(21)(ii) expressly allows particular subsidiaries to be left out of Exhibit 21 when together they would not be a significant subsidiary, and that [subsidiary] may be a small or dormant entity kept for contracts. It could add that the consolidation note is not required to list every subsidiary at all, so naming one entity there and another in Exhibit 21 breaches no rule. That defense is tenable, and nothing in the filings shows the size of either entity; the point is therefore a question. However, the two lists are presented as complete lists of the same group and disagree in both directions, and one entity is a party to the credit agreement, so the company should confirm which list is right.
The fix
- Confirm the current legal entity list. If [subsidiary] exists, add it to Exhibit 21 (or document that the unnamed subsidiaries together are below the significant-subsidiary tests); if it was merged or renamed, correct the consolidation note and name the Company Logistics Holdings, Inc. there.
Question for the company
Is [subsidiary] ([state]), named in Note 1 as a consolidated wholly owned subsidiary and a party to the [date] credit-agreement amendment, still a subsidiary at [date]? If so, why is it not in Exhibit 21, and was its omission assessed under the significant-subsidiary test? If not, should the note name the Company Logistics Holdings, Inc. instead?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The consolidation note names [subsidiary] as a wholly owned subsidiary | Document | Form 10-K 2025, unnumbered page |
| 2 | Exhibit 21 lists the Company Logistics Holdings, Inc. | Document | |
| 3 | [subsidiary] is a party to the credit-agreement amendments in the exhibit index (the [date] amendment shown here; the [date] amendment names it in the same list) | Document | Form 10-K 2025, unnumbered page |
| 4 | The Company Logistics Holdings, Inc. is a party to the same amendment | Document | Form 10-K 2025, unnumbered page |
| 5 | The prior-year consolidation note names [subsidiary] as a wholly owned subsidiary | Document | Form 10-K 2024 (prior year), unnumbered page |
| 6 | The prior-year Exhibit 21 lists the Company Logistics Holdings, Inc., which the note does not name | Document | |
| 7 | Both companies are parties to the [date] credit agreement amendment listed in the prior-year exhibit index | Document | Form 10-K 2024 (prior year), unnumbered page |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Principles of Consolidation
- What is missing
- The Company Logistics Holdings, Inc., a [state] corporation
- Pages looked at
- p.3, [n], 58-100
- Result
- 'the Company Logistics Holdings' and 'Logistics Holdings' hit only unnumbered page (party list of the [date] credit-agreement amendment); 'Holdings, Inc.' hits p.3 and unnumbered page ([subsidiary]) and p.81-83 (credit-agreement party lists), none of which names the Company Logistics Holdings, Inc. in the consolidation note.
Absence check
- Document
- Company document
- Where it would appear
- SUBSIDIARIES OF THE REGISTRANT
- What is missing
- [subsidiary], a [state] corporation
- Pages looked at
- Exhibit 21 unnumbered page (the whole exhibit)
- Result
- 'Logistics, Inc.' and 'the Company Logistics, Inc' have no hit in Exhibit 21; 'a [state] corporation' hits only [related company]. In the 10-K, 'the Company Logistics, Inc' hits p.81-83 (credit-agreement party lists in the exhibit index) and unnumbered page (the consolidation note), none of which is Exhibit 21.
Absence check
- Document
- Company document
- Where it would appear
- SUBSIDIARIES OF THE REGISTRANT
- What is missing
- [subsidiary], the [state] subsidiary named in the consolidation note
- Pages looked at
- prior-year Exhibit 21 (one page)
- Result
- '[state] corporation' hits only [related company]; '[subsidiary]' and 'Logistics, Inc.' have no hits (the only similar name is the Company Logistics Holdings, Inc., a [state] corporation).
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.