4.15 The 2024 net capital expenditure comparative in MD&A is on a basis the 10-K does not explain
Company B · a US-listed transportation and logistics company · SEC-style question
In brief
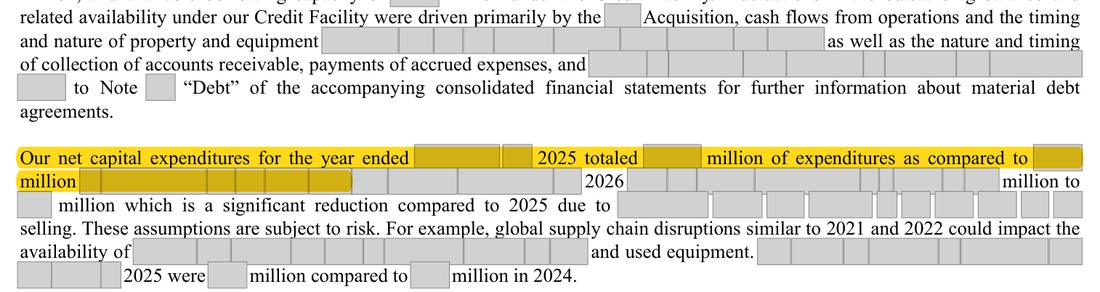
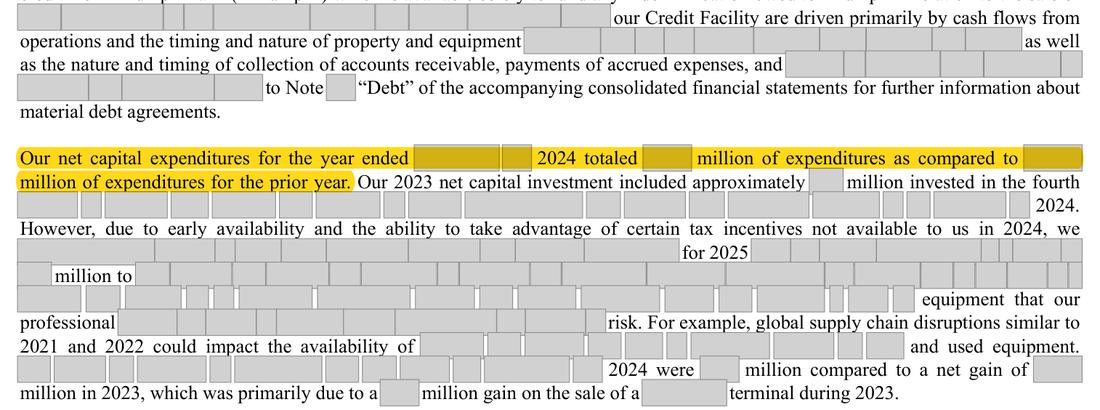
Management's discussion and analysis (MD&A) compares net capital expenditures of [amount] for 2025 with [amount] for 2024. The 2025 figure, and the 2023 figure given in last year's Form 10-K ([amount]), each equal acquisitions of property and equipment less disposal proceeds in the cash flow statement. The same computation gives [n] dollars for 2024, not [amount], and the 10-K does not say what was left out of the 2024 figure. The prior-year 10-K set a 2025 baseline of [amount] to [amount] of 'fleet' net capital expenditures; the fiscal 2025 10-K does not compare the [amount] outcome with it or say whether either year is on that fleet basis.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
2025 net capital expenditures [amount] = [n] - [n] = [n]; 2024 shown as [amount] although [n] - [n] = [n]; the gap is [n] and no basis is given. | Net capital expenditures for both years on one stated basis, with any exclusion from the cash flow lines named and quantified. |
The rule
Regulation S-K Item 303(b)(1) (17 CFR 229.303(b)(1))
Liquidity and capital resources. Analyze the registrant's ability to generate and obtain adequate amounts of cash to meet its requirements and its plans for cash in the short-term
Version: In force from [date] · Source: Regulation S-K Item 303, as amended by Release 33-10890, eCFR
Why it applies here. the 2024 figure appears to exclude some 2024 spending (for example property or other non-fleet assets) that the 2025 and 2023 figures include, or rests on another definition; the 10-K does not say which, so the year-on-year comparison in the liquidity discussion cannot be followed by a reader.
Why it matters
The liquidity discussion shows capital spending rising by about [n]% when the cash flow statement shows about [n]%, which colours the reader's view of the step-down to the [amount] to [amount] expected for 2026.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, MD&A results of operations drew 239 of the 1,774 numbered comments (13.5%): the third most frequent topic.
Exposure
A question for management; if the basis differs, a staff comment could ask for consistent presentation in future filings.
Our workings
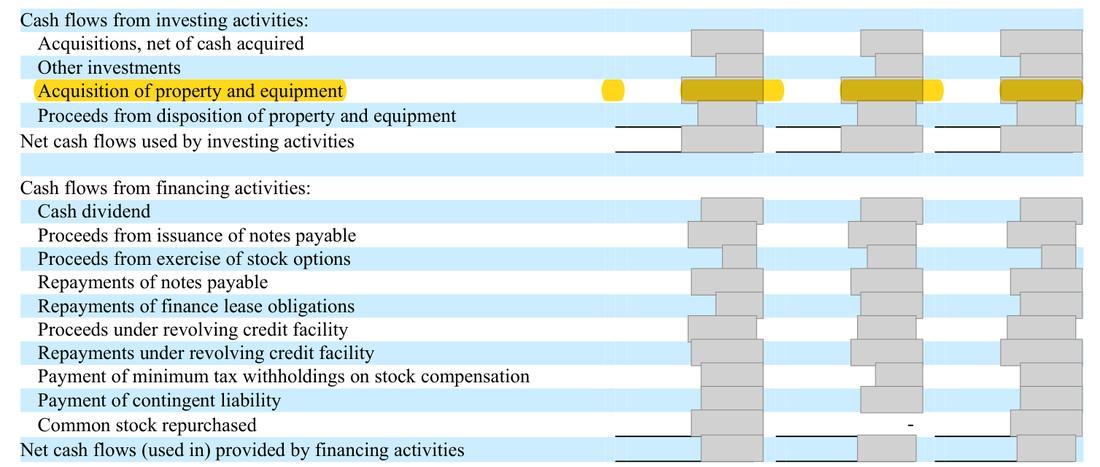
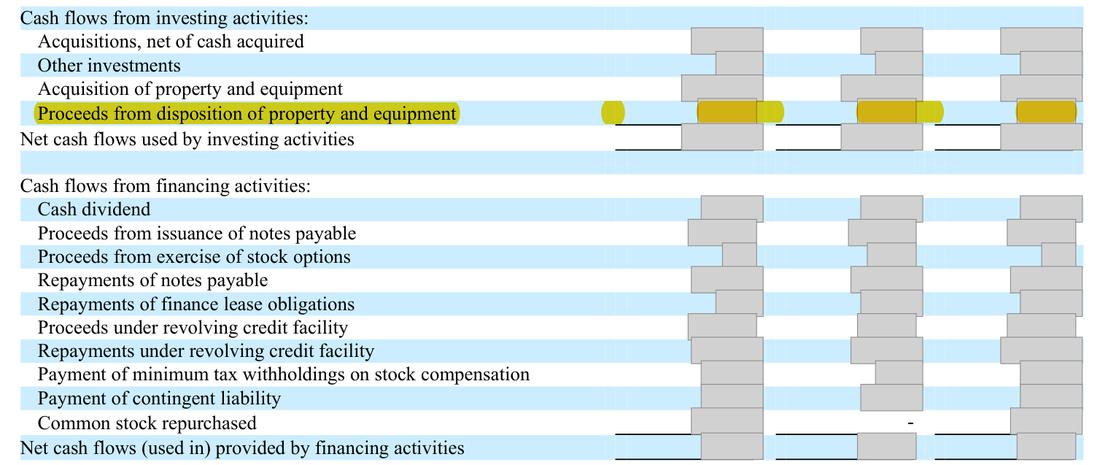
the liquidity discussion (unnumbered page) says net capital expenditures were [amount] in 2025 and [amount] in the prior year. The cash flow statement (unnumbered page) shows acquisition of property and equipment of [n] and [n] and disposal proceeds of [n] and [n] for 2025 and 2024. Last year's Form 10-K (Form 10-K 2024 (prior year) unnumbered page) gave [amount] for 2024 and [amount] for 2023, and its cash flow statement (Form 10-K 2024 (prior year) unnumbered page) shows 2023 acquisitions of [n] and proceeds of [n].
[n] - [n] = [n] (the [amount]); [n] - [n] = [n] (the [amount]); [n] - [n] = [n] against the [amount] shown, a gap of [n]. On the stated figures 2025 spending is [n]% above 2024; on the cash-flow computation it is 9.3% above.
the prior-year 10-K gave the 2025 plan as 'net capital equipment expenditures' of [amount] to [amount] (Form 10-K 2024 (prior year) unnumbered page) and as 'fleet net capital expenditures' in the same range (Form 10-K 2024 (prior year) unnumbered page).
if the [amount] for 2024 was also a fleet-only figure, that would explain part of the gap, but the fiscal 2025 10-K neither says so nor compares the 2025 outcome with the plan.
| Year | Acquisition of property and equipment less disposal proceeds (USD thousand) | Figure in MD&A |
|---|---|---|
| 2025 | [n] - [n] = [n] | [amount] |
| 2024 | [n] - [n] = [n] | [amount] |
| 2023 (prior-year 10-K) | [n] - [n] = [n] | [amount] |
| 2024 gap | [n] - [n] = [n] | |
| 2025 over 2024, as stated | [n] / [n] = [n] ([n]% higher) | |
| 2025 over 2024, cash-flow basis | [n] / [n] = [n] (9.3% higher) |
Management’s best defense, and our reply
Management could say that 'net capital expenditures' is a management measure of fleet spending and that the 2024 figure excluded a non-fleet purchase, such as property, that the company did not regard as part of the fleet program. It could add that the measure is narrative and not a statement line, so a reasonable reader should treat it as an approximation of the cash flow lines. The answer: the 2025 and 2023 figures do equal the full cash flow lines, so the 2024 figure is on a different footing from the year it is compared with, and the 10-K names no exclusion; the question remains what was left out.
The fix
- State how net capital expenditures is measured, present 2025 and 2024 on that basis (or restate 2024 as [amount]), and name any item excluded.
Question for the company
On what basis was 2024 net capital expenditure of [amount] measured, given that acquisitions less disposal proceeds in the cash flow statement give [amount] for 2024 while the same computation gives the [amount] shown for 2025 and the [amount] shown last year for 2023; what does the [amount] difference consist of, and is either year stated on the 'fleet' basis of the [amount] to [amount] 2025 baseline given in the prior-year 10-K?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | MD&A figures for 2025 and 2024 | Document | Form 10-K 2025, unnumbered page |
| 2 | Cash flow statement: acquisitions 2025 and 2024 | Document | Form 10-K 2025, unnumbered page |
| 3 | Cash flow statement: disposal proceeds 2025 and 2024 | Document | Form 10-K 2025, unnumbered page |
| 4 | Prior-year 10-K: the same [amount], and [amount] for 2023 | Document | Form 10-K 2024 (prior year), unnumbered page |
| 5 | Prior-year cash flow statement: 2024 and 2023 acquisitions as published | Document | Form 10-K 2024 (prior year), unnumbered page |
| 6 | Prior-year cash flow statement: 2024 and 2023 disposal proceeds as published | Document | Form 10-K 2024 (prior year), unnumbered page |
| 7 | Prior-year 10-K, Item 1: the 2025 plan is stated for capital equipment | Document | Form 10-K 2024 (prior year), unnumbered page |
| 8 | Prior-year 10-K, MD&A liquidity: the same plan, called fleet net capital expenditures | Document | Form 10-K 2024 (prior year), unnumbered page |
| 9 | Fiscal 2025 10-K: the 2025 outcome, with no comparison to the fleet plan and no statement of basis | Document | Form 10-K 2025, unnumbered page |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.