4.01 MD&A shows 2024 segment operating income that differs from the audited segment note, while saying prior periods were conformed
Company B · a US-listed transportation and logistics company · Compliance or disclosure gap
In brief
Management's discussion and analysis (MD&A) presents 2024 segment operating income of [n] for Segment 1 (thousand dollars) and similar figures for the other three segments, footnoted as the measure the chief operating decision maker (CODM) uses and stating that prior periods have been conformed. The audited segment note in the same Form 10-K, and the prior-year Form 10-K as published, show [n] for Segment 1 for 2024. Across the four segments the MD&A comparatives are [n] higher than the note. In [date] the company told the SEC staff that MD&A would in future present segment operating income in conformity with the segment accounting standard.
The evidence, as filed
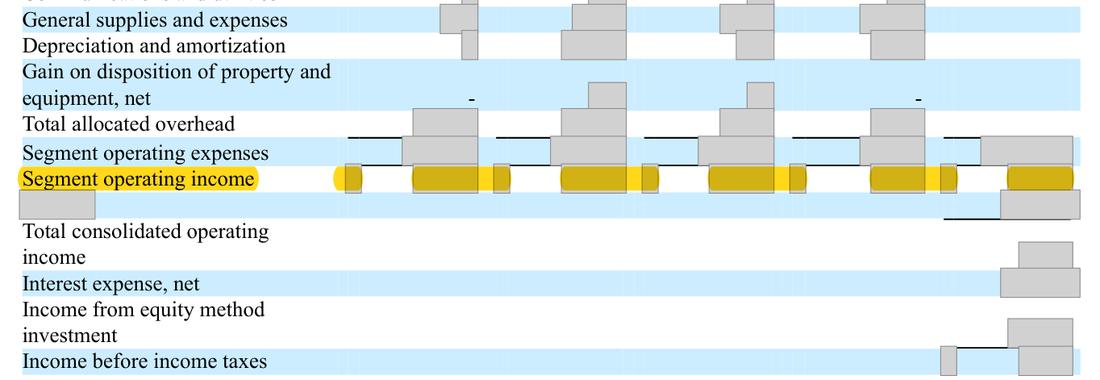
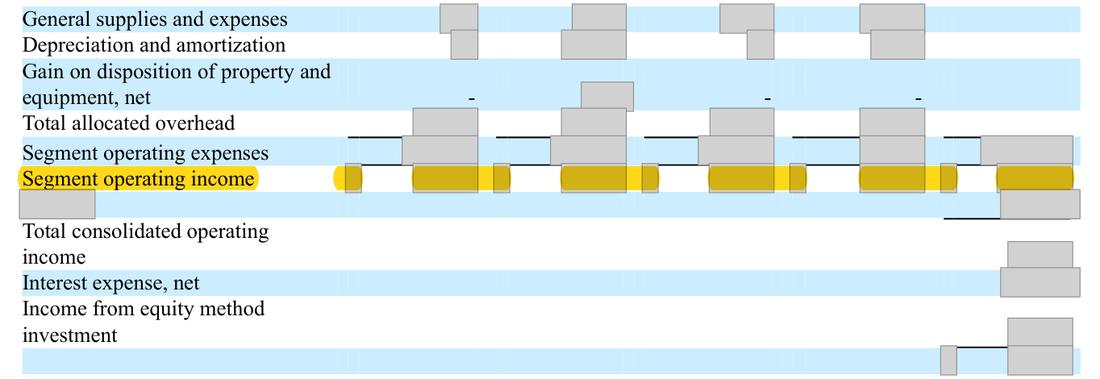
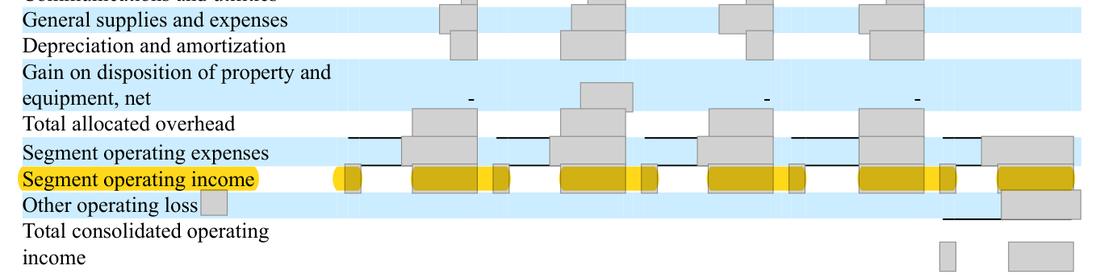
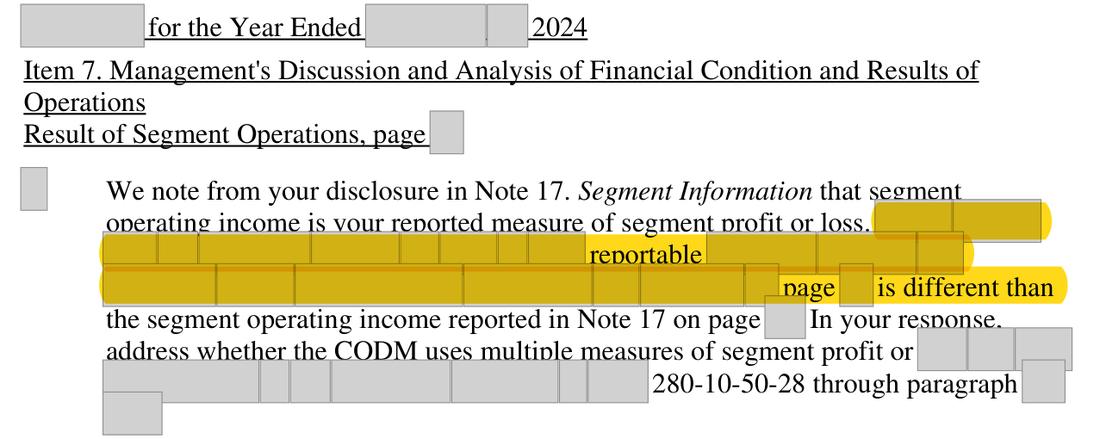
5 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
MD&A 2024 segment operating income: Segment 1 [n]; Segment 2 [n]; Segment 3 [n]; Segment 4 [n] (total [n]), described as the CODM measure with prior periods conformed. Note 17 2024: [n]; [n]; [n]; [n] (total [n]). 2025 figures agree in both places. | One 2024 segment operating income per segment throughout the Form 10-K: the Note 17 measure ([n]; [n]; [n]; [n]), with the MD&A operating ratios and narrative recomputed on it; or, if the CODM measure changed in 2025, Note 17 recast for 2024 with the change and its effect disclosed. |
The rule
Regulation S-K Item 303(b) (17 CFR 229.303(b))
Where in the registrant's judgment a discussion of segment information and/or of other subdivisions (e.g., geographic areas, product lines) of the registrant's business would be necessary to an understanding of such business, the discussion must focus on each relevant reportable segment
Version: In force from [date] · Source: Regulation S-K Item 303, as amended by Release 33-10890, eCFR
SEC Corporation Finance Non-GAAP Interpretation, Question [n]
Segment measures that are adjusted to include amounts excluded from, or to exclude amounts included in, the measure reported to the chief operating decision maker for purposes of making decisions about allocating resources to the segment and assessing its performance do not comply with Accounting Standards Codification [n]. Such measures are, therefore, non-GAAP financial measures and subject to all of the provisions of Regulation G and Item 10(e) of Regulation S-K.
Version: Text in force at the date of this review · Source: SEC Division of Corporation Finance, Compliance and Disclosure Interpretations: Non-GAAP Financial Measures, Question [n]
Regulation S-K Item 10(e)(1)(i)(B) (17 CFR 229.10(e)(1)(i)(B))
A reconciliation (by schedule or other clearly understandable method), which shall be quantitative for historical non-GAAP measures presented
Version: Text in force at the date of this review · Source: Regulation S-K Item 10(e), as amended, eCFR
Why it applies here. Only one 2024 series can be the CODM measure. No reconciliation is given, and Note 17 is not recast for any change in the measure.
Why it matters
- Year-on-year segment declines look larger in MD&A than on the audited measure: Segment 2 falls [amount] against [amount].
- This repeats a [date] SEC staff comment the company undertook to address; a further comment, or a Form 10-K/A if judged material, could follow.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, segment reporting drew 191 of the 1,774 numbered comments (10.8%): topic 4 of 25 by frequency.
Exposure
A further staff comment on a matter already raised and answered with an undertaking; a request to correct the presentation in future filings or, if judged material, a Form 10-K/A.
Our workings
the MD&A segment table (unnumbered page) and the segment table in the non-GAAP section (unnumbered page) give 2024 segment operating income of [n], footnoted as matching the information the CODM uses and stating that [wording masked]. Note 17 of the same filing (unnumbered page) gives [n] for 2024; the prior-year Form 10-K as published (Form 10-K 2024 (prior year) unnumbered page) gives the same note figures. For 2025 the MD&A and Note 17 agree ([n]). In its [date] reply to the staff's [date] comment on exactly this difference in the 2024 Form 10-K, the company undertook to present segment operating income in MD&A in conformity with the segment accounting standard.
the MD&A comparatives are higher by [n], a total of [n]; the 2024 to 2025 fall in Segment 2 is [n] on the MD&A basis against [n] on the note basis.
only one of the two 2024 series can be the measure reported to the CODM. Under the SEC staff's interpretation, a segment measure adjusted away from the CODM measure is a non-GAAP measure, which would then need a label and a reconciliation to the segment-note measure; neither is given. If instead the CODM measure changed in 2025, the segment note gives no recast of 2024 and no explanation of a change. Either way the filing presents two different 2024 values under one label, and the year-on-year segment discussion rests on the series that does not agree with the audited note.
| Segment (USD thousand) | MD&A 2024 (p.62, [n]) | Note 17 2024 (unnumbered page) | Difference |
|---|---|---|---|
| Segment 1 | [n] | [n] | [n] - [n] = [n] |
| Segment 2 | [n] | [n] | [n] - [n] = [n] |
| Segment 3 | [n] | [n] | [n] - [n] = [n] |
| Segment 4 | [n] | [n] | [n] - [n] = [n] |
| Total | [n] + [n] + [n] + [n] = [n] | [n] | [n] - [n] = [n] |
| Segment 2 fall 2024 to 2025 | [n] - [n] = [n] | [n] - [n] = [n] | [n] - [n] = [n] |
Management’s best defense, and our reply
Management could say that the CODM's allocation of indirect costs was refined in 2025 and that the 2024 MD&A columns were recast to that refined basis so that the year-on-year comparison is like for like, which is what the footnote means by 'conformed'. It could add that Note 17 shows 2024 as the CODM actually received it, so each series serves its own purpose. The answer: the segment standard requires the note itself to be recast (or the change explained) when the measure changes, and Note 17 shows 2024 unchanged from the prior-year filing with no mention of any change; a recast series that lives only in MD&A is, under the staff's interpretation, a non-GAAP measure that needs a label and a reconciliation, and none is given. That reading does not answer the [date] undertaking, which was to present the note measure in MD&A.
The fix
- Replace the 2024 MD&A segment operating income with the Note 17 figures ([n] / [n] / [n] / [n]), recompute the 2024 segment operating ratios and the segment narrative, and delete '[wording masked]' unless the note itself is recast; if the CODM measure did change in 2025, recast Note 17 for 2024 and state the change and its effect.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | MD&A segment table: 2025 and 2024 segment operating income for Segment 2 (the other segments follow in the same table) | Document | Form 10-K 2025, unnumbered page |
| 2 | MD&A 2024 Segment 3 segment operating income [n] | Document | Form 10-K 2025, unnumbered page |
| 3 | MD&A 2024 Segment 4 segment operating income [n] | Document | Form 10-K 2025, unnumbered page |
| 4 | Non-GAAP section repeats the same series, including Segment 1 2024 of [n] | Document | Form 10-K 2025, unnumbered page |
| 5 | MD&A says the figures are the CODM measure and that 2024 was conformed | Document | Form 10-K 2025, unnumbered page |
| 6 | Note 17, 2025: agrees with MD&A for every segment | Document | Form 10-K 2025, unnumbered page |
| 7 | Note 17, 2024: the audited CODM measure differs from the MD&A 2024 column | Document | Form 10-K 2025, unnumbered page |
| 8 | Prior-year Form 10-K as published: the same 2024 note figures, so the note was not recast | Document | Form 10-K 2024 (prior year), unnumbered page |
| 9 | SEC staff comment of [date] on the same difference in the prior-year Form 10-K | Document | |
| 10 | Company's undertaking to the staff, [date] | Document | |
| 11 | The company's [date] undertaking to the SEC staff on the MD&A segment measure | Document | |
| 12 | MD&A Segment 1 segment operating income, 2025 and 2024 | Document | Form 10-K 2025, unnumbered page |
| 13 | Note 17: 2024 segment operating income, Segment 1 [n] | Document | Form 10-K 2025, unnumbered page |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.