1.27 Three different amounts are given for the 2024 change in fair value of the earn-out liability
Company B · a US-listed transportation and logistics company · SEC-style question
In brief
For 2024 the Note 3 rollforward records a fair value increase of [n] (thousand dollars) in the earn-out (contingent consideration) liability. The narrative of the same note attributes [amount] to [acquisition 2] and [amount] to [acquisition 3], which add to [amount]. The management's discussion and analysis (MD&A) non-GAAP table adds back [n] for the same item, and the prior-year Form 10-K split that [n] into [n] for Segment 2 and [n] for Segment 3. The rollforward and the add-back differ by [n], and only management can say which amount was charged to 2024 operating expenses.
The evidence, as filed
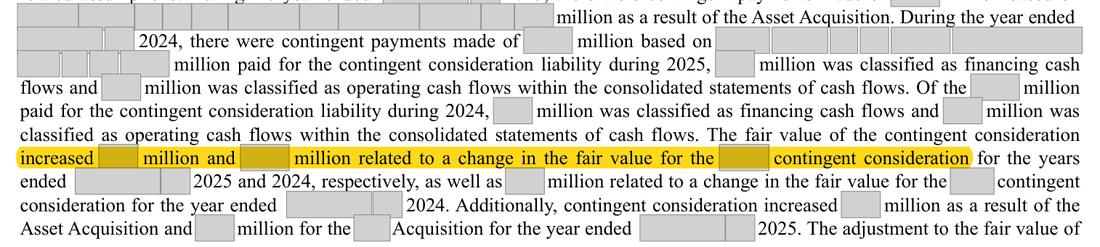
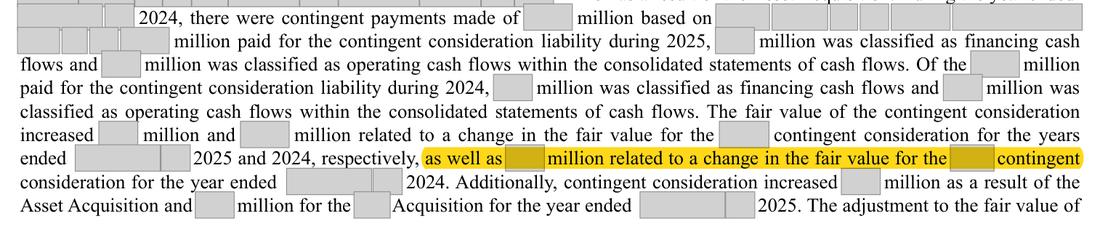
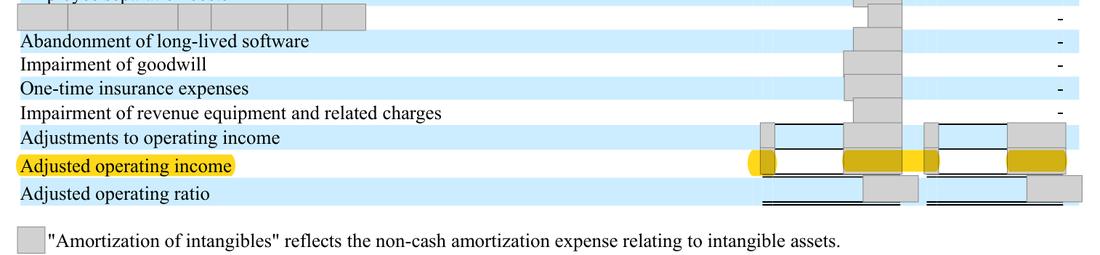
3 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Note 3 rollforward 2024: adjustments to fair market value ([n]). Note 3 narrative: [acquisition 2] [amount] plus [acquisition 3] [amount]. MD&A non-GAAP 2024: contingent consideration liability adjustment [n]; prior-year Form 10-K: Segment 2 ([n]) and Segment 3 ([n]). | One amount for the 2024 fair value change, used in the rollforward, the narrative and the non-GAAP reconciliation, with the [acquisition 2] and [acquisition 3] parts adding to it. |
The rule
Consistency of note, narrative and non-GAAP reconciliation
Why it applies here. either the non-GAAP add-back (and the 2024 adjusted operating income derived from it) is overstated by [n], or [n] of the charge sits outside the liability and the rollforward and narrative do not explain it. The difference is small in money but the reconciliation of a non-GAAP measure to the audited figures should be exact, and the note narrative should describe the rollforward it accompanies.
Why it matters
If the rollforward is right, the 2024 adjusted operating income and adjusted operating ratio presented as non-GAAP measures are overstated by [n]; if the add-back is right, the audited note does not explain [n] of the charge.
Exposure
A question: no exposure is asserted until management confirms the 2024 charge.
Our workings
the 2024 row of the Note 3 rollforward reads opening ([n]), additions nil, fair value adjustments ([n]), payments [n], closing ([n]) and it foots. The note narrative says the liability increased [amount] for [acquisition 2] and [amount] for [acquisition 3] in 2024 (unnumbered page). The MD&A non-GAAP table adds back a contingent consideration liability adjustment of [n] for 2024 to reach adjusted operating income of [n], and the prior-year Form 10-K shows the same [n] split [n] Segment 2 (where [acquisition 2] reports) and [n] Segment 3 (where [acquisition 3] reports).
the add-back exceeds the rollforward by [n]; the narrative parts add to [amount], not [amount]; if the [acquisition 2] part is [n], the [acquisition 3] part implied by the rollforward is [n], not [n].
| Comparison | Arithmetic (USD thousand) |
|---|---|
| 2024 rollforward foots | -[n] + 0 - [n] + [n] = -[n] |
| Non-GAAP add-back less rollforward | [n] - [n] = [n] |
| Prior-year segment split of the add-back | [n] + [n] = [n] |
| [acquisition 3] part implied by the rollforward | [n] - [n] = [n] |
| Note narrative parts (USD million) | [n] + [n] = [n] |
| 2024 adjusted operating income if the add-back were [n] | [n] - [n] = [n] |
Management’s best defense, and our reply
The rollforward is the audited figure and the narrative rounds it; the non-GAAP table may add back a further [n] that management groups with the earn-out adjustment, for example an earn-out related cost recorded outside the liability, and [n] is under one percent of 2024 adjusted operating income. That reading is possible, which is why the point is a question rather than a finding. However, no such item is described anywhere in either Form 10-K, and the prior-year segment split puts [n] against Segment 3 while the note gives [acquisition 3] only [amount], so the figures cannot all be right as printed.
The fix
- Confirm the 2024 charge. If it is [n], restate the 2024 non-GAAP add-back to [n] (adjusted operating income [n]) in the next filing that presents 2024, and correct the narrative to '[acquisition 2] [amount] and [acquisition 3] [amount]'; if it is [n], explain the [n] that is not in the rollforward.
Question for the company
Which amount was charged to 2024 general supplies and expenses for the change in fair value of contingent consideration - [n] as in the Note 3 rollforward, or [n] as added back in the non-GAAP table - and how was it split between [acquisition 2] and [acquisition 3]?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | 2024 rollforward: fair value adjustment of [n] | Document | Form 10-K 2025, page 66 |
| 2 | Narrative: [amount] of the 2024 change attributed to [acquisition 2] | Document | Form 10-K 2025, unnumbered page |
| 3 | Narrative: a further [amount] in 2024 attributed to [acquisition 3] | Document | Form 10-K 2025, unnumbered page |
| 4 | MD&A non-GAAP table adds back [n] for 2024 | Document | Form 10-K 2025, page 39 |
| 5 | 2024 adjusted operating income built on the [n] add-back | Document | Form 10-K 2025, page 39 |
| 6 | Prior-year Form 10-K: the [n] split by segment (combined, Segment 1, Segment 2, Segment 3, Segment 4) | Document | Form 10-K 2024 (prior year), page 39 |
| 7 | The prior-year MD&A gives the 2024 earn-out increase as [amount] and attributes it to [acquisition 2] | Document | Form 10-K 2024 (prior year), page 34 |
| 8 | The prior-year Note 3 gives the 2024 fair value adjustment as [amount] | Document | Form 10-K 2024 (prior year), unnumbered page |
| 9 | The prior-year non-GAAP table adds back [n], split [n] Segment 2 and [n] Segment 3 | Document | Form 10-K 2024 (prior year), page 39 |
| 10 | As published in the fiscal 2024 10-K, the 2024 roll-forward shows a fair value adjustment of [n]. | Document | Form 10-K 2024 (prior year), page 66 |
| 11 | The same note's narrative gives the whole 2024 adjustment as [amount], with no split between [acquisition 2] and [acquisition 3]. | Document | Form 10-K 2024 (prior year), unnumbered page |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.