1.11 The 2024 column of the other assets table does not add up and does not agree with the balance sheet
Company B · a US-listed transportation and logistics company · Presentation point
In brief
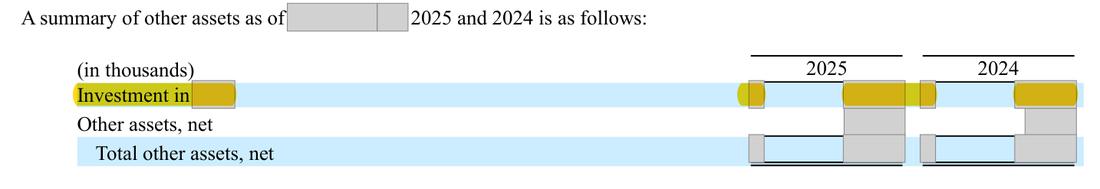
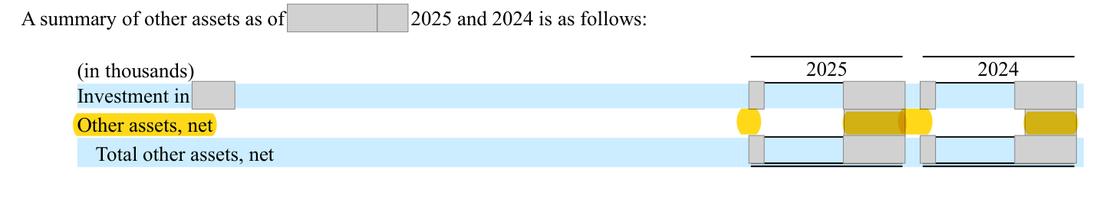
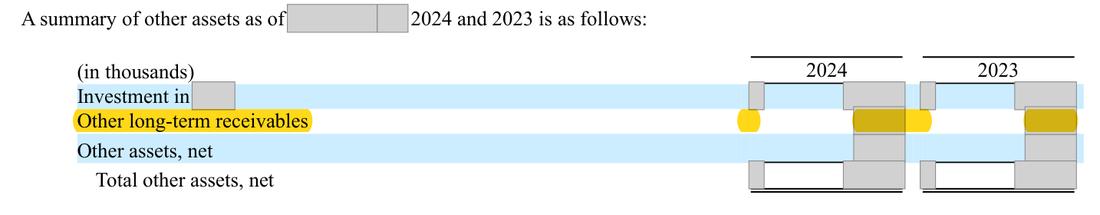
The other assets table in Note 9 shows, for [date], investment in [equity investee] of [n] and other assets of [n] (thousand dollars) but a total of [n]. The two lines add to [n], which is the 2024 'Other assets, net' on this year's balance sheet. The [n] is the prior-year total, which included [n] of other long-term receivables; this year the balance sheet shows those receivables on their own line, but the note dropped the line and kept the old total.
The evidence, as filed
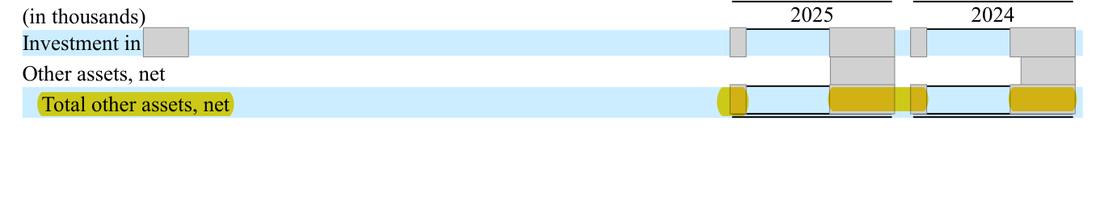
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Note 9, 2024 column: Investment in [equity investee] [n]; Other assets, net [n]; Total other assets, net [n]. Balance sheet 2024: Other receivables [n]; Other assets, net [n]. | Note 9, 2024 column total [n], agreeing with the balance sheet (or the [n] of other long-term receivables shown as a line with a reconciling note). |
The rule
Note-to-balance-sheet consistency
Why it applies here. The printed total exceeds its lines by [amount]. The 2025 column ([amount]) is correct, and no balance-sheet amount is affected.
Why it matters
- A comparative total that neither adds nor agrees to the balance sheet undermines confidence in the notes.
- It may prompt a staff question on the 2024 reclassification; there is no penalty exposure.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, financial statement presentation drew 254 of the 1,774 numbered comments (14.3%): the second most frequent topic.
Exposure
Presentation inconsistency; no audited balance-sheet amount is misstated.
Our workings
the Note 9 table prints a 2024 total of [n] below lines of [n] and [n] (unnumbered page). The 2025 balance sheet shows for 2024 a new caption 'Other receivables' of [n] and 'Other assets, net' of [n] (unnumbered page). The prior-year Form 10-K presented a single 'Other assets' caption of [n] and its note included 'Other long-term receivables' of [n] (p.68 of that report).
the 2024 lines add to [n] and the printed total exceeds them by [n] (see recompute).
when the comparative balance sheet was re-presented to split out other receivables, the note was updated by deleting the receivables line but not the total; the 2025 column ([n] + [n] = [n]) is correct. No audited balance-sheet figure is wrong, but the note table does not cast and does not agree with the face of the balance sheet for the comparative year.
| Check | Arithmetic (USD thousand) |
|---|---|
| 2024 lines of the note table | [n] + [n] = [n] |
| Printed total less sum of lines | [n] - [n] = [n] |
| Prior-year presentation | [n] + [n] + [n] = [n] |
| 2025 column (casts) | [n] + [n] = [n] |
Management’s best defense, and our reply
The balance sheet itself is right and the 2024 column was carried from the prior-year note, which tied to the prior-year balance sheet; readers can see the split on the face of the statement. The difference is a presentation slip in a supporting table, not a measurement error. However, the note as printed does not add, and it supports a balance-sheet caption whose 2024 amount is now [n], so it should be corrected; the point is kept at the lowest weight.
The fix
- Correct the 2024 total to [n] (or restore the 'Other long-term receivables [n]' line with a note that it is now presented separately on the balance sheet).
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Note 9 other assets table: [equity investee] line, 2025 and 2024 | Document | Form 10-K 2025, unnumbered page |
| 2 | Note 9 other assets table: other assets line, 2025 and 2024 | Document | Form 10-K 2025, unnumbered page |
| 3 | Printed 2024 total of [n] exceeds the two lines above it | Document | Form 10-K 2025, unnumbered page |
| 4 | Balance sheet now shows the [n] of 2024 other receivables on its own line | Document | Form 10-K 2025, unnumbered page |
| 5 | Balance sheet 2024 other assets, net is [n] | Document | Form 10-K 2025, unnumbered page |
| 6 | Prior-year note included the [n] receivables in the [n] total | Document | Form 10-K 2024 (prior year), unnumbered page |
| 7 | As published in the fiscal 2024 10-K, the other assets table carried a [n] line of other long-term receivables for [date]. | Document | Form 10-K 2024 (prior year), unnumbered page |
| 8 | With that line the published 2024 column foots: [n] + [n] + [n] = [n]; the current-year comparative keeps this total but drops the [n] line. | Document | Form 10-K 2024 (prior year), unnumbered page |
| 9 | The fiscal 2024 note explained what the [n] line was; the current-year note replaces this sentence with a description of life insurance policies and prepaid expenses. | Document | Form 10-K 2024 (prior year), unnumbered page |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.