1.10 The [acquisition 3] and [acquisition 2] notes give a lowest total purchase price that already includes the fair value of the earn-out, although no earn-out may be paid
Company B · a US-listed transportation and logistics company · Presentation point
In brief
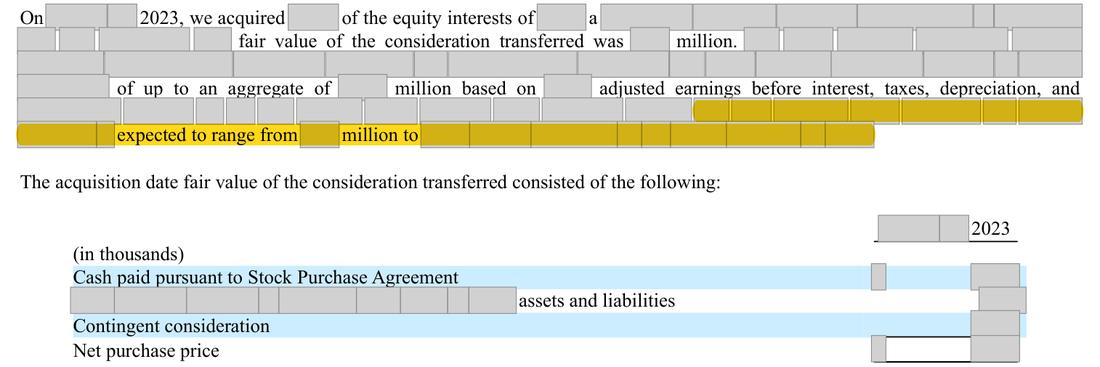
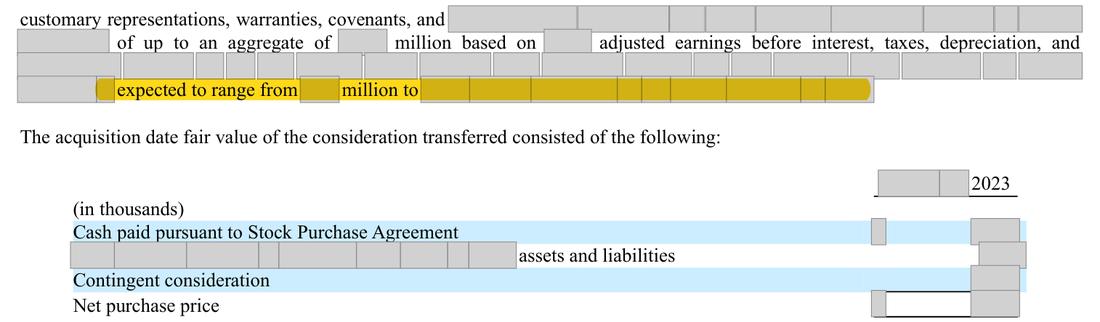
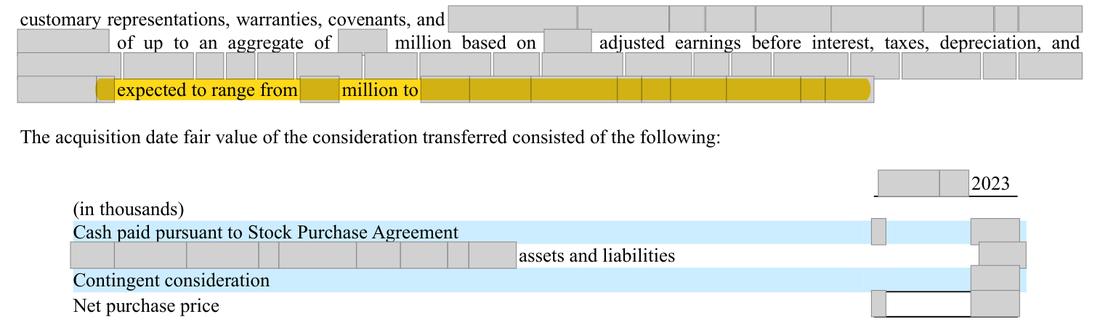
Both [n]-Ks say the total purchase price of [acquisition 3], 'including any earnout achieved', will range from [amount] to [amount], and that of [acquisition 2] from [amount] to [amount]. The low ends are the acquisition-date fair values, which already include the earn-outs at their fair value ([n] and [n]). If no earn-out is achieved, the notes' own tables give net cash prices of [amounts]. The high ends are worked on that cash basis, so each range mixes two bases.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
[acquisition 3]: 'expected to range from [amount] to [amount]'; net cash paid [n] ([n] less [n] cash acquired), earn-out at fair value [n], cap [amount]. [acquisition 2]: 'expected to range from [amount] to [amount]'; net cash paid [n] ([n] less [n]), earn-out at fair value [n], cap [amount]. | Ranges on one basis: [acquisition 3] from about [amount] (no earn-out) to [amount] (full earn-out); [acquisition 2] from about [amount] to [amount]; or a statement that the acquisition-date fair value of [amounts] is fixed and later earn-out changes go through earnings. |
The rule
Exchange Act Rule 12b-20
there shall be added such further material information, if any, as may be necessary to make the required statements, in the light of the circumstances under which they are made not misleading.
Version: Text in force at the date of this review · Source: 17 CFR 240.12b-20, as in force for fiscal 2024 and 2025
Why it applies here. The low ends are acquisition-date fair values; the high ends are cash totals. Readers are told the lowest price is [amounts] when the contracts allow [amounts].
Why it matters
- The two ends of each range cannot be compared, and the minimum price is overstated by the earn-out fair value.
- A presentation point the staff could ask to correct in future filings; no reported amount changes.
Exposure
A narrative inconsistency in the acquisition notes; no recognized amount is affected.
Our workings
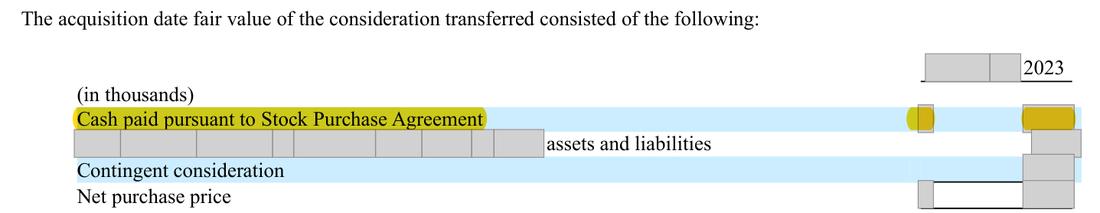
the [acquisition 3] note says the purchase agreement includes an earn-out of up to [amount] and that the total purchase price, including any earn-out achieved, is expected to range from [amount] to [amount]. Its consideration table shows cash paid of [n], cash acquired of ([n]) and contingent consideration of [n], a net purchase price of [n] (thousand dollars). The [acquisition 2] note gives an earn-out of up to [amount] and a range of [amount] to [amount], with cash paid [n], cash acquired ([n]) and contingent consideration [n] (net [n]). The fiscal 2024 10-K printed the same sentences and tables.
with no earn-out, [acquisition 3] costs [n] - [n] = [n] and [acquisition 2] [n] - [n] = [n]; with the full earn-out, [n] + [n] = [n] and [n] + [n] = [n]. The printed low ends equal the acquisition-date fair values ([n] and [n]), which include [n] and [n] of earn-out at fair value.
each range takes its low end on a fair-value basis and its high end on a cash basis, so the lowest outcome is overstated by the earn-out's fair value. The required earn-out disclosure itself (the cap) is given, so this is a narrative inconsistency, not a missing disclosure.
| Step | Computation | Result |
|---|---|---|
| [acquisition 3]: no earn-out, printed low end, full earn-out | [n] - [n] = [n]; [n] + [n] = [n]; [n] + [n] = [n] | [amount] with no earn-out against [amount] printed (the fair value including the earn-out); [amount] high end agrees |
| [acquisition 2]: no earn-out, printed low end, full earn-out | [n] - [n] = [n]; [n] + [n] = [n]; [n] + [n] = [n] | [amount] with no earn-out against [amount] printed (the fair value including the earn-out); [amount] against [amount] printed (rounding) |
| Overstatement of the two low ends | [n] - [n] = [n]; [n] - [n] = [n]; [n] + [n] = [n]; [n] / [n] = [n]% | [n] USD thousand, [n]% of 2024 pre-tax income; narrative only, no recognized amount affected |
Management’s best defense, and our reply
Management could say that the low end is the acquisition-date fair value of the consideration, which is the purchase price recognized under the business combination standard and does not change when the earn-out is remeasured, so [amounts] are the accounting purchase prices. They could add that the earn-out caps are disclosed separately, so a reader can work out the cash range. However, the sentence speaks of the total purchase price 'including any earnout achieved' and its high end is a cash figure, so the low end must be read on the same basis; on that basis a nil earn-out gives [amounts]. The defense explains the source of the figure but not the mixed basis.
The fix
- State the ranges on one basis, for example: 'Including any earnout achieved, total cash consideration will range from [amount] (no earnout) to [amount] (maximum earnout)', and the equivalent [amount] to [amount] for [acquisition 2].
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | [acquisition 3] range as printed in the fiscal 2025 10-K | Document | Form 10-K 2025, unnumbered page |
| 2 | [acquisition 3] cash paid | Document | Form 10-K 2025, unnumbered page |
| 3 | [acquisition 3] cash acquired and earn-out at fair value | Document | Form 10-K 2025, unnumbered page |
| 4 | [acquisition 3] earn-out cap | Document | Form 10-K 2025, unnumbered page |
| 5 | [acquisition 2] range as printed in the fiscal 2025 10-K | Document | Form 10-K 2025, unnumbered page |
| 6 | [acquisition 2] cash paid | Document | Form 10-K 2025, unnumbered page |
| 7 | [acquisition 2] cash acquired and earn-out at fair value | Document | Form 10-K 2025, unnumbered page |
| 8 | [acquisition 2] earn-out cap | Document | Form 10-K 2025, unnumbered page |
| 9 | The fiscal 2024 10-K printed the same [acquisition 3] range | Document | Form 10-K 2024 (prior year), unnumbered page |
| 10 | The [acquisition 3] low end equals the acquisition-date fair value including the earn-out | Document | Form 10-K 2024 (prior year), unnumbered page |
| 11 | The fiscal 2024 10-K printed the same [acquisition 2] range | Document | Form 10-K 2024 (prior year), unnumbered page |
| 12 | The [acquisition 2] low end equals the acquisition-date fair value including the earn-out | Document | Form 10-K 2024 (prior year), unnumbered page |
| 13 | 2024 pre-tax income used for the materiality comparison | Document | Form 10-K 2025, unnumbered page |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.