7.01 Part I slips: a risk-factor cross-reference to a heading that does not exist, a leased lodging property called wholly-owned, and four word errors
Company A · a US-listed consumer leisure company · Drafting slip
In brief
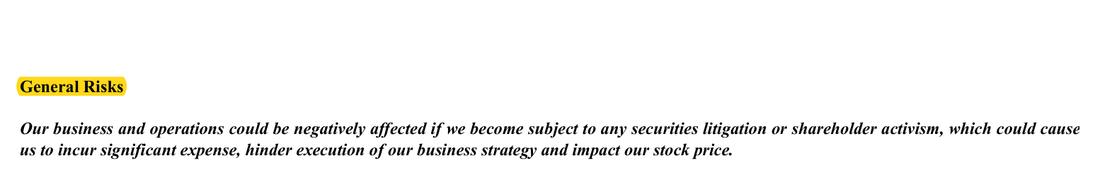
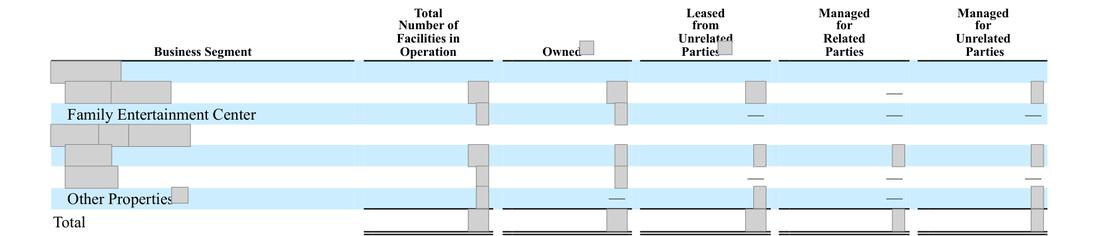
The stock-price risk factor refers readers to a section headed 'Risks related to our business and industry', which does not exist; the risk it points to sits under 'General Risks' on the same page. Item 1 calls the seven owned lodging properties 'wholly-owned' although one of them, the [property name] [city] [property name], is operated under a long-term lease. Four word errors also appear: '[product description]' (twice), 'complimented by', 'adversely effecting' and 'become senior vice president'.
The evidence, as filed
4 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Cross-reference to a non-existent heading; 'seven owned and operated lodging properties' including a leased lodging property; 'complementary', 'complimented', 'effecting', 'become'. | See 'General Risks - Our business and operations could be negatively affected ...'; 'seven owned or leased and operated lodging properties'; 'complimentary', 'complemented', 'affecting', 'became'. |
Why it matters
Readers following the cross-reference find no such heading; the ownership description slightly overstates the owned estate.
Exposure
Drafting only; no filing consequence.
Our workings
Each slip is shown on its page. The properties table in Item 2 classes one lodging property as leased from an unrelated party, and Item 1 says the [property name] [city] [property name] is operated under a long-term lease, so the group of seven includes a leased lodging property. The cross-reference and the 'complementary' and 'become' slips also appear in the prior-year report.
Management’s best defense, and our reply
The company would say the reader can find the referenced risk factor on the same page and that the [property name] is clearly described as leased two pages later and in the properties table. It would add that none of the slips changes a figure. That is right, which is why these are drafting slips only; they are still worth correcting before the next filing because the cross-reference has now been carried for two years.
The fix
- Change the cross-reference to 'General Risks - Our business and operations could be negatively affected ...'; write 'seven owned or leased and operated lodging properties'; correct complimentary, complemented, affecting and became.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Cross-reference to a heading that appears nowhere in the report | Document | Form 10-K 2025, page 18 |
| 2 | The risk factor referred to sits under this heading on the same page | Document | Form 10-K 2025, page 18 |
| 3 | All seven described as wholly-owned | Document | Form 10-K 2025, page 1 |
| 4 | The [state] lodging property among the seven is leased | Document | Form 10-K 2025, page 7 |
| 5 | Properties table: one lodging property leased from an unrelated party | Document | Form 10-K 2025, page 21 |
| 6 | Should read complimentary (also later on the same page) | Document | Form 10-K 2025, page 4 |
| 7 | Should read complemented | Document | Form 10-K 2025, page 5 |
| 8 | Should read affecting | Document | Form 10-K 2025, page 13 |
| 9 | Should read became | Document | Form 10-K 2025, page 22 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.