1.11 Convertible note repurchase: the cash flow line exceeds the consideration in Note 5 by [amount]
Company A · a US-listed consumer leisure company · SEC-style question
In brief
Note 5 says holders exchanged [amount] of Convertible Notes for cash consideration of [amount] in fiscal 2024, but the statement of cash flows shows [amount] paid under financing activities for the same repurchase. MD&A describes the [amount] as paid for the repurchases 'and related transaction costs', but the third-quarter 2025 Form 10-Q says each tranche was bought for its cash consideration 'plus accrued interest'. Neither filing says how much of the [amount] difference is interest, which would be an operating, not a financing, cash flow.
The evidence, as filed
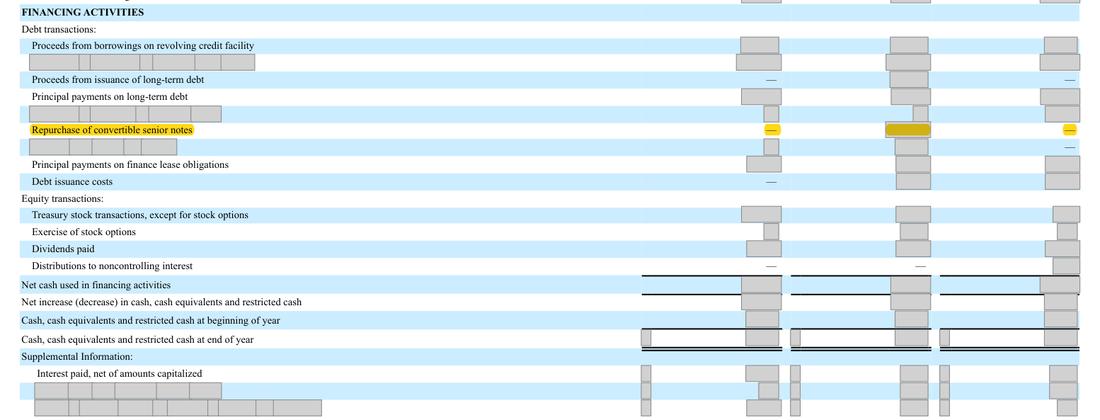
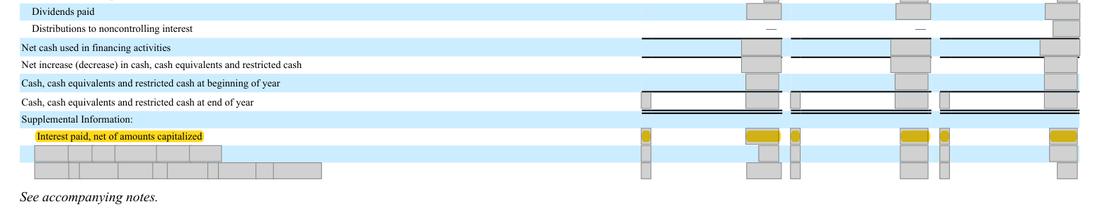
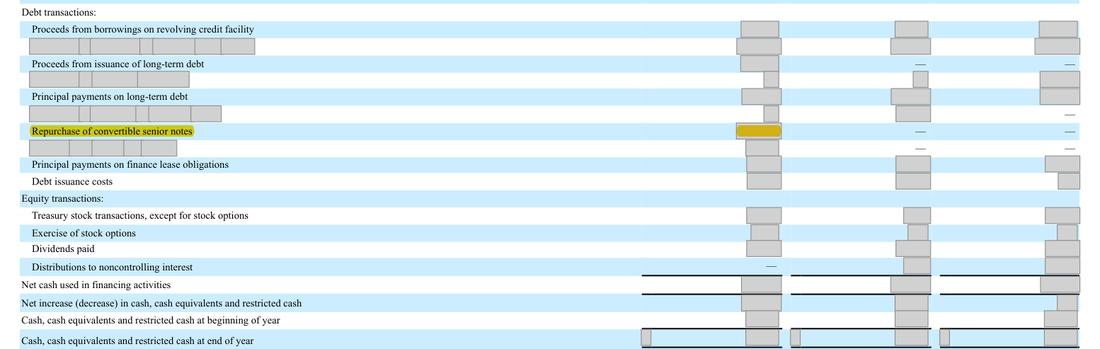
4 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Financing activities, fiscal 2024: repurchase of convertible senior notes ([n]). Note 5: cash consideration of [amount]. MD&A: [amount] paid for the repurchases 'and related transaction costs'. The third-quarter 2025 Form 10-Q: each tranche settled for its consideration 'plus accrued interest'. No figure splits the [n] between interest and transaction costs. | The two figures agree, or the note explains the difference; any interest component is shown in operating activities and within interest paid. |
The rule
FASB ASC 230-10-45-10 to 45-17 (classification of cash receipts and payments)
Summary; FASB/IFRS text is copyrighted Classify cash receipts and payments as operating, investing or financing by their nature, present gross flows, include restricted cash, and disclose significant noncash activities.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 230-10-45 (as amended by ASU 2016-15 and ASU 2016-18), paraphrased
Why it applies here. the cash flow standard classifies receipts and payments by their nature; repayment of principal and debt extinguishment costs are financing outflows, but cash paid for interest is an operating outflow even when it is paid on the day the debt is retired. The company's own wording points both ways: MD&A attributes the excess to transaction costs, while the Form 10-Q says accrued interest was paid on top of the consideration. If part of the [n] is accrued coupon, fiscal 2024 operating cash flow is overstated and interest paid understated by that part; if it is all transaction cost, financing is right and only Note 5 needs a reconciling sentence. The filings do not allow either reading to be confirmed.
Why it matters
If part of the difference is accrued interest, fiscal 2024 operating cash flow is overstated, financing outflow overstated and interest paid understated by that part (at most [amount]); if it is all settlement or transaction cost, only a reconciling sentence is missing.
Exposure
A question; if the answer is accrued interest, the fiscal 2024 comparative would need a revision in a later filing. No fine applies.
Our workings
Note 5 states the repurchase consideration as [amount]; the fiscal 2024 financing line shows ([n]); the prior-year report carries the same two figures. The liquidity discussion in both years says [amount] was paid for the repurchases and related transaction costs. The third-quarter 2025 Form 10-Q describes the tranches as retired for their cash consideration plus accrued interest. Supplemental interest paid was [amount] for fiscal 2024.
the difference is [n], or [n]% of the line; the notes carried a 5.00% coupon on [amount], about [n] a year, so the difference equals about [n] months of coupon (workings).
| Item | Computation | Result |
|---|---|---|
| Cash flow line less consideration in Note 5 | [n] - [n] = [n] | [n] |
| Difference against the cash flow line | [n] / [n] = [n]% | [n]% |
| Annual coupon on the Convertible Notes | [n] x 5.00% = [n] | [n] |
| Difference expressed in months of coupon | [n] / [n] x [n] = [n] | [n] |
Management’s best defense, and our reply
The finance team would say the note gives the negotiated repurchase price, while the cash flow line records every payment made to retire the notes on the settlement dates, that MD&A already says the cash paid included related transaction costs, and that payments to extinguish debt, including prepayment and extinguishment costs, are financing cash flows. It would add that the amount is [n]% of the line and that the staff examined this very transaction in 2026 and closed its review. That answer holds for transaction and extinguishment costs but not for coupon interest, which is an operating cash flow whatever the occasion of payment, and the company's own Form 10-Q says accrued interest was paid on top of the consideration; only the company can say how the [n] splits, so the point is put as a question.
The fix
- Add one sentence to Note 5 reconciling the consideration to the cash flow line and, if interest is included, move it to operating activities and interest paid in the fiscal 2024 column with a brief revision note.
Question for the company
How does the [amount] by which the fiscal 2024 cash flow line for the repurchase of convertible senior notes exceeds the [amount] cash consideration in Note 5 split between the accrued interest paid at settlement and the related transaction costs? If it includes interest, why is that part presented in financing activities rather than in operating activities and in interest paid?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Note 5 gives the cash consideration for the fiscal 2024 repurchase | Document | Form 10-K 2025, page 70 |
| 2 | The fiscal 2024 financing outflow for the same repurchase | Document | Form 10-K 2025, page 58 |
| 3 | Coupon rate and principal of the notes repurchased | Document | Form 10-K 2025, page 69 |
| 4 | Supplemental interest paid, fiscal 2025, 2024 and 2023 | Document | Form 10-K 2025, page 58 |
| 5 | The prior-year report gives the same consideration | Document | Form 10-K 2024 (prior year), page 70 |
| 6 | The prior-year cash flow statement shows the same outflow | Document | Form 10-K 2024 (prior year), unnumbered page |
| 7 | MD&A attributes the cash paid to the repurchases and related transaction costs, without mentioning interest | Document | Form 10-K 2025, page 45 |
| 8 | The third-quarter 2025 Form 10-Q says the first tranche was settled for its consideration plus accrued interest (the same wording is used for each tranche) | Document |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.