1.10 Prior-year Other operating expenses were re-presented to show (gain) loss on disposition separately, with no reclassification statement
Company A · a US-listed consumer leisure company · SEC-style question
In brief
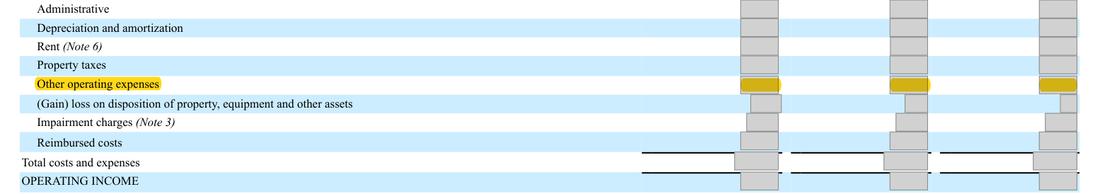
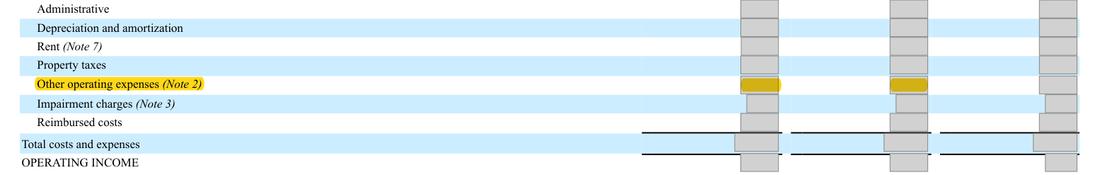
This statement of operations adds a line, '(Gain) loss on disposition of property, equipment and other assets', showing [n] for fiscal 2024 and [n] for fiscal 2023. The prior-year Form 10-K had no such line and showed Other operating expenses of [n] and [n]; this filing shows [n] and [n], and the differences are exactly the new line. Nothing in the notes says the comparatives were reclassified.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Fiscal 2024 Other operating expenses [n] plus a new (gain) loss line of [n] (published: [n]); fiscal 2023 [n] plus [n] (published: [n]); no reclassification statement | A sentence in Note 1 that prior-year amounts were reclassified to show (gain) loss on disposition separately, or a documented conclusion that the change needs no explanation |
Why it matters
A reader comparing the two filings sees fiscal 2024 Other operating expenses fall from [n] to [n] without an explanation; nothing else changes.
Exposure
Presentation only; operating income and net earnings are unchanged.
Our workings
the comparative columns of Other operating expenses differ from the figures published in the prior-year Form 10-K, and a new (gain) loss on disposition line appears.
[n] + [n] = [n] and [n] + [n] = [n], so the whole difference is the amount moved to the new line; total costs and operating income are unchanged.
the comparatives were re-presented. The FASB Codification's guidance on changes in comparative statements (paraphrased) asks for information explaining a change in the way corresponding items are presented for two or more periods, and the searches found no such sentence. Because the amounts are small and visible elsewhere, this is put as a question.
| Fiscal year | Other operating expenses as published (prior-year 10-K) | Other operating expenses now | New (gain) loss line | Check |
|---|---|---|---|---|
| 2024 | [n] | [n] | [n] | [n] + [n] = [n] |
| 2023 | [n] | [n] | [n] | [n] + [n] = [n] |
| Size | [n] / [n] = 0.91% of the published line |
Management’s best defense, and our reply
Management would say the amounts are trivial against total costs, operating income is unchanged, the same amounts already appeared on the (gain) loss line of the cash flow statement, the prior-year segment note said these gains and losses sat in other items, and MD&A discusses the fiscal 2024 net loss on disposition. That is a tenable materiality position. However, the codification asks for an explanation whenever the presentation of corresponding items changes, and a one-line statement removes the question; it is therefore raised as a question, not a gap.
The fix
- Add to Note 1: 'Certain prior-year amounts have been reclassified to conform to the current-year presentation, including the separate presentation of (gain) loss on disposition of property, equipment and other assets.'
Question for the company
Were the fiscal 2024 and 2023 (gain) loss on disposition amounts ([n] and [n]) moved out of Other operating expenses for this filing, and was it decided that no reclassification statement was needed?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | This filing: Other operating expenses for fiscal 2024 and 2023 are [n] and [n] | Document | Form 10-K 2025, page 55 |
| 2 | New separate line carrying [n] (fiscal 2024) and [n] (fiscal 2023) | Document | Form 10-K 2025, page 55 |
| 3 | Prior-year Form 10-K as published: [n] and [n], with no separate (gain) loss line | Document | Form 10-K 2024 (prior year), page 55 |
| 4 | MD&A discusses the fiscal 2024 net loss on disposition (management's side) | Document | Form 10-K 2025, page 32 |
| 5 | Prior-year segment note said these gains and losses sat within other items (management's side) | Document | Form 10-K 2024 (prior year), page 83 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- 1. Description of Business and Summary of Significant Accounting Policies
- What is missing
- a statement that prior-year amounts were reclassified to show (gain) loss on disposition separately
- Pages looked at
- p.54-62 (statements and Note 1), p.32 (MD&A operating income discussion)
- Result
- 'reclassif' hits p.56 (interest-rate swap reclassification adjustment in other comprehensive income) and p.61 ([brand] tradename reclassified to definite-lived): neither concerns the expense line; 'conform to the current' hits p.49 and p.64, both about the income-tax disclosure recast on adopting ASU 2023-09; 'previously reported' and 'prior year amounts' have no hits.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.