1.09 Federal tax credit carryforwards rose to [amount], but the note gives no expiry dates for them
Company A · a US-listed consumer leisure company · SEC-style question
In brief
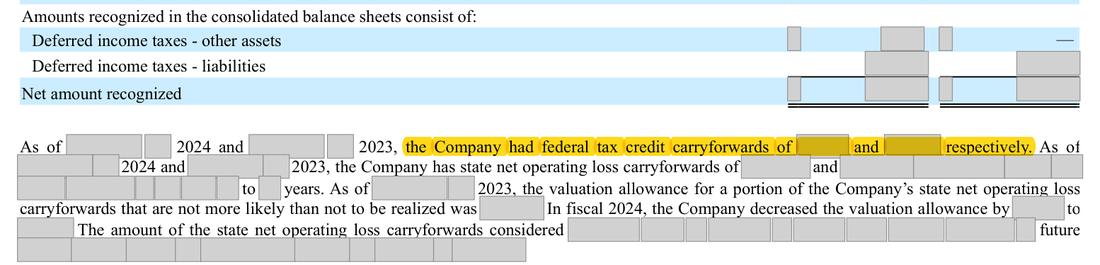
The income-tax note gives federal tax credit carryforwards of [amount] (up from [amount]) after [amount] of federal tax credits generated in fiscal 2025. It states when the state net operating losses expire but says nothing about when the federal credits expire. The prior-year note gave the credit amounts without expiry dates as well.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Amounts of federal and state tax credit carryforwards at both dates; expiry stated only for state net operating losses. | The amounts and expiration dates (or ranges) of the federal and state tax credit carryforwards. |
| What we checked. Note 9 (deferred taxes, carryforwards, valuation allowance, rate reconciliation), Note 1 income-tax policy, and the prior-year Form 10-K. | |
Why it matters
Readers cannot see whether any of the federal credits, which carry no valuation allowance, are close to expiry; the state credits carry a valuation allowance of [amount] and are under a [date] contract of sale.
Exposure
None on its own; a possible staff question if the credits continue to grow.
Our workings
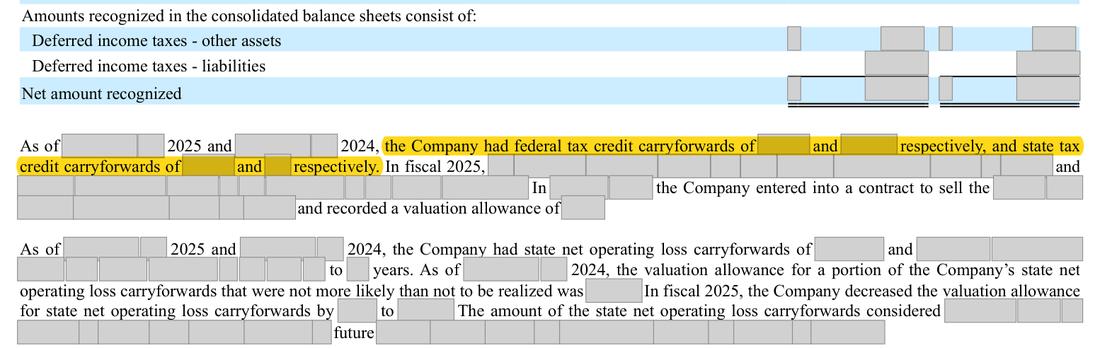
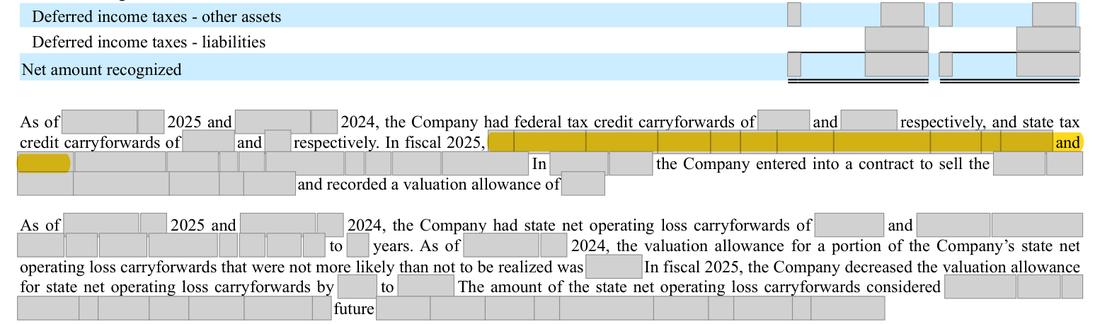
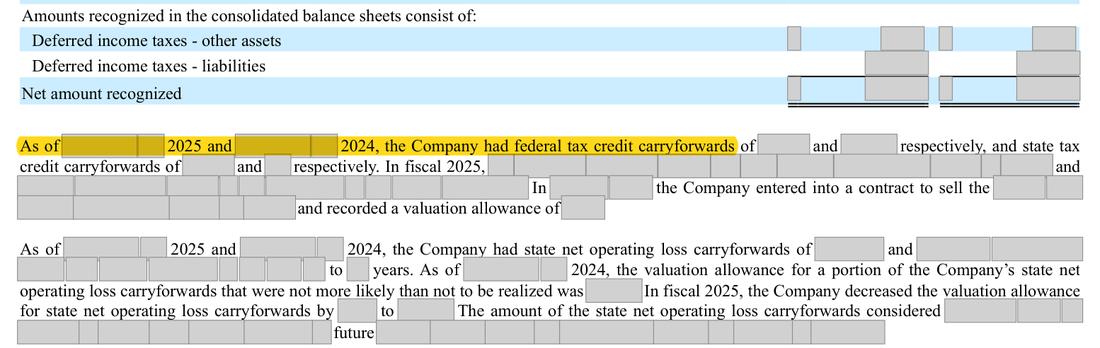
the note states federal tax credit carryforwards of [amounts] and state tax credit carryforwards of [amount] and nil at the two dates, and that fiscal 2025 generated tax credits of [amounts]. For state net operating losses it adds that they 'will expire primarily in the next [n] to 20 years'; for the credits there is no expiry information.
the federal credits grew by [n] ([n] - [n]) and equal 104.1% of pre-tax income ([n] / [n]).
Accounting Standards Codification (ASC) paragraph 740-10-50-3(a) asks for the amounts and expiration dates of tax credit carryforwards. Federal general business credits normally carry forward for 20 years, so the dates may be distant, and the state credits are under a [date] contract of sale; but whether any older credits expire soon matters to the decision not to record a valuation allowance against them, and only management can give the dates.
| Measure | Working | Result |
|---|---|---|
| Growth in federal credit carryforwards | [n] - [n] = [n] | [n] |
| Federal credit carryforwards against pre-tax income | [n] / [n] = 104.1% | 104.1% |
Management’s best defense, and our reply
Management can argue that the federal credits are general business credits with a 20-year carryforward, most generated in fiscal 2025, so expiry is remote and not material to the valuation allowance judgment. It can add that the state credits were contracted for sale in [date], so their expiry is irrelevant. That is a tenable materiality view, which is why the point is put as a question: the codification asks for expiry dates, and the note does not let a reader confirm that none of the older credits is near expiry.
The fix
- Add: 'The federal tax credit carryforwards expire between [year] and [year]; the state credits are subject to a [date] contract of sale.'
Question for the company
When do the federal tax credit carryforwards of [amount] (and the state credits of [amount]) expire, and are any due to expire within the next five years?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Credit carryforward amounts given, with no expiry | Document | Form 10-K 2025, page 78 |
| 2 | Source of the increase in fiscal 2025 | Document | Form 10-K 2025, page 78 |
| 3 | Expiry given for state net operating losses only | Document | Form 10-K 2025, page 78 |
| 4 | Pre-tax income, the denominator of the 104.1% working | Document | Form 10-K 2025, page 55 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- As of [date] and [date], the Company had federal tax credit carryforwards
- What is missing
- the expiration dates of the federal and state tax credit carryforwards
- Pages looked at
- p.78-80 (Note 9), p.62 (income-tax policy) - images
- Result
- 'expire' hits p.10 (labor agreements), p.21 (property leases), p.72 (stock options) and p.78, where it refers only to state net operating losses. 'expiration' hits p.24 (share repurchase authorization). 'credit carryforward' hits p.78 only, the amount sentences without dates. 'carryforward period' hits p.78, the general sentence on realizability of state losses.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.