1.03 Goodwill note gives no amount by reportable segment and no gross amount or accumulated impairment losses
Company A · a US-listed consumer leisure company · Compliance or disclosure gap
In brief
The balance sheet and Note 1 give one goodwill figure, [amount] at both dates, and Note 1 says each reporting unit is an operating segment. The notes never state the goodwill carried by each of the two reportable segments, or the gross amount and accumulated impairment losses, in either Form 10-K. Only the critical accounting estimates in the management's discussion and analysis (MD&A) say that 'primarily all' goodwill relates to the venue segment, with no amount.
The evidence, as filed
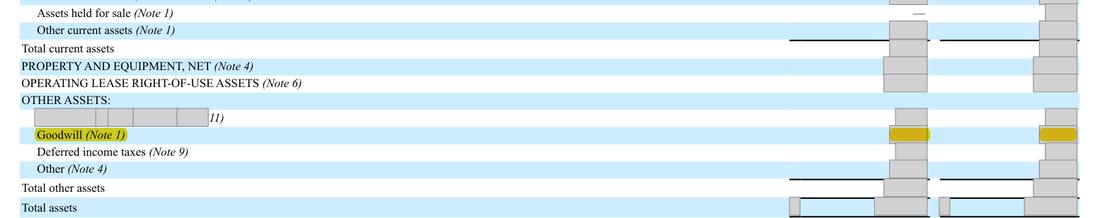
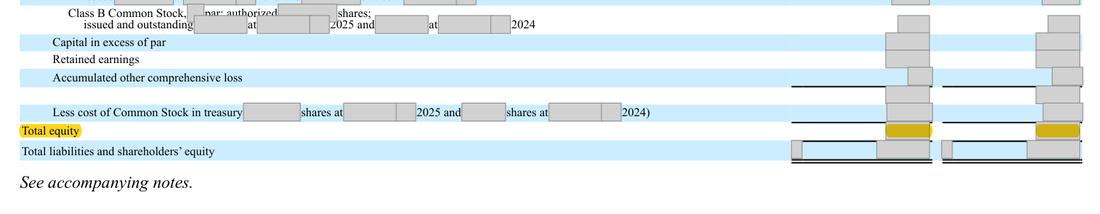
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
One net goodwill balance of [amount] in Note 1, with no amount by segment, no gross amount and no accumulated impairment losses, in both Forms 10-K; the MD&A says only that 'Primarily all of our goodwill relates to our venue segment'. | For each balance-sheet year, goodwill in total and for each reportable segment: gross amount and accumulated impairment losses at the start and end of the year and any changes (a one-line statement suffices where nothing moved). |
| What we checked. Note 1 goodwill and trade-name paragraphs, Note 3 impairment, Note 12 segment tables (three years), the critical accounting estimates in MD&A, the balance sheet, and the prior-year Form 10-K. | |
The rule
FASB ASC 350-20-50-1 to 50-2 (goodwill changes, by reportable segment)
Summary; FASB/IFRS text is copyrighted Impairment equals carrying amount exceeding reporting unit fair value, capped at goodwill; disclose goodwill changes by segment and impairment circumstances, amount and valuation method.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 350-20-50-1 to 50-2 (as amended by ASU 2017-04), paraphrased
Regulation S-X Rule 4-01(a)(1)
Financial statements filed with the Commission which are not prepared in accordance with generally accepted accounting principles will be presumed to be misleading or inaccurate, despite footnote or other disclosures
Version: Text in force at the date of this review · Source: 17 CFR 210.4-01(a)(1), Regulation S-X (eCFR text in force for fiscal 2024 and 2025)
Why it applies here. Accounting Standards Codification (ASC) paragraph 350-20-50-1 requires, for each period for which a balance sheet is presented, the gross amount and accumulated impairment losses at the beginning and end of the period and the changes in between, in total and for each reportable segment where the entity reports segment information. The requirement applies to the audited notes and is not switched off when the balance does not move. The MD&A sentence tells the reader where most of the goodwill sits, so the practical gap is narrow, which is why the point is rated low; but the sentence is qualitative ('primarily all' leaves an unquantified balance elsewhere), sits outside the audited statements and says nothing about accumulated impairment losses. Goodwill and impairment are among the most frequent Securities and Exchange Commission (SEC) staff comment themes.
Why it matters
The audited notes do not show how the [amount] is split between the two reportable segments, or whether any accumulated impairment losses exist; a reader must rely on a qualitative MD&A sentence. The note falls short of the codification requirement in both years, although the practical information gap is narrow.
Exposure
An SEC staff comment letter asking for the segment allocation, answered by an undertaking to add it in future filings; no amount changes.
Our workings
the balance sheet carries goodwill of [amount] at both dates and Note 1 repeats that figure; Note 1 says goodwill is tested at the reporting-unit level, determined to be the operating segment, and that a quantitative test was run as of [date]. The company reports two segments, venues and Lodging. The critical accounting estimates in the MD&A (p.48) say that primarily all goodwill relates to the venue segment and that the fair value of the venue reporting unit exceeded its carrying value by a substantial amount; neither the notes nor the MD&A give the amount held by each segment, the gross amount or any accumulated impairment losses.
goodwill is [n]% of total equity ([n] / [n]).
| Measure | Figure | Working |
|---|---|---|
| Goodwill as a share of total equity, [date] | [n]% | [n] / [n] = [n]% |
| Requirement | Status | Where |
|---|---|---|
| Gross amount of goodwill, beginning and end of year | Absent | Note 1 gives only the net balance |
| Accumulated impairment losses, beginning and end of year | Absent | nowhere |
| Additions, disposals, impairment losses, other changes | Given (nil) | Note 1: no impairment indicated |
| The above by reportable segment | Absent from the notes | MD&A p.48: 'primarily all' Venue, no amount |
Management’s best defense, and our reply
Management would say the MD&A already tells readers that primarily all goodwill relates to the venue segment and that the venue reporting unit passed its annual test by a substantial margin, and that the balance did not move in either year, so a segment roll-forward would repeat one figure. It would add that the staff's 2026 review of this Form 10-K raised no goodwill comment. That narrows the point to a low-severity one, but it does not meet the requirement: the paragraph asks for amounts by reportable segment, and for the gross amount and accumulated impairment losses, in the notes to the audited statements; 'primarily all' is not an amount, and an MD&A sentence is not part of the audited statements.
The fix
- Add to Note 1: 'Goodwill of [amount] is assigned to the [venues / lodging properties] segment; there were no changes in its carrying amount in fiscal 2025 or 2024 and accumulated impairment losses were $[x] at each date' (or a roll-forward table by segment).
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Balance sheet: goodwill unchanged at both dates, referred to Note 1 | Document | Form 10-K 2025, page 54 |
| 2 | Total equity, the denominator of the [n]% working | Document | Form 10-K 2025, page 54 |
| 3 | Reporting units are the operating segments, yet the notes name no segment | Document | Form 10-K 2025, page 61 |
| 4 | The only goodwill disclosure in the notes: one net figure, no segment, no gross amount or accumulated impairment | Document | Form 10-K 2025, page 61 |
| 5 | Two reportable segments, so the segment-level goodwill information applies | Document | Form 10-K 2025, page 82 |
| 6 | The only statement of where the goodwill sits: in the MD&A, qualitative, with no amount | Document | Form 10-K 2025, page 48 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Goodwill - The Company reviews goodwill
- What is missing
- the goodwill carried by each reportable segment, and the gross amount and accumulated impairment losses at the start and end of each year
- Pages looked at
- p.61-62 (Note 1), p.66-67 (Note 3), p.82-84 (Note 12), p.48 (critical accounting estimates), p.51-52 (auditor's report), p.54 (balance sheet) - images
- Result
- 'accumulated impairment' and 'goodwill by' have no hit. 'allocated to' hits p.66 (transaction price allocated to performance obligations) and p.84 (corporate costs allocated to segments), neither about goodwill. 'reporting unit' hits p.48 and [n], the policy text on how the test is run, giving no amount by unit. 'Venue segment' hits p.48, the MD&A sentence that primarily all goodwill relates to the venue segment (qualitative, no amount, outside the notes), and in the plural p.51-52, the auditor's critical audit matter on venue long-lived assets, not goodwill.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.