2.01 The 2024 highest paid director figure of [amount] leaves out a director's [amount] gain on exercising share options, which the regulations count; on their measure it is at least [amount] (2024 report, and the 2024 comparative in the 2025 report)
UK Company C · an AIM-quoted scientific instruments group · Compliance or disclosure gap
In brief
As a company traded on AIM, the Company must show in the notes to its accounts the gains directors make on exercising share options, and the highest paid director's share of pay plus such gains. The 2024 Remuneration Committee report says one director exercised options in 2024 with a gain of [amount], more than double the 2024 pay of any director (the largest total was [amount]. The audited note [n] in the 2024 report, repeated as the comparative in the 2025 report, shows directors' emoluments of [amount] and the highest paid director at [amount], with no gain. On the regulations' own definition the highest paid director for 2024 is the director who made the gain, with at least [amount] attributable.
The evidence, as filed
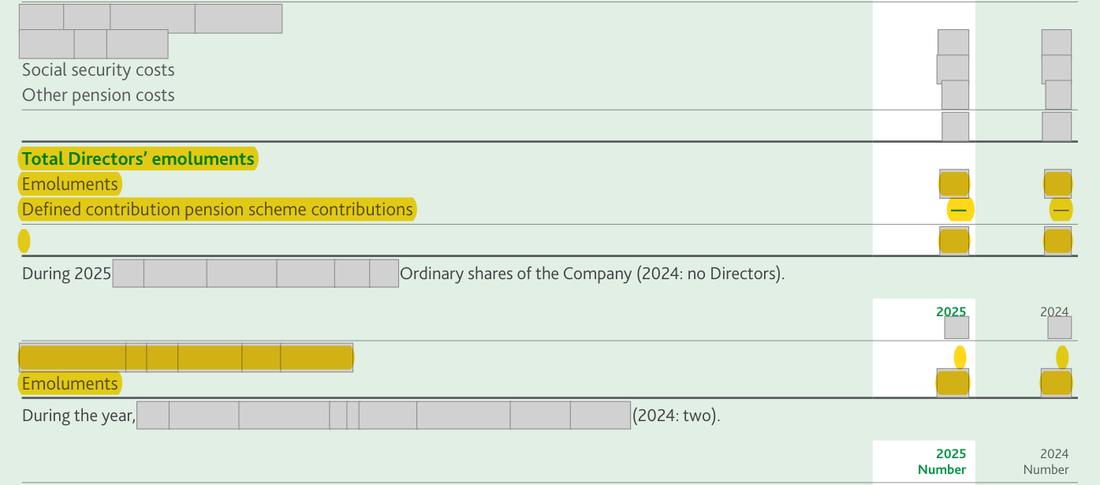
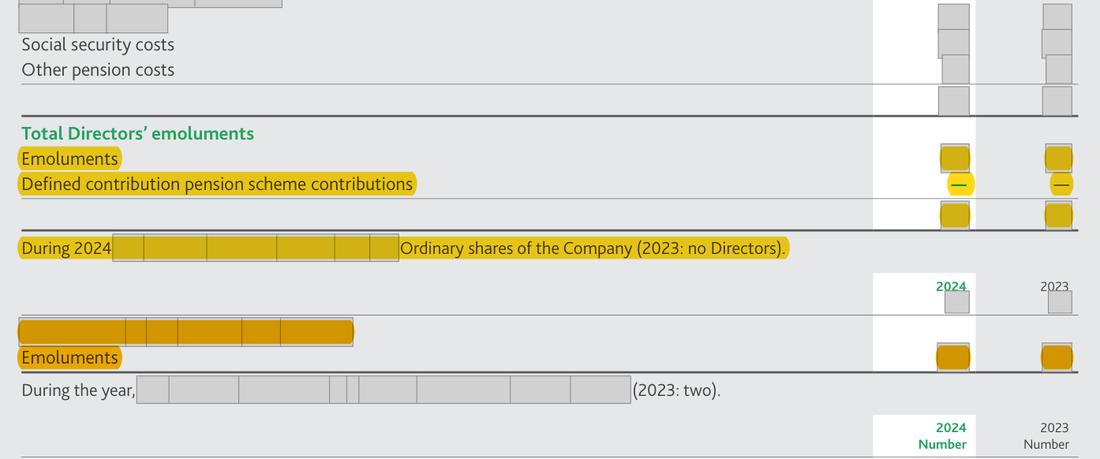
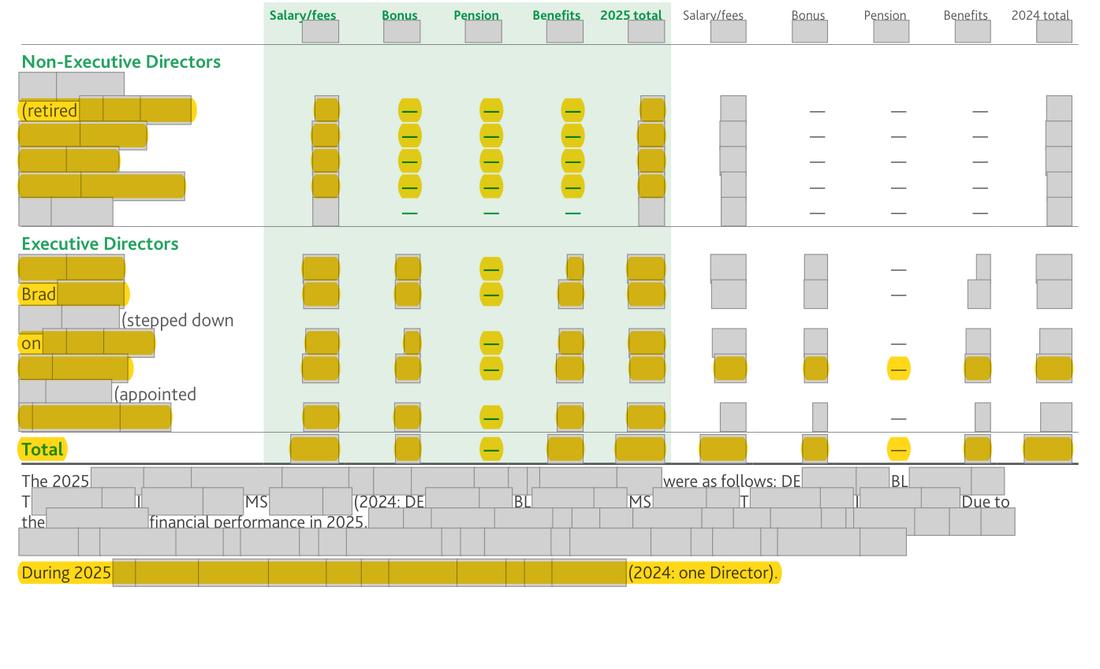
Further pages withheld to protect the company’s identity (one): Annual Report 2024, page 54. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Note 13, 2024 column (both reports): total directors' emoluments [n]; [wording masked] [n]; one director exercised options; no gain on exercise shown. Remuneration Committee report 2024: one director's exercise with a gain of [amount]; the largest 2024 director total was [n] ([amount] | What the rule requires Note 13, 2024: the aggregate gains made by directors on the exercise of share options ([amount] shown, and the highest paid director's figure given as that director's share of remuneration and option gains together, at least [amount], in the 2024 report and as the comparative in the 2025 report |
The rule
SI 2008/410 Schedule 5 paragraph 1(1)(b)
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
the aggregate of the amount of gains made by directors on the exercise of share options
SI 2008/410 Schedule 5 paragraph 1(3)
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
In the case of a company which is not a quoted company and whose equity share capital is not listed on the market known as AIM ... sub-paragraph (1) has effect as if paragraph (b) were omitted
SI 2008/410 Schedule 5 paragraph 2(1)
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
Where the aggregates shown under paragraph 1(1)(a), (b) and (c) total [amount] or more, there must be shown ... so much of the total of those aggregates as is attributable to the highest paid director
SI 2008/410 Schedule 5 paragraph 10
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
means the director to whom is attributable the greatest part of the total of the aggregates shown under paragraph 1(1)(a), (b) and (c)
Companies Act 2006 s.412(1) and (2)(a)
Version relied on: Companies Act 2006, revised text on legislation.gov.uk as in force for the financial year reviewed
The Secretary of State may make provision by regulations requiring information to be given in notes to a company's annual accounts about directors' remuneration.
Why it applies here: Schedule 5 paragraph 1(3) removes the gains disclosure only for a company that is neither quoted nor on AIM, so an AIM company must show the aggregate gains under paragraph 1(1)(b).
Why it matters
- The audited notes say the best-paid director received [amount] for 2024 when, on the measure the regulations require, a different director received at least [amount], and the option gain that makes the difference is missing.
- The 2025 report carries the same comparative, so the correction falls in the Annual Report 2026.
The audited notes tell readers that the best-paid director received [amount] for 2024 when, on the measure the regulations require, a different director received at least [amount], and the option gain that makes the difference is missing from the notes; the 2025 report carries the same comparative.
Exposure
No fine in practice; the realistic consequence is a Financial Reporting Council (FRC) Corporate Reporting Review question and correction of the 2024 comparative in the next report.
Our workings
the 2024 Remuneration Committee report (page 54) states that during 2024 [wording masked] Company's shares with a gain of [amount]; its table gives each director's 2024 total, the largest being [n] ([amount], and a total of [n] ([amount]. The audited parent company note [n] in the 2024 report (page 107) shows total directors' emoluments of [n] (£m) with nil pension contributions, says one director exercised options in 2024, and gives the [wording masked] as [n] (£m); it gives no gain on exercise. The 2025 report's note [n] (page 108) repeats [n] and [n] as the 2024 comparatives, and its remuneration table (page 53) again shows [n] as the largest 2024 total.
[n] exceeds [n] (workings), so whichever director made the gain had at least [n] ([amount] attributable under paragraphs 1(1)(a) and (b) of Schedule 5, against [n] (£m) shown; [n] - [n] = -[n] (£m) at the least.
Paragraph 2(1)(a) then requires the highest paid director's share of the total of paragraphs 1(1)(a), (b) and (c), and paragraph 10 defines the highest paid director by that same total, so option gains decide both who the highest paid director is and the amount. The note shows remuneration only, which identifies the wrong director and understates the amount. The 2025 figures are not affected: the Remuneration Committee report states that no director exercised options in 2025, and the highest 2025 total of [n] ([amount] matches [n] (£m). The note's statement on which year had the exercise is the separate point in [n].
| Step | Figures | Result |
|---|---|---|
| Largest 2024 total of any director (Remuneration Committee report, [amount] | max([n]) = [n] | [n] ([amount] = [amount] |
| 2024 gain on exercise of share options by one director ([amount] | [n] > [n] | the director with the gain is the highest paid director under paragraph 10 |
| Reported, correct (floor), difference (£m) | reported [n]; correct [n]; difference -[n] | [n] - [n] = -[n] |
| Paragraph 1(1)(a) plus (b) for 2024 ([amount] | [n] + [n] = [n] | [n] ([amount] >= [n] ([amount] threshold in paragraph 2(1); note [n] shows [n] (£m) |
| Size | [n] / [n] = [n]%; [n] / [n] = 137% | of 2024 profit before tax; of the line |
| 2025 check ([amount] | max([n]) = [n] | [n] ([amount] agrees to [n] (£m); total [n] ([amount] agrees to [n] (£m) |
Management’s best defence, and our reply
The Company could argue that the note's line is labelled emoluments and that 'remuneration' as defined in paragraph 9 of Schedule 5 excludes gains on share options, so [amount] correctly states the highest paid director's emoluments. It could add that the [amount] gain is set out in the Remuneration Committee report within the same annual report, so it is treated as shown under paragraph 6(2), and that the auditor, who reports by exception if directors' remuneration disclosures [wording masked], raised nothing. The answer: paragraph 2(1)(a) does not ask for emoluments; it asks for the highest paid director's share of the total of paragraphs 1(1)(a), (b) and (c), and paragraph 10 picks that director by the same total, so option gains change both the person and the amount. The Remuneration Committee report does not say which director exercised, so the highest paid director's figure cannot be readily worked out from it, and section 412 requires the information in the notes to the accounts, which the Remuneration Committee report is not.
The fix
- In the next report, correct the 2024 comparative in note [n]: show aggregate gains on the exercise of share options of [amount], give the highest paid director's figure as that director's 2024 remuneration plus the gain, and keep the gains line (nil for 2025) in future notes.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | One director made a gain of [amount] on exercising share options in 2024 | Document | Annual Report 2024, page 54 |
| 2 | Largest non-executive total in 2024 (other non-executives [n]) | Document | Annual Report 2024, page 54 |
| 3 | Non-executive 2024 total | Document | Annual Report 2024, page 54 |
| 4 | Non-executive 2024 total | Document | Annual Report 2024, page 54 |
| 5 | Non-executive 2024 total | Document | Annual Report 2024, page 54 |
| 6 | Non-executive 2024 total (appointed [date]) | Document | Annual Report 2024, page 54 |
| 7 | Executive director 2024 total | Document | Annual Report 2024, page 54 |
| 8 | Executive director 2024 total | Document | Annual Report 2024, page 54 |
| 9 | Executive director 2024 total | Document | Annual Report 2024, page 54 |
| 10 | The largest 2024 director total, [n] ([amount] | Document | Annual Report 2024, page 54 |
| 11 | Executive director 2024 total (appointed [date]) | Document | Annual Report 2024, page 54 |
| 12 | Total 2024 directors' remuneration, [n] ([amount] | Document | Annual Report 2024, page 54 |
| 13 | Audited note [n] gives 2024 directors' emoluments of [n] (£m) with no option gains | Document | Annual Report 2024, page 107 |
| 14 | The note records the 2024 exercise but gives no gain | Document | Annual Report 2024, page 107 |
| 15 | Audited note [n] gives the 2024 highest paid director at [n] (£m) | Document | Annual Report 2024, page 107 |
| 16 | The 2025 report repeats [n] (£m) as the 2024 comparative | Document | Annual Report 2025, page 108 |
| 17 | The 2025 report repeats [n] (£m) for 2024 and gives [n] (£m) for 2025 | Document | Annual Report 2025, page 108 |
| 18 | No exercise in 2025, so the 2025 figures need no gain | Document | Annual Report 2025, page 53 |
| 19 | Largest 2025 total [n] ([amount]; 2024 comparative [n] ([amount] | Document | Annual Report 2025, page 53 |
| 20 | Total 2025 directors' remuneration [n] ([amount] | Document | Annual Report 2025, page 53 |
| 21 | Non-executive 2025 total | Document | Annual Report 2025, page 53 |
| 22 | Non-executive 2025 total | Document | Annual Report 2025, page 53 |
| 23 | Non-executive 2025 total | Document | Annual Report 2025, page 53 |
| 24 | Non-executive 2025 total | Document | Annual Report 2025, page 53 |
| 25 | Executive director 2025 total | Document | Annual Report 2025, page 53 |
| 26 | Executive director 2025 total | Document | Annual Report 2025, page 53 |
| 27 | Executive director 2025 total (stepped down [date]) | Document | Annual Report 2025, page 53 |
| 28 | Executive director 2025 total | Document | Annual Report 2025, page 53 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- Total Directors’ emoluments
- What is missing
- the aggregate gains made by directors on the exercise of share options for 2024 ([amount] and their inclusion in the highest paid director's figure
- Pages looked at
- p.108 (parent company note [n]), p.52-55 (Remuneration Committee report); Annual Report [amount].107 and p.52-55
- Result
- Annual Report 2025: 'gains made', 'with a gain' and '[n]' have no hits; 'exercise of share options' hits p.20 and [n] (shares issued to staff on option exercises) and p.74 (tax treatment policy), none of them directors' gains; 'gain' hits p.55 (a director's gain of [amount] on an exercise on [date], after the year end), p.65, [n] and [n] (pension actuarial gains) and p.90 (hedging gains or losses). The [amount] gain appears only in the 2024 Remuneration Committee report (Annual Report [amount].54), outside the notes to the accounts.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.