3.01 Key management pay note counts share awards as short-term employee benefits
UK Company C · an AIM-quoted scientific instruments group · Compliance or disclosure gap
In brief
Note 7 lists share-based payments of [amount] under the heading 'Short-term employee benefits' and adds them into a subtotal 'Total short-term employee benefits' of [amount]. IAS 24 makes share-based payment a separate category, so short-term benefits should read [amount] with [amount] of share-based payment shown on its own. The total of [amount] is right; only the split is wrong. The 2025 report repeats the layout ([amount] inside a [amount] subtotal).
The evidence, as filed
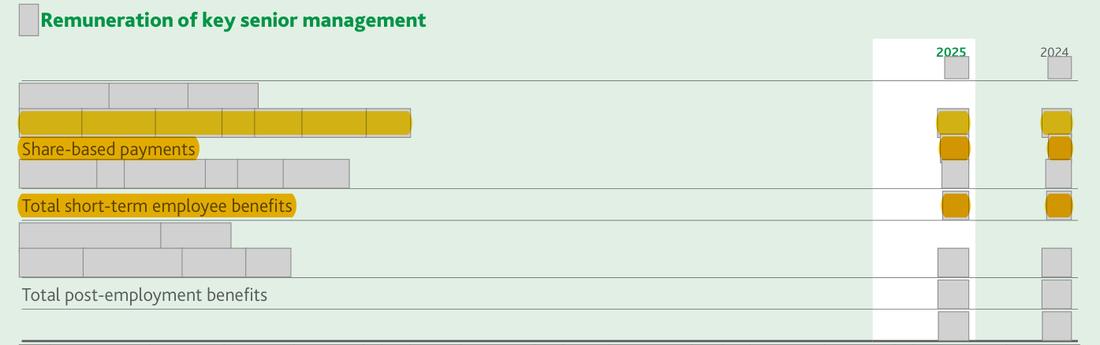
Further pages withheld to protect the company’s identity (one): Annual Report 2024, page 78. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Short-term employee benefits subtotal [amount], including share-based payments [amount] (2025 report: [amount] including [amount]) | What the rule requires Short-term employee benefits [amount]; post-employment benefits [amount]; share-based payment [amount] as its own category; total [amount] |
What we checked: Note 7 table on the page image in both reports; IAS 24 paragraphs 9 and 17; employee costs in note 6
The rule
IAS 24 Related Party Disclosures, paragraph 17
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
Key management personnel compensation must be disclosed in total and split into short-term benefits, post-employment benefits, other long-term benefits, termination benefits and share-based payment.
IAS 24 Related Party Disclosures, paragraph 9 (definition of compensation)
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
Compensation for this purpose includes all employee benefits, including share-based payments.
Why it applies here: IAS 24 paragraph 9 lists short-term employee benefits (wages, salaries, social security, bonuses payable within twelve months, non-monetary benefits) and share-based payment as separate kinds of compensation, and paragraph 17 requires key management personnel compensation in total and for each category.
Why it matters
- The category split IAS 24 requires is misstated in both years, and comparisons with the Remuneration Committee report are distorted.
The category split that IAS 24 requires is misstated in both years: a reader cannot take the short-term pay of key management from the note without noticing that [amount] (2025: [amount]) of share awards sits inside it, and comparisons with the remuneration report are distorted.
Exposure
A disclosure point of the kind the Financial Reporting Council's Corporate Reporting Review raises in a letter, usually closed by an undertaking to correct the next report; no fine applies.
Our workings
the note 7 table for 2024 prints, under the heading '[wording masked] [amount], share-based payments [amount] and [wording masked] [amount], then 'Total short-term employee benefits [amount]', post-employment benefits [amount] and a total of [amount]. The 2025 report prints the same structure (share-based payments [amount], subtotal [amount]).
short-term benefits on the IAS 24 definition are [n] + [n] = [n], so the printed subtotal is higher by [n] - [n] = [n], the share-based payment line; the total [n] + [n] + [n] = [n] agrees to the note.
Share awards under the company's schemes vest over a period and are measured under IFRS 2, outside the short-term definition, so the printed category figure is not the IAS 24 short-term figure.
| Item (2024, £m) | Figure | IAS 24.17 category |
|---|---|---|
| [wording masked] | [n] | (a) short-term |
| [wording masked] | [n] | (a) short-term |
| Short-term employee benefits on the IAS 24 basis | [n] + [n] = [n] | (a) |
| Printed subtotal less correct figure | [n] - [n] = [n] | share-based payments inside (a) |
| Total compensation check | [n] + [n] + [n] = [n] | agrees to the note total |
| 2025 report: correct short-term figure | [n] + [n] = [n]; [n] - [n] = [n] | same pattern |
| Size against profit before tax | [n] / [n] = [n]% | of 2024 PBT |
| Size against the line | [n] / [n] = [n]% | of the printed subtotal |
Management’s best defence, and our reply
The finance team would say the share-based payment amount is printed on its own line, so every IAS 24 category can be read from the table, and the total of [amount] is correct. They might add that the grouping is long-standing and that no user has been misled about total key management pay. The answer: IAS 24 paragraph 17 asks for each category, and the note prints a figure labelled 'Total short-term employee benefits' that is not the short-term figure; a correct line under a wrong subtotal still leaves the category figure wrong. Moving one line below the subtotal costs nothing.
The fix
- Show share-based payment as its own category: 'Short-term employee benefits [n]; Post-employment benefits [n]; Share-based payment [n]; Total [n]' (2025: [n] / [n] / [n] / [n]).
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Salaries, bonuses and social security of [amount], the first line under the short-term heading in note 7 | Document | Annual Report 2024, page 78 |
| 2 | Share-based payments of [amount] (2023: [amount]) listed under the short-term employee benefits heading | Document | Annual Report 2024, page 78 |
| 3 | Other benefits of [amount], a genuine short-term item | Document | Annual Report 2024, page 78 |
| 4 | The subtotal labelled short-term benefits of [amount] includes the share-based payments | Document | Annual Report 2024, page 78 |
| 5 | Post-employment benefits [amount] and total compensation [amount] | Document | Annual Report 2024, page 78 |
| 6 | The 2025 report keeps share-based payments ([amount]) under the short-term heading | Document | Annual Report 2025, page 78 |
| 7 | The 2025 subtotal of [amount] again includes share-based payments | Document | Annual Report 2025, page 78 |
| 8 | 2025 salaries line of [amount] used in the 2025 recomputation | Document | Annual Report 2025, page 78 |
| 9 | 2025 key management share-based payments of [n] listed under the short-term employee benefits heading | Document | Annual Report 2025, page 78 |
| 10 | 2025 short-term total of [n] includes the [n] share-based payments, so the short-term category is overstated and share-based payment is not shown as its own category | Document | Annual Report 2025, page 78 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.