1.24 Provisions note: no use or release of the opening warranty provision, and the 2023 balance left in accruals
UK Company C · an AIM-quoted scientific instruments group · Regulator-style question
In brief
Note 21, shown for the first time in 2024, moves warranties from [amount] to [amount] with only 'provisions made' of [amounts] acquired, although warranties typically run for 12 months, so most of the opening [amount] should have been used or released during the year. The 2025 report's table for the next year does show amounts used ([amount]) and released ([amount]). The [amount] of provisions at the start of 2024 was left inside accruals in the 2023 balance sheet column, which shows no provisions line.
The evidence, as filed
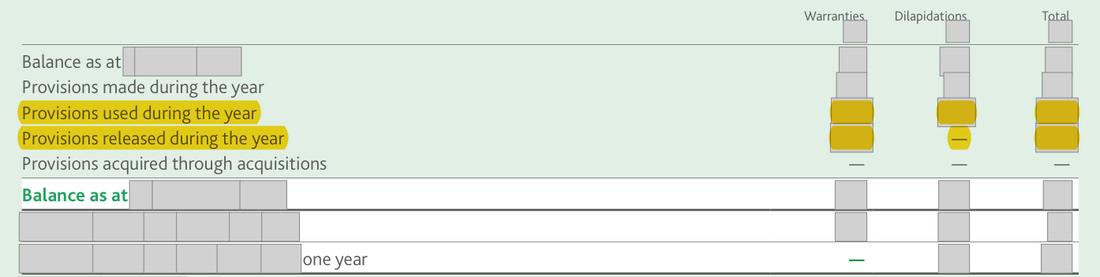
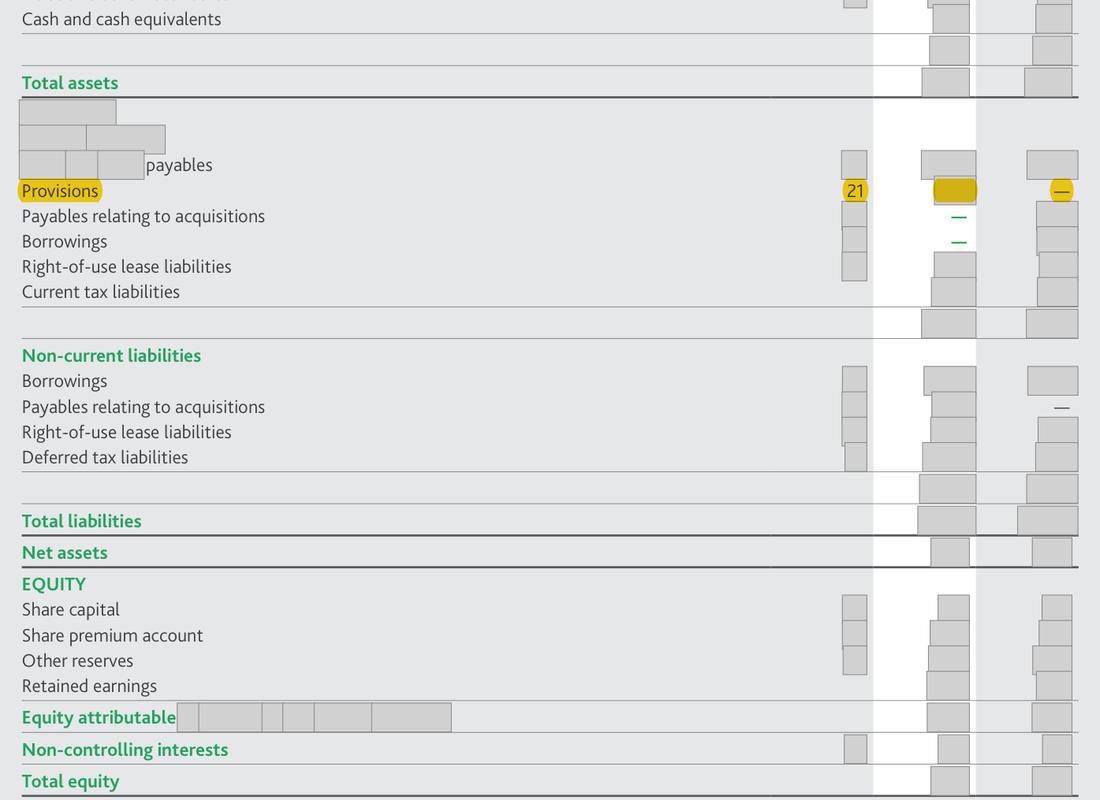
Further pages withheld to protect the company’s identity (one): Annual Report 2024, page 85. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Movement table: opening [amount], made [amount], acquired [amount], closing [amount], with no amounts used or reversed; 2023 balance sheet provisions shown as nil (held within accruals) | What the rule requires For each class: amounts used and unused amounts reversed shown separately from new provisions; the 2023 comparative re-presented (or the reason it was not given) |
What we checked: Note 21, note [n] and the balance sheet on the page images; the 2025 report's note [n]; IAS 37 paragraph 84 and IAS 1 paragraph 41
The rule
IAS 37 Provisions, Contingent Liabilities and Contingent Assets, paragraph 84
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
For each class of provision, the accounts must reconcile the opening and closing carrying amounts, showing additions, amounts used and amounts reversed.
IAS 1 Presentation of Financial Statements, paragraph 41
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
When presentation or classification changes, the comparatives must be reclassified (unless impracticable), with disclosure of what was reclassified, how much and why.
Why it applies here: with 12-month warranties, the [amount] 'made' in 2024 is probably a net figure after use and release of the opening balance;
Why it matters
A reader cannot see how much of the opening warranty provision was consumed or released in 2024, or the size of the new charge, and the 2023 and 2024 balance sheets classify the same kind of liability differently.
Exposure
A question on presentation; amounts are small and no misstatement of the total liability is asserted.
Our workings
note [n] gives, for warranties, an opening balance at [date] of [amount], provisions made of [amount] and provisions acquired of [amount], closing at [amount]; dilapidations move from [amount] to [amount]. A footnote says provisions at [date] were held within accruals, and the 2023 balance sheet column shows provisions as nil. The note says [wording masked] 12-month period. The 2025 report's table, for the following year, shows provisions used of [amount] and released of [amount].
[n] + [n] + [n] = [n], so the table leaves no room for any use or release of the opening warranty balance in 2024; in 2025 the opening warranty balance of [amount] was wholly used or released ([n] + [n] = [n]).
IAS 37 paragraph 84 asks for those components separately. Separately, presenting provisions as a line item for 2024 but leaving the [amount] inside accruals for 2023 is a change of classification without re-presenting the comparative.
| Warranty provision (£m) | Figure |
|---|---|
| Opening at [date] | [n] |
| Provisions made in 2024 | [n] |
| Acquired with subsidiaries | [n] |
| Closing per note | [n] + [n] + [n] = [n] |
| 2025 report: opening warranty balance used and released | [n] + [n] = [n] |
| Opening provisions held in accruals against 2024 PBT | [n] / [n] = [n]% |
Management’s best defence, and our reply
The finance team would say provisions were not material before 2024, so including them in accruals was a permitted aggregation, and that the 2024 table was a first-time analysis where the opening balance was simply carried forward with a net charge. Given the small amounts, an auditor could accept that view under the materiality rules of IAS 1. The answer: IAS 37 asks for the gross components for each class whenever a provision is presented, and the 2025 report shows that the components are available; whether the 2024 figures are net is a matter only management can confirm, so it is put as a question.
The fix
- Show the 2024 movement gross (made, used, released) as the 2025 report does, and re-present the comparative or state why it was not re-presented (for example immateriality).
Question for the company
Was any of the [amount] opening warranty provision used or released during 2024, given 12-month warranty terms, and is the [amount] shown as 'provisions made' a net figure? Why was the [amount] of provisions held within accruals at the end of 2023 not re-presented as provisions in the 2023 balance sheet column?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Opening provisions: warranties [amount], dilapidations [amount], total [amount] | Document | Annual Report 2024, page 85 |
| 2 | The only in-year movement apart from acquisitions is provisions made | Document | Annual Report 2024, page 85 |
| 3 | Warranty provisions of [amount] acquired with subsidiaries | Document | Annual Report 2024, page 85 |
| 4 | Closing provisions of [amount], warranties [amount] | Document | Annual Report 2024, page 85 |
| 5 | The opening [amount] sat inside accruals at the end of 2023 | Document | Annual Report 2024, page 85 |
| 6 | Warranties run about a year, so the opening balance would be used or released within 2024 | Document | Annual Report 2024, page 85 |
| 7 | Balance sheet: provisions [amount] for 2024 and nil for 2023 | Document | Annual Report 2024, page 68 |
| 8 | The following year's table shows amounts used | Document | Annual Report 2025, page 86 |
| 9 | The following year's table shows warranty amounts released of [amount] | Document | Annual Report 2025, page 86 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.