2.04 The year-end options table drops [n] options at [amount] that the same report says were extended and exercised after the year end
UK Company C · an AIM-quoted scientific instruments group · Regulator-style question
In brief
The directors' interests table shows [name] holding [n] options at [date] and lists no option at [amount]. The post balance sheet note on the same page says that on [date] he exercised options over [n] shares at [amount], a gain of [amount], after the Board extended their [date] expiry date. The 2024 report listed those [n] options, and the opening and closing figures only reconcile if they are treated as gone by the year end. The report does not say when the extension was approved, so a reader cannot tell whether the year-end table is incomplete or whether options that had already expired were revived after the year end. The share-based payment note is also silent on the extension: it records no modification of these options.
The evidence, as filed
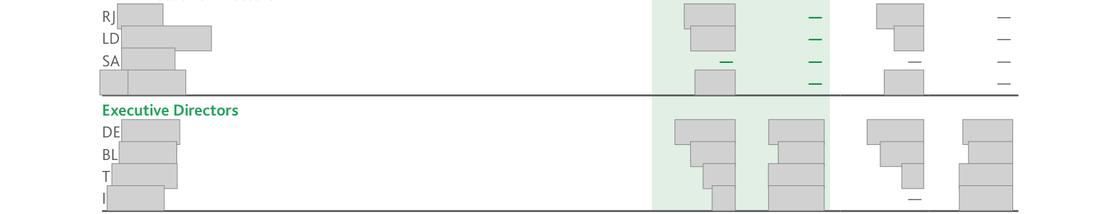
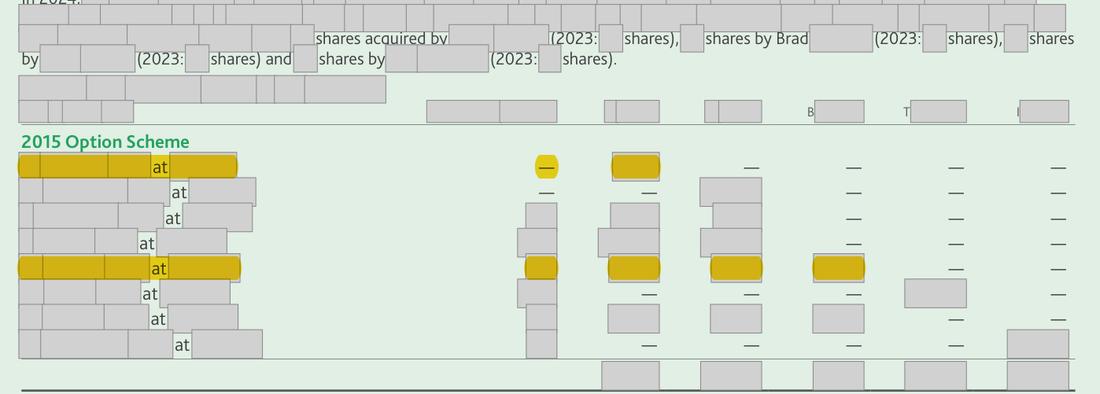
Further pages withheld to protect the company’s identity (two): Annual Report 2025, page 53; Annual Report 2025, page 93. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Options at [date]: [n], with no [amount] line; post balance sheet note: [n] options at [amount] exercised on [date] after an extension of their [date] expiry date; no date given for the extension | What the rule requires A director-by-director options reconciliation (opening, granted, lapsed, exercised, closing) that includes the [n] options at [amount] if they were outstanding at [date], and the date and basis of the Board's extension |
Why it matters
A reader cannot tell whether a director's option holding at the year end is understated by [n] options or whether options that had already expired were revived after the year end and then exercised at a gain of [amount]; either answer bears on how the Board governs share awards to directors.
Exposure
The table is a voluntary disclosure for a company traded on AIM; no statutory sanction attaches. The consequence is one of governance and investor confidence.
Our workings
the 2024 report lists [n] options at [amount] granted on [date] within the [n] options held at [date]. The 2025 table repeats [n] as the [date] holding and shows [n] at [date], with the [amount] line gone; it also says all 2023 options lapsed and that no director exercised options in 2025. The post balance sheet note says the [n] options were exercised on [date] at [amount] for a gain of [amount] and [wording masked] their [date] expiry date because the Board was in a close period.
[n] less the [n] lapsed 2023 options plus the [n] granted in [date] gives [n]; the table shows [n]; the gap is exactly the [n] options at [amount].
The report gives no date for the extension, so the point is put as a question.
| Item | Options (number) or amount | Source |
|---|---|---|
| Options held at [date] | [n] | p.55; Annual Report [amount].55 |
| of which [date] grant at [amount] | [n] | Annual Report [amount].55 |
| of which [date] grant (lapsed in 2025) | [n] | Annual Report [amount].55; p.55 |
| Granted [date] at [amount] | [n] | p.55 |
| Expected holding if the [amount] options were still held: [n] - [n] + [n] | [n] | computed |
| Holding shown at [date] | [n] | p.55 |
| Gap: [n] - [n] | [n] | equals the [amount] options exercised on [date] |
| Gain on exercise in GBP million: [n] / [n] | [n] | p.55 |
Management’s best defence, and our reply
The Company could argue that the table is a voluntary disclosure for an AIM company, that the options passed their contractual expiry on [date] so nil at [date] reflects their position until the Board formally extended them in [date], and that the post balance sheet note then gives full disclosure including the gain. It could add that the amount is small for the Group. However, the note calls the Board's decision an extension to the expiry date, which presupposes options still alive, it gives no date for that decision, and nothing in the report explains why [n] options leave the table in a year with no exercise. A reasonable preparer could hold either reading, so the point is put as a question rather than as a finding.
The fix
- Add a reconciliation of each director's options (opening, granted, lapsed, exercised, closing), state the date on which the Board approved the extension, and include the [n] options at [amount] in the year-end holding if they were outstanding at [date].
Question for the company
When did the Board approve the extension of the [date] expiry date of the [n] options at [amount], and were those options outstanding at [date]? If they were, why does the year-end table omit them; if they had lapsed before the extension, was the extension treated as a new award, and how was it approved and accounted for?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Options held: [n] at [date] and [n] at [date] | Document | Annual Report 2025, page 55 |
| 2 | The 2023 grant ([n] options) lapsed in the year | Document | Annual Report 2025, page 55 |
| 3 | [n] options granted in [date]; no [amount] line in the year-end options table | Document | Annual Report 2025, page 55 |
| 4 | [n] options at [amount] exercised after the year end | Document | Annual Report 2025, page 55 |
| 5 | Extension of the expiry date; no date of approval given | Document | Annual Report 2025, page 55 |
| 6 | No exercise in 2025, so the [n] options did not leave the table by exercise | Document | Annual Report 2025, page 53 |
| 7 | The 2024 report lists the [n] options at [amount] within the [n] total | Document | Annual Report 2024, page 55 |
| 8 | The 2023 grant of [n] options that lapsed in 2025 | Document | Annual Report 2024, page 55 |
| 9 | The remuneration report records an extension of the options' expiry | Document | Annual Report 2025, page 55 |
| 10 | Note 26 movement table: no line or note for options whose terms were extended | Document | Annual Report 2025, page 93 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- [n]. Share-based payments
- What is missing
- any statement that option terms were modified (expiry extended), whether the extended options were outstanding at [date], and the incremental fair value recognised
- Pages looked at
- p.92-93 (notes 25-26), p.73-75 (accounting policies), p.108 (parent note [n])
- Result
- 'extension' hits p.55 (the remuneration report sentence) and p.92 (extension of the bank facility); 'expiry' hits only p.55; 'modification' hits p.60 (climate premises) and p.73 (lease modifications); 'modified' has no hit.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.