1.11 Parent deferred tax note charges [amount] to equity; the parent statement of changes in equity shows [amount]
UK Company C · an AIM-quoted scientific instruments group · Presentation point
In brief
The parent's deferred tax note moves the asset from [amount] to [amount] through a [amount] credit to profit and a [amount] charge to equity. The parent statement of changes in equity shows only [amount] of [wording masked] charged to equity, which is also the figure in the group's deferred tax note. Both cannot be right: on the equity statement's figure, the movement through profit is a [amount] charge, not a [amount] credit.
The evidence, as filed
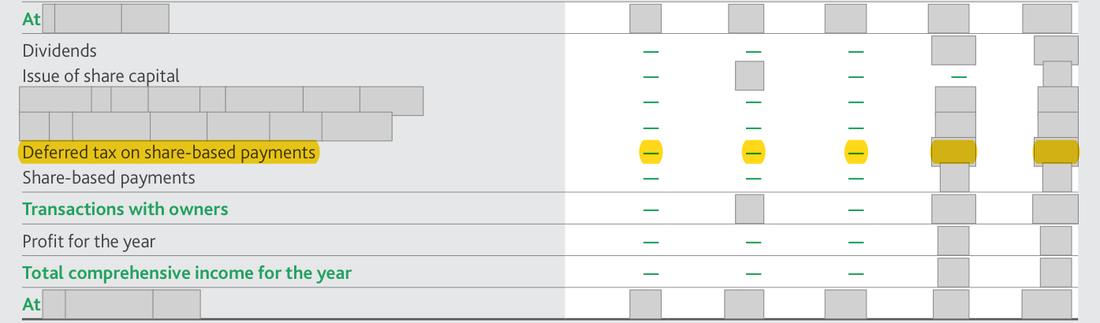
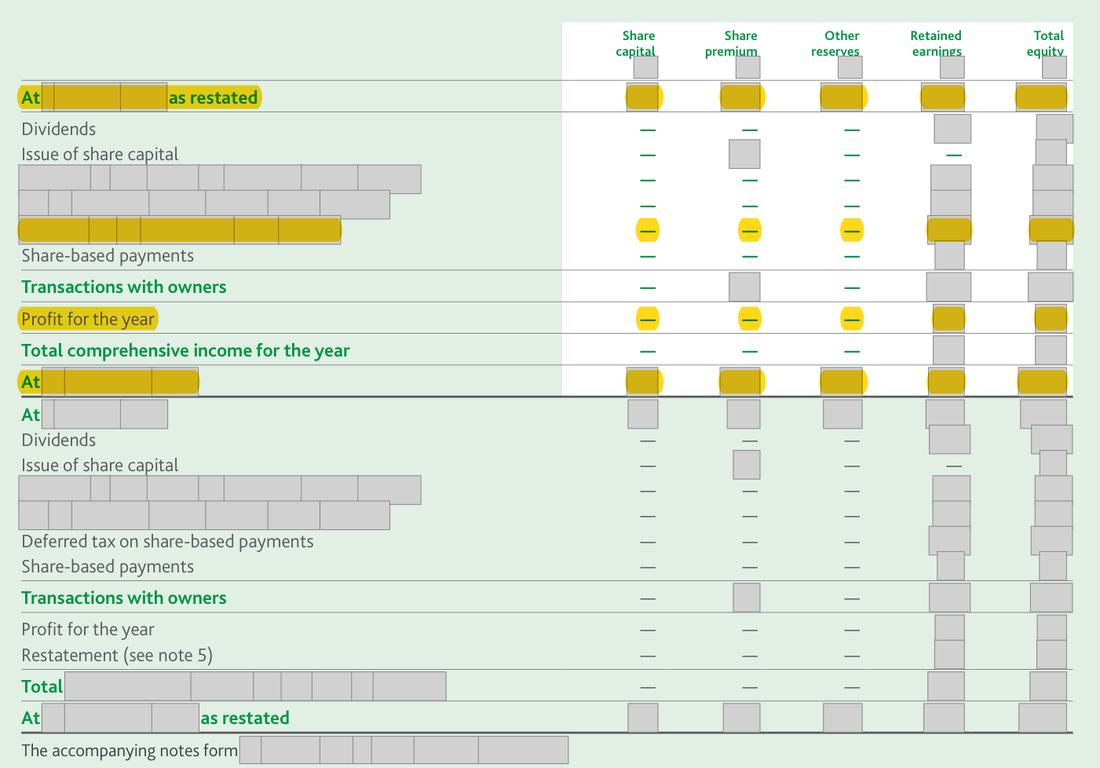
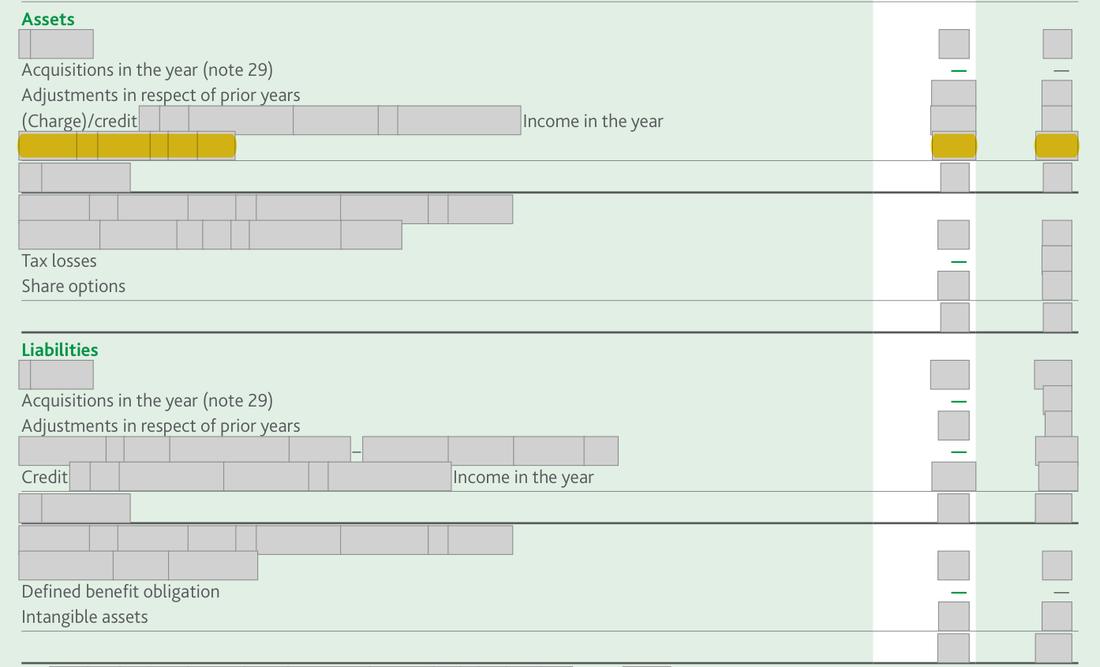
Further pages withheld to protect the company’s identity (one): Annual Report 2025, page 107. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Note 10: 1 [date].7, credit to income [n], charge to equity ([n]), [n] [date].8. Parent statement of changes in equity: [wording masked] ([n]). | What the rule requires One set of figures in both places; if the equity statement is right, note [n] shows a charge to profit of [n] and a charge to equity of [n]. |
The rule
IAS 12 Income Taxes, paragraph 81(a) (applied by the parent under FRS 101)
Version relied on: FRS 101 / FRS 102, FRC, as amended and in force for the financial year reviewed
The accounts must give the total current and deferred tax on items charged or credited directly to equity.
Why it applies here: note [n]'s split between profit and equity disagrees with the parent's primary statement; which one is right only management can confirm, and on the primary statement's figures the note shows a credit to profit where there was a charge.
Why it matters
Readers cannot tell how much deferred tax went through the parent's profit, and on the primary statement's figures the note presents a [n] charge as a [n] credit, a swing of [n] against a reported parent profit of [n].
Exposure
Inconsistency within the parent company accounts; the closing balance sheet figures agree.
Our workings
parent note [n] shows the deferred tax asset on share options moving from [n] to [n], with a credit of [n] '[wording masked] Income' and a charge to equity of [n]. The parent statement of changes in equity shows [wording masked] of [n] charged to retained earnings, a profit for the year of [n] and closing retained earnings of [n]; the group deferred tax note also charges [n] to equity.
the equity charges differ by [n]; holding the closing asset at [n] and the equity charge at [n], the movement through profit is a [n] charge; holding note [n]'s [n], retained earnings would close at [n] unless profit were [n] higher (workings).
| Test | Figures | Result |
|---|---|---|
| Note 10 roll | [n] + [n] - [n] = [n] | agrees with the debtors note |
| Equity charge: note [n] vs statement of changes in equity | [n] - [n] = [n] | difference |
| Movement through profit implied by the equity statement | [n] - [n] + [n] = -[n] | a charge, not a credit |
| Retained earnings if note [n]'s equity charge applied with reported profit | [n] - [n] - [n] - [n] - [n] + [n] + [n] = [n] | against [n] on the balance sheet |
Management’s best defence, and our reply
The finance team might say note [n] shows the equity movement gross, including amounts released on options exercised and lapsed, while the statement of changes in equity nets them. They would add that the closing asset of [n] agrees with the debtors note, so no balance is affected. However, the statement of changes in equity carries only [n] of deferred tax (and [n] of current tax on reward shares) to equity, no other equity line holds the remaining [n], and the group note charges [n]; a gross presentation would still have to net to the same total, so the two statements cannot both stand.
The fix
- Correct note [n] so that its profit and equity lines agree with the parent statement of changes in equity (on the equity statement's figures: charge to profit [n], charge to equity [n]), and relabel the profit line 'to the profit and loss account' since the parent presents no statement of comprehensive income.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Note 10: credit to profit of [n] | Document | Annual Report 2025, page 107 |
| 2 | Note 10: charge to equity of [n] | Document | Annual Report 2025, page 107 |
| 3 | Closing deferred tax asset [n] | Document | Annual Report 2025, page 107 |
| 4 | Parent statement of changes in equity: [n] charged to equity | Document | Annual Report 2025, page 101 |
| 5 | Opening retained earnings [n] | Document | Annual Report 2025, page 101 |
| 6 | Closing retained earnings [n] after profit of [n] | Document | Annual Report 2025, page 101 |
| 7 | Parent profit for the year [n] | Document | Annual Report 2025, page 101 |
| 8 | Group deferred tax note also charges [n] to equity | Document | Annual Report 2025, page 85 |
| 9 | 2024 parent statement of changes in equity: [amount] deferred tax charged to equity | Document | Annual Report 2024, page 101 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.