2.02 The audited directors' emoluments note says one director exercised options in 2025 and none in 2024; the Remuneration Committee report and the 2024 report say the opposite
UK Company C · an AIM-quoted scientific instruments group · Presentation point
In brief
The note to the parent company accounts on directors' emoluments says that during 2025 one director exercised share options and that none did in 2024. The Remuneration Committee report says no director exercised options in 2025 and one did in 2024, and the 2024 report recorded that 2024 exercise with a gain of [amount]. The note has the two years the wrong way round. The same note, worded as in 2024, says two directors were [wording masked], while it shows no contributions and the remuneration report says executives receive cash in lieu of pension; that sentence needs explaining.
The evidence, as filed
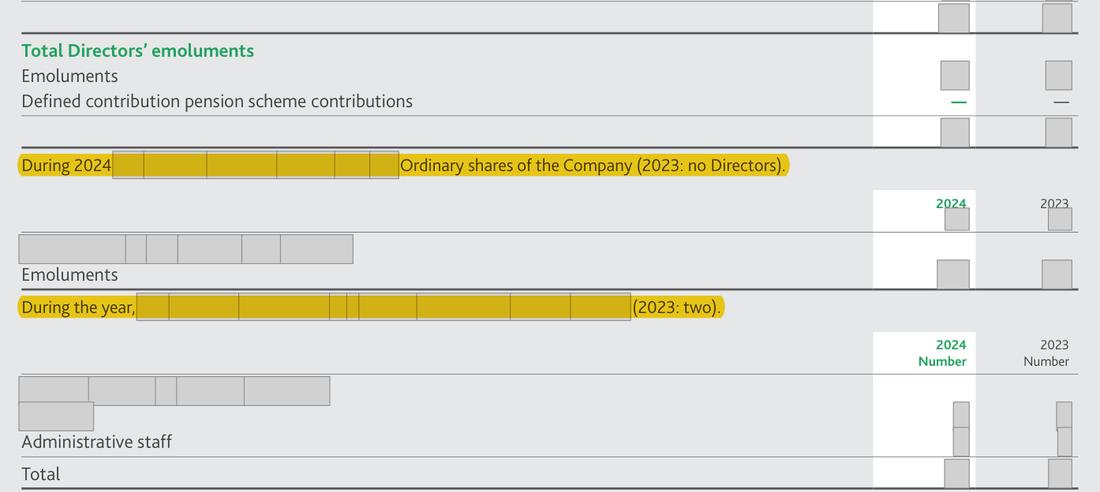
Further pages withheld to protect the company’s identity (five): Annual Report 2025, page 108; Annual Report 2024, page 54; Annual Report 2025, page 53; Annual Report 2025, page 55; Annual Report 2025, page 54. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Note 13: 'During 2025 one Director exercised options ... (2024: no Directors)'; two directors [wording masked] with contributions of nil | What the rule requires Note 13 consistent with the remuneration report and the prior year: no director exercised options in 2025 (2024: one Director), and pension participation stated consistently with nil contributions and payments in lieu |
The rule
Companies Act 2006 s.412(1) and (2)(a)
Version relied on: Companies Act 2006, revised text on legislation.gov.uk as in force for the financial year reviewed
The Secretary of State may make provision by regulations requiring information to be given in notes to a company's annual accounts about directors' remuneration.
Why it applies here: note [n] transposes the current and prior year for option exercises; its pension sentence does not match nil contributions and payments made in lieu unless the two directors are members to whom no contributions were made, which the note does not say.
Why it matters
The audited note on directors' benefits contradicts the remuneration report and the prior year on option exercises, and a reader cannot tell from the note whether any director gained from options in 2025.
Exposure
A transposed comparative in an audited note; the realistic consequence is correction in the next report. No fine attaches to the inconsistency itself.
Our workings
parent company note [n] states that during 2025 [wording masked] Company's shares (2024: no directors), gives defined contribution pension contributions of nil for both years, and says [wording masked] (2024: two). The Remuneration Committee report states that no director exercised options during 2025 (2024: one director), and the post balance sheet section records the next exercise on [date]. The 2024 report's remuneration report recorded one director's exercise in 2024 with a gain of [amount], and its own note [n] said 'During 2024 one Director exercised options' (2023: no Directors), so the 2025 note appears to have rolled the prior sentence forward by changing only the years. The remuneration report also says three executive directors receive 5% of salary in lieu of pension contributions, and its pension column is nil; the 2024 note [n] carried the same 'two Directors' pension sentence against nil contributions.
Section 412 of the Companies Act 2006 provides for notes to the accounts on directors' remuneration, and the matters it lists include gains made by directors on the exercise of share options; note [n] is the parent company's audited note on that subject.
Management’s best defence, and our reply
The company could say the remuneration report is the primary and fuller disclosure, that the note simply carries a typing slip in the year labels, and that nothing turns on it because the option exercise that had been expected in 2025 in fact took place in [date] after the Board extended the expiry date. It could add that the two directors counted as pension scheme participants may hold legacy scheme memberships with no contributions in the year. However, the note forms part of the audited accounts, it states the opposite of the remuneration report and of the 2024 note for both years, and the share option note shows no director exercise in 2025. The pension sentence cannot be squared with nil contributions without an explanation, so that limb is put as a matter to explain rather than an error.
The fix
- Correct note [n] to 'no Director exercised options in 2025 (2024: one Director)', and reword the pension sentence to state how many directors had benefits accruing under a defined contribution scheme and that executives receive payments in lieu of pension contributions.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Note 13: one exercise in 2025, none in 2024 | Document | Annual Report 2025, page 108 |
| 2 | Remuneration report: no exercise in 2025, one in 2024 | Document | Annual Report 2025, page 53 |
| 3 | The 2024 report records the 2024 exercise and its gain | Document | Annual Report 2024, page 54 |
| 4 | The next exercise fell after the 2025 year end | Document | Annual Report 2025, page 55 |
| 5 | Note 13: two directors in a pension scheme | Document | Annual Report 2025, page 108 |
| 6 | Note 13: nil pension contributions in both years | Document | Annual Report 2025, page 108 |
| 7 | Cash in lieu, not scheme contributions | Document | Annual Report 2025, page 54 |
| 8 | The 2024 note [n] recorded the 2024 exercise; the 2025 note reverses it | Document | Annual Report 2024, page 107 |
| 9 | The same pension sentence in 2024, also against nil contributions | Document | Annual Report 2024, page 107 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.