6.06 The pro-forma income statement footnote calls [amount] 'depreciation and amortisation', a figure that includes [amount] of impairment
UK Company B · a UK-listed technology and logistics group · Drafting slip
In brief
Footnote 2 to the pro-forma income statement says [wording masked] [amount] (FY24: [amount]). The Financial Review and the segment note give the same [amounts] as depreciation, amortisation and impairment, including an impairment charge of [amount] (FY24: [amount]).
The evidence, as filed
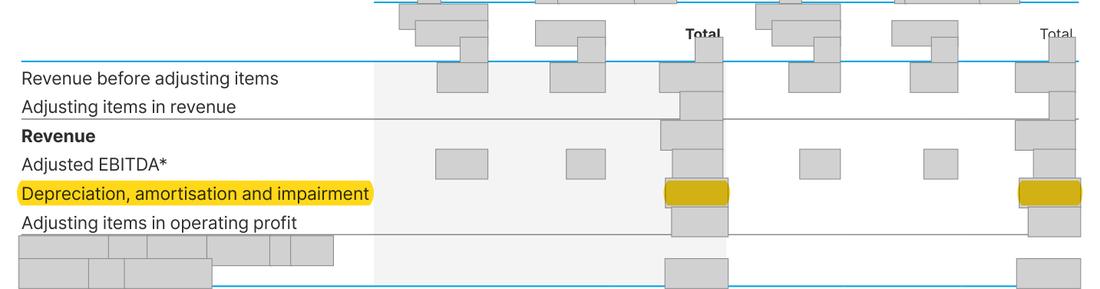
Further pages withheld to protect the company’s identity (two): Annual Report 2025, page 272; Annual Report 2025, page 26. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows p.272 footnote 2: 'depreciation and amortisation of [amount] (FY24: [amount])' | What the rule requires 'depreciation, amortisation and impairment of [amount] (FY24: [amount])', as on p.26 and p.199 |
What we checked: APM pro-forma income statement footnote against the Financial Review and the segment table
Why it matters
No amount is affected; the footnote understates what the figure contains.
Exposure
Drafting only.
Our workings
footnote 2 on p.272 labels [amount] (FY24: [amount]) as depreciation and amortisation. The Financial Review on p.26 gives the same totals as depreciation, amortisation and impairment, made up of depreciation, amortisation and an impairment charge of [amount] (FY24: [amount]), and the segment table on p.199 uses the same caption.
Management’s best defence, and our reply
Management would say the amount is the same as elsewhere and the Financial Review explains its make-up. However, the footnote caption leaves out the impairment the amount includes.
The fix
- Change footnote 2 to 'depreciation, amortisation and impairment of [amount] (FY24: [amount])'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | APM footnote labels the total as depreciation and amortisation only | Document | Annual Report 2025, page 272 |
| 2 | Financial Review gives the same total as depreciation, amortisation and impairment | Document | Annual Report 2025, page 26 |
| 3 | The total includes an impairment charge | Document | Annual Report 2025, page 26 |
| 4 | Segment table uses the full caption for the same amounts | Document | Annual Report 2025, page 199 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.