6.07 Directors' report: the responsibility statement describes all the financial statements as prepared under UK-adopted IFRS, and the Listing Rules index cites the wrong rule for two items
UK Company B · a UK-listed technology and logistics group · Drafting slip
In brief
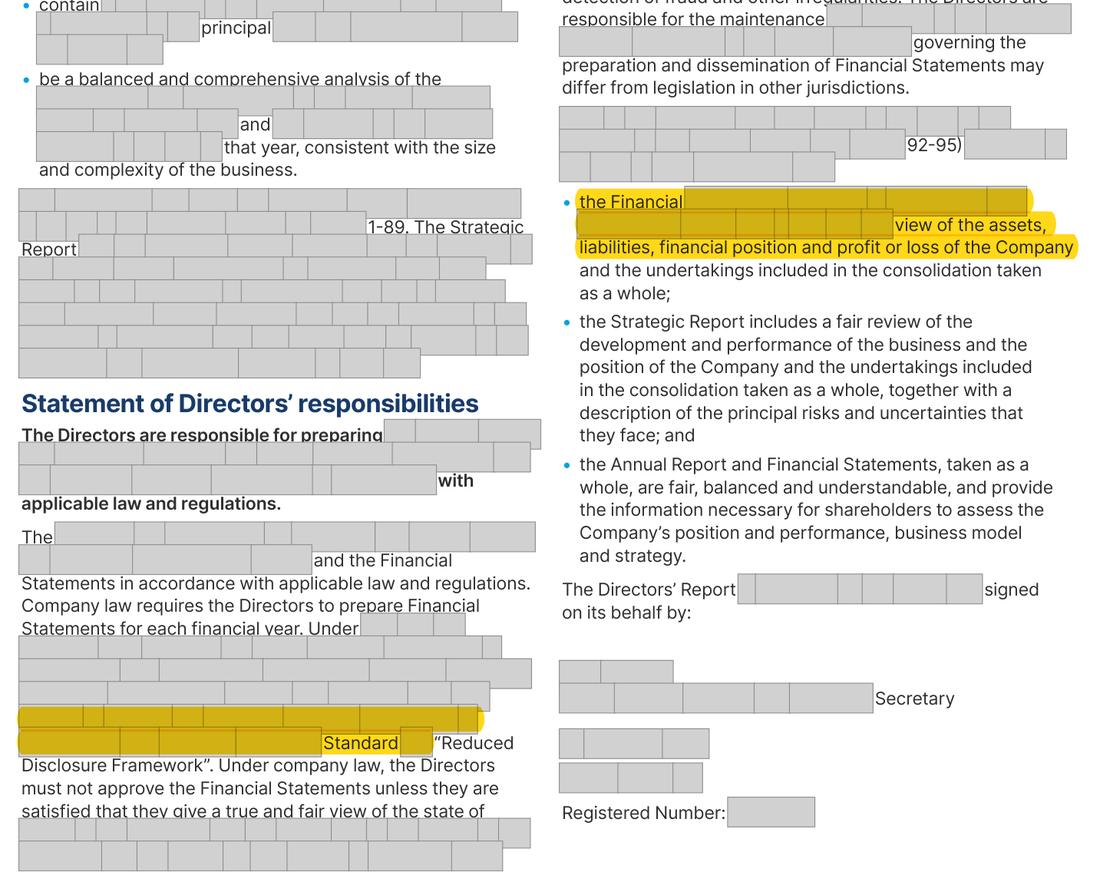
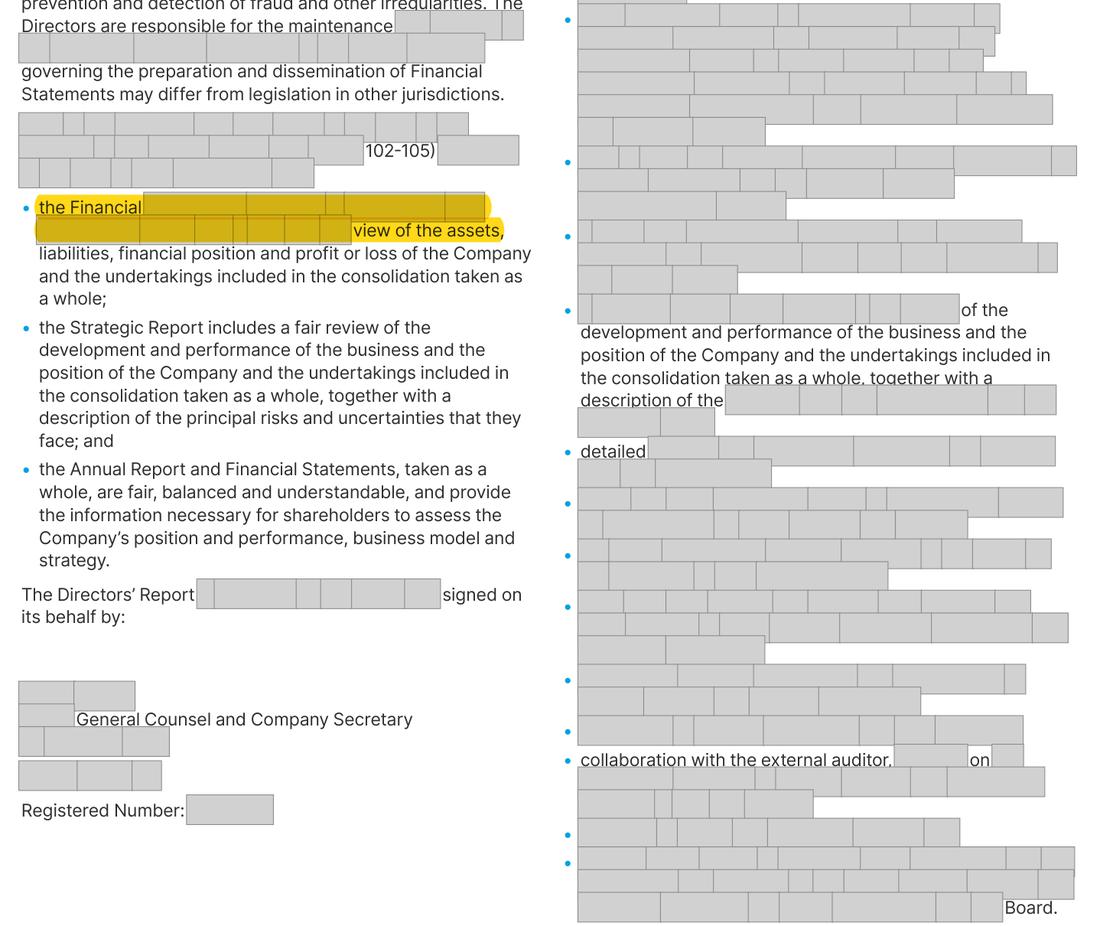
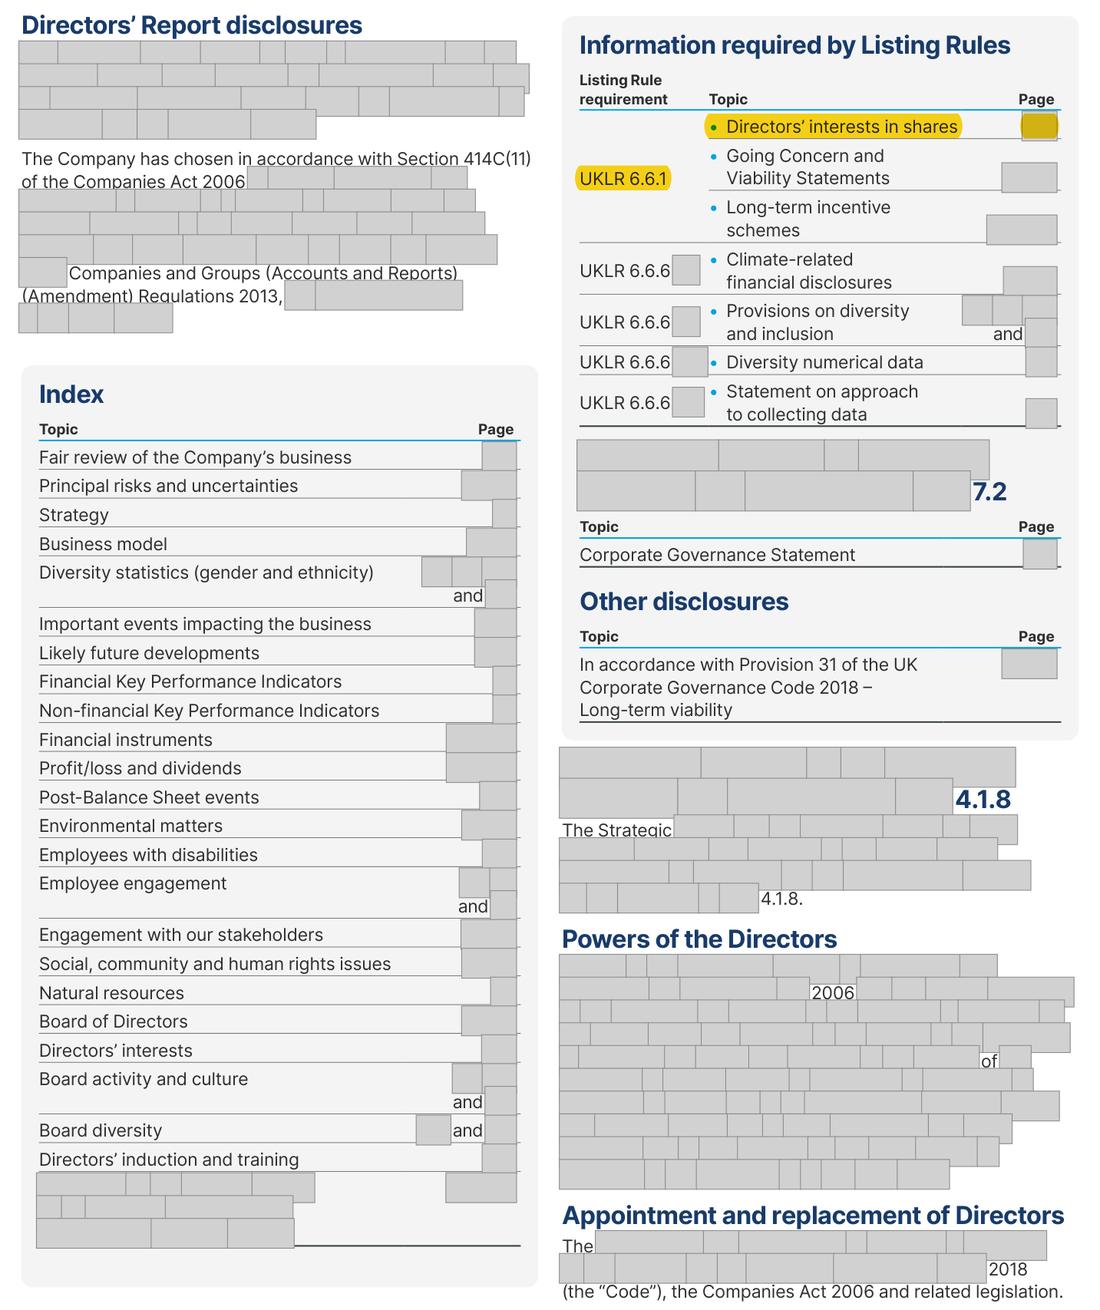
Two slips repeated in both years. The responsibility statement says 'the Financial [wording masked] view, although the same statement of directors' responsibilities says the company financial statements are prepared under FRS 101; the Disclosure Guidance and Transparency Rules (DTR) wording is 'the applicable set of accounting standards'. The Listing Rules index places directors' interests and [wording masked] under UKLR 6.6.1, which deals with other items (such as capitalised interest and long-term incentive schemes); those two items are required by UKLR 6.6.6R(1) and (3).
The evidence, as filed
Further pages withheld to protect the company’s identity (one): Annual Report 2025, page 159. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Responsibility statement: 'the Financial [wording masked] view'; index: directors' interests and going concern / viability shown under UKLR 6.6.1 (2025 report: 'UKLR 6.6.1 (1)' and '(3)'). | What the rule requires 'the financial statements, prepared in accordance with the applicable set of accounting standards' (or 'UK-adopted IFRSs and FRS 101 respectively'); index rows citing UKLR 6.6.6R(1) for directors' interests and UKLR 6.6.6R(3) for [wording masked]. |
The rule
FCA Disclosure Guidance and Transparency Rules, DTR 4.1.12R(3)(a)
Version relied on: FCA Handbook, Disclosure Guidance and Transparency Rules sourcebook, as in force at the financial year end
the financial statements, prepared in accordance with the applicable set of accounting standards, give a true and fair view of the assets, liabilities, financial position and profit or loss of the issuer and the undertakings included in the consolidation taken as a whole
FCA UK Listing Rules, UKLR 6.6.1R(1) and (3)
Version relied on: FCA Handbook, UK Listing Rules (UKLR), in force from July 2024, as at the financial year end
a statement of the amount of interest capitalised by the group during the period under review, with an indication of the amount and treatment of any related tax relief
Why it applies here: label slips; the content each row points to is present.
Why it matters
Cosmetic; a reader checking the rule references or the accounting basis named in the responsibility statement is misdirected.
Exposure
Drafting slips only.
Our workings
the 2024 report says the Directors 'have [wording masked] Standard [n]', then confirms [wording masked] view' of the Company and the undertakings in the consolidation. The 2025 report repeats the confirmation. The Listing Rules index ([amount].148; [amount].159) lists directors' interests and [wording masked] under UKLR 6.6.1. UKLR 6.6.1R lists capitalised interest, long-term incentive schemes, waived emoluments and similar items; directors' interests and [wording masked] are UKLR 6.6.6R(1) and (3).
Management’s best defence, and our reply
The company could say that the confirmation follows common market wording and that the group statements, which dominate, are under UK-adopted IFRS, and that the index is a navigation aid only. That is fair as to impact, which is why the point is a drafting slip only; the words still describe the company statements on the wrong basis and the rule numbers are wrong.
The fix
- Reword the confirmation to 'prepared in accordance with the applicable set of accounting standards' and cite UKLR 6.6.6R(1) and 6.6.6R(3) in the index.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | 2024 report: the company financial statements are prepared under FRS 101 | Document | Annual Report 2024, page 154 |
| 2 | 2024 report: the confirmation names only UK-adopted IFRSs | Document | Annual Report 2024, page 154 |
| 3 | 2025 report: the same confirmation wording | Document | Annual Report 2025, page 168 |
| 4 | 2024 index: directors' interests (and going concern / viability) placed under UKLR 6.6.1 | Document | Annual Report 2024, page 148 |
| 5 | 2025 index: the same items placed under UKLR 6.6.1(1) and (3) | Document | Annual Report 2025, page 159 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.