3.03 Two different 2024 net debt figures: [amount] in the going concern statement, [amount] in the Finance Review, with no label on the basis
UK Company B · a UK-listed technology and logistics group · Presentation point
In brief
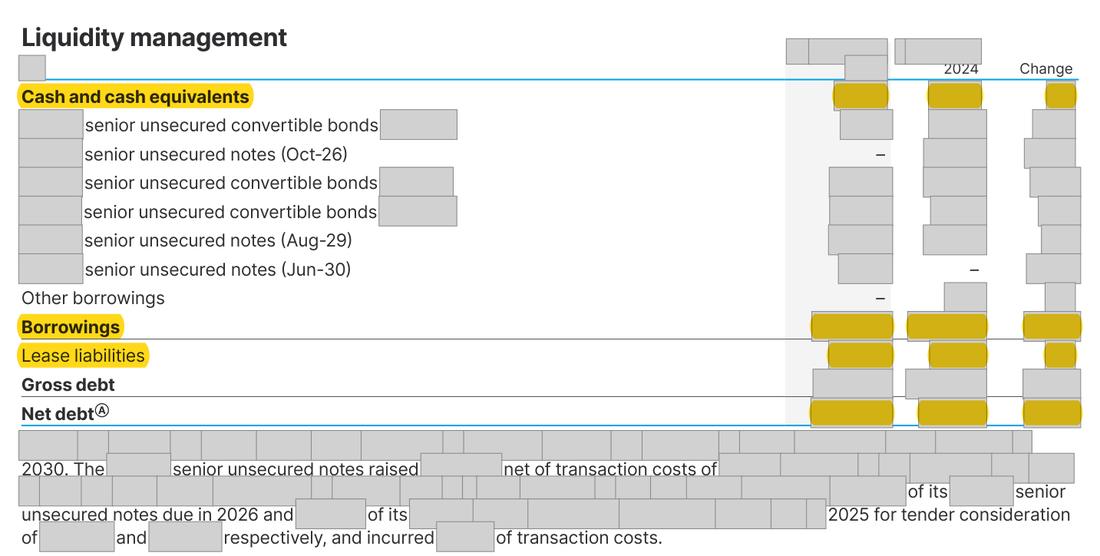
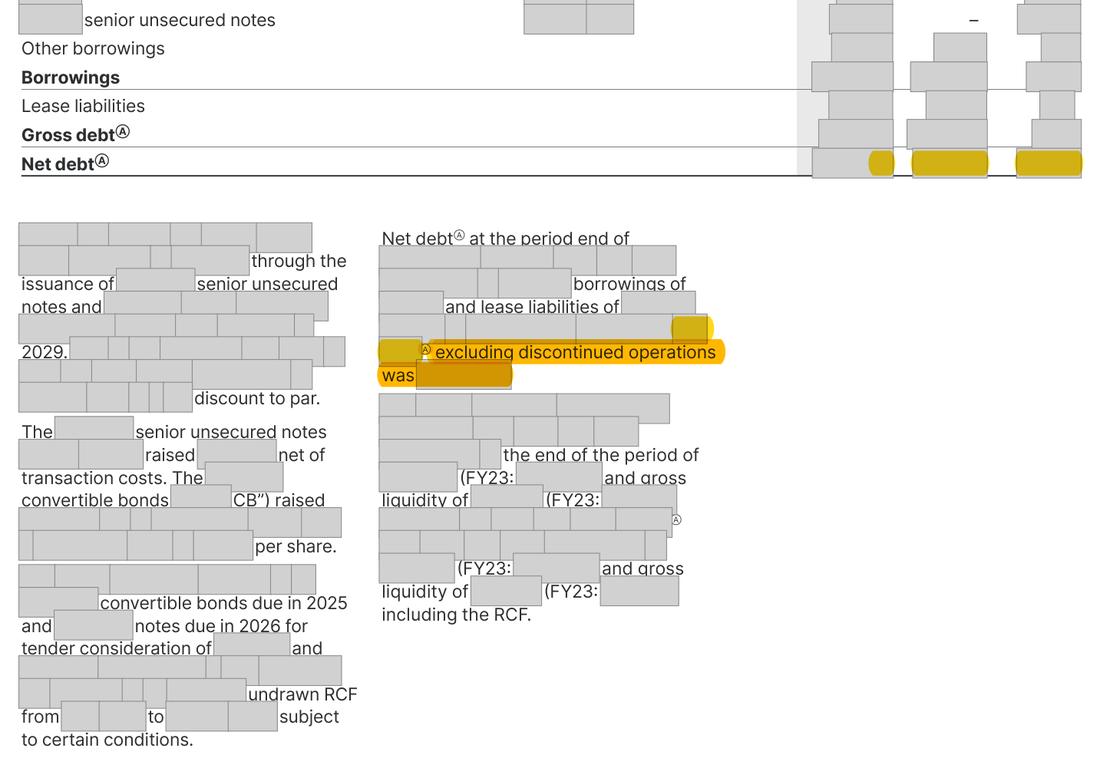
The going concern statement compares year-end net debt of [amount] with [amount] at the end of 2024, so net debt fell. The Finance Review compares the same [amount] with [amount] for 2024, so net debt rose by [amount]. The [amount] is the 2024 figure excluding discontinued operations, but the 2025 report labels it simply 'net debt' and never says so. The 2024 report itself shows both figures for 2024 net debt without a basis label (both years).
The evidence, as filed
Further pages withheld to protect the company’s identity (eight): Annual Report 2025, page 95; Annual Report 2025, page 27; Annual Report 2024, page 226; Annual Report 2024, page 208; Annual Report 2024, page 240; Annual Report 2025, page 271; Annual Report 2024, page 239; Annual Report 2025, page 272. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows p.95: net debt [amount] against [amount] at the end of FY24; pp.27 and [n]: net debt [amount] against FY24 [amount], change [amount], both labelled 'Net debt' with no basis note. | What the rule requires One 2024 net debt figure under the 'Net debt' label, or the [amount] labelled 'excluding discontinued operations' with a bridge to the [amount] in Note 4.2. |
The rule
ESMA Guidelines on Alternative Performance Measures, paragraph 41 (consistency)
Version relied on: ESMA Guidelines on Alternative Performance Measures, ESMA/2015/1415, published October 2015, applying from July 2016; the FCA expects UK issuers to continue to apply them after EU exit
The definition and calculation of an APM should be consistent over time. In exceptional circumstances where issuers or persons responsible for the prospectus decide to redefine an APM, the issuer should: i. Explain the changes
Why it applies here: a reader comparing the going concern statement with the Finance Review gets opposite directions for the year's movement in net debt, and nothing in the 2025 report reconciles the two.
Why it matters
Readers comparing the going concern statement with the Finance Review see net debt falling in one place and rising in the other, with no reconciliation in the 2025 report.
Exposure
A presentation point; the audited Note 4.2 is internally consistent. An FRC Corporate Reporting Review could ask for the basis to be labelled.
Our workings
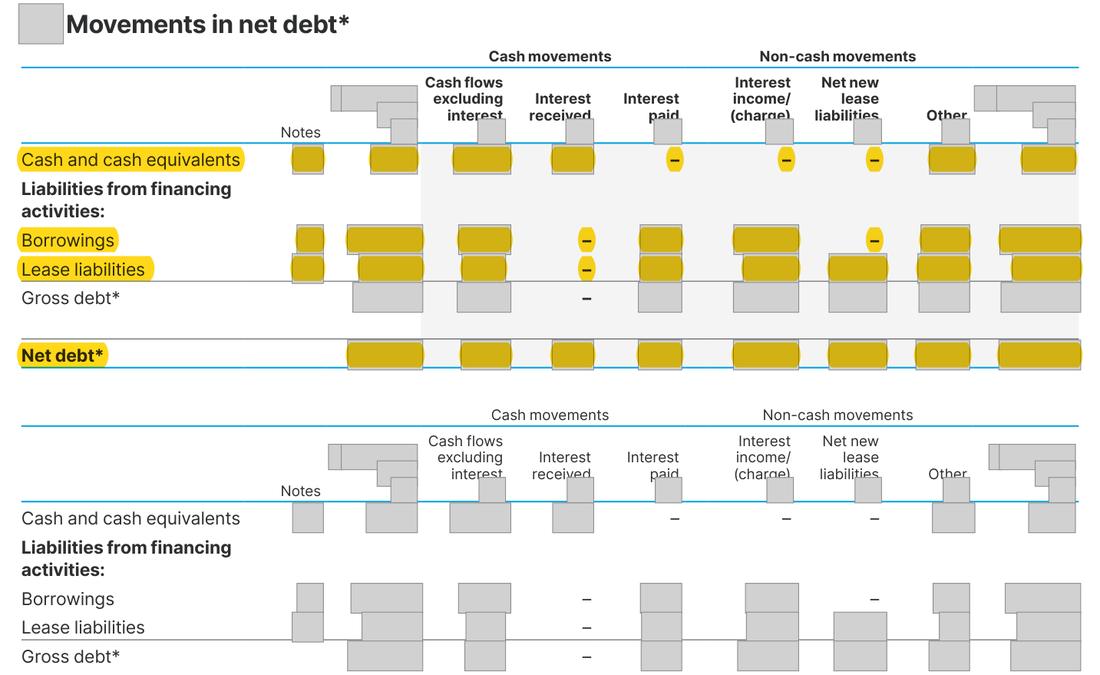
the going concern statement on p.95 gives 2024 net debt of [amount], which is the total-group figure in Note 4.2 ([amount]) and in the capital-management note. The Finance Review on p.27 and its liquidity table on p.43 give 2024 net debt of [amount] and show net debt up [amount] in the year. The 2024 report explained that [amount] was 'net debt excluding discontinued operations', the total-group figure being [amount]. The 2025 report keeps the [amount] in its Finance Review but drops the qualifier; the only basis statement in the report (Note 4.2) says the [date] net debt includes the disposal group.
the gap is [amount], made up of lease liabilities of [amount] and borrowings of [amount] less cash of [amount] relating to the business that was being sold. Measured on the total-group basis net debt fell by [amount]; on the Finance Review basis it rose by [amount].
| Item | Arithmetic | Result (£m) |
|---|---|---|
| Gap between the two 2024 net debt figures | [n] - [n] | [n] |
| Of which lease liabilities | [n] - [n] | [n] |
| Of which borrowings | [n] - [n] | [n] |
| Of which cash (reduces net debt) | [n] - [n] | [n] |
| Check | [n] + [n] - [n] | [n] |
| Movement on the total-group basis (fall) | [n] - [n] | [n] |
| Movement on the Finance Review basis (rise) | [n] - [n] | [n] |
Management’s best defence, and our reply
Management would say the Finance Review deliberately shows 2024 on a continuing-operations basis so that the year-on-year movement is comparable after the loss of control of the retail subsidiary, and that the [amount] was published and explained in the 2024 report. The going concern statement, they could add, uses the total-group figure that ties to the audited note. That explains why two bases exist; it does not explain why the 2025 report prints the narrower figure under the plain 'Net debt' label with no qualifier, while its own note defines the 2024 figure to include the disposal group. A reader of the 2025 report alone cannot tell which figure is which.
The fix
- In the Finance Review label the 2024 comparative 'net debt excluding discontinued operations (FY24 total Group: [amount])', or use the total-group figure, so that p.27, p.43 and p.95 tie.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Going concern statement: 2024 net debt [amount] | Document | Annual Report 2025, page 95 |
| 2 | Finance Review headline: 2024 net debt [amount], no basis label | Document | Annual Report 2025, page 27 |
| 3 | Liquidity table: 2024 lease liabilities exclude the disposal group | Document | Annual Report 2025, page 43 |
| 4 | Liquidity table: 2024 borrowings exclude the disposal group | Document | Annual Report 2025, page 43 |
| 5 | Liquidity table: 2024 cash excludes the disposal group | Document | Annual Report 2025, page 43 |
| 6 | Liquidity table: net debt shown rising by [amount] | Document | Annual Report 2025, page 43 |
| 7 | Note 4.2: net debt falls from [amount] to [amount] | Document | Annual Report 2025, page 234 |
| 8 | Note 4.2: 2024 lease liabilities [amount] | Document | Annual Report 2025, page 234 |
| 9 | Note 4.2: 2024 borrowings [amount] | Document | Annual Report 2025, page 234 |
| 10 | Note 4.2: 2024 cash [amount] | Document | Annual Report 2025, page 234 |
| 11 | The only basis statement in the 2025 report: the 2024 net debt includes the disposal group | Document | Annual Report 2025, page 234 |
| 12 | 2024 report: [amount] was the figure excluding discontinued operations | Document | Annual Report 2024, page 40 |
| 13 | Capital management note defines gross debt by the balance sheet borrowings and lease liabilities | Document | Annual Report 2024, page 226 |
| 14 | The same paragraph prints net debt of [amount] | Document | Annual Report 2024, page 226 |
| 15 | The [amount] includes disposal-group cash, borrowings and lease liabilities that the balance sheet shows within held-for-sale items | Document | Annual Report 2024, page 208 |
| 16 | Net debt on the balance-sheet lines is [amount] | Document | Annual Report 2024, page 208 |
| 17 | The 2024 report's alternative performance measures section defines net debt only on the Total Group basis. | Document | Annual Report 2024, page 240 |
| 18 | The list of measures in the 2024 report names net debt once and has no 'net debt excluding discontinued operations'. | Document | Annual Report 2024, page 239 |
| 19 | The 2024 Financial Review also gives a second net debt measure, excluding discontinued operations, of [amount]. | Document | Annual Report 2024, page 40 |
| 20 | The Total Group net debt at [date] in the same Financial Review is [amount]. | Document | Annual Report 2024, page 40 |
| 21 | The APM section gives 2024 gross debt of [amount], the basis of the [amount] net debt | Document | Annual Report 2025, page 271 |
| 22 | The APM definition of net debt points to the note that gives the [amount] figure; no APM defines a net debt excluding discontinued operations | Document | Annual Report 2025, page 272 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.