7.05 Drafting slips: period statements headed 'As at', a key audit matter pointing to the wrong note and standard, a stale committee badge and a misspelt shareholder
UK Company C · an AIM-quoted scientific instruments group · Drafting slip
In brief
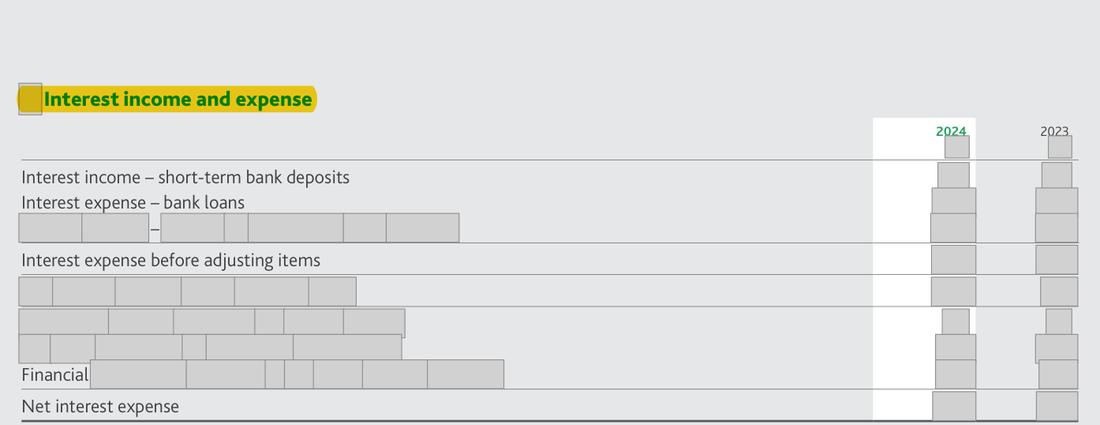
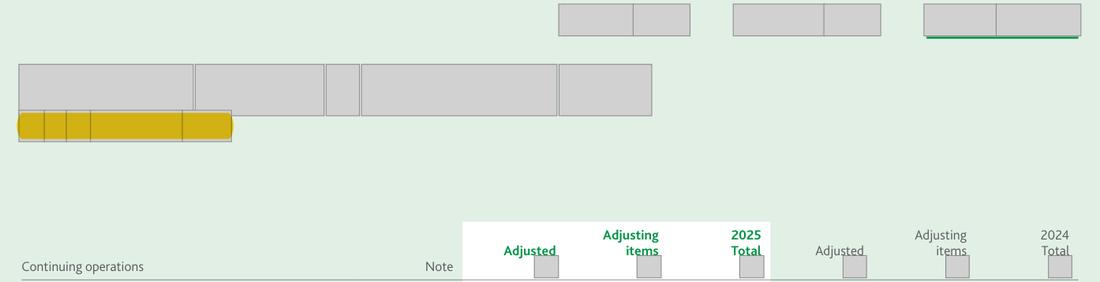
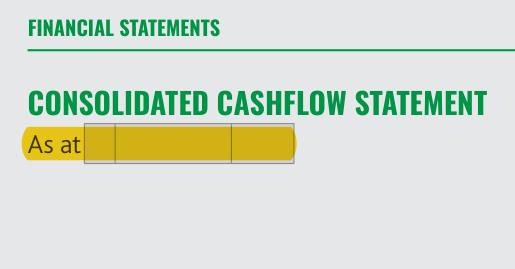
The income statement and cash flow statement, which cover a year, are headed 'As at [date]' (the 2025 income statement and cash flow statement repeat this). In the auditor's report, the key audit matter on acquired intangibles points to note 9, which is the interest note (acquisitions are note [n]), and the goodwill matter tests cash-generating units against IAS 38 rather than IAS 36. The board page still shows the new Chair with a Remuneration Committee badge although he left that committee at [date], and the shareholder table spells '[name]'.
The evidence, as filed
Further pages withheld to protect the company’s identity (seven): Annual Report 2024, page 67; Annual Report 2024, page 63; Annual Report 2024, page 62; Annual Report 2024, page 44; Annual Report 2024, page 52; Annual Report 2024, page 48; Annual Report 2024, page 56. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
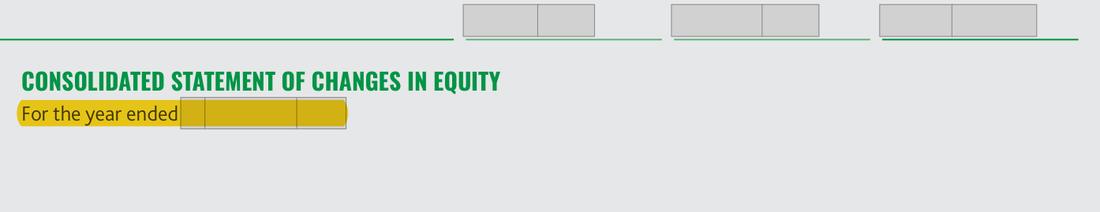
| What the annual report shows 'As at [date]' on the income statement and cash flow; 'outlined in note 9' for acquired intangibles; 'criteria of IAS 38' for cash-generating units; Remuneration Committee badge for a director who stepped down; '[name]'. | What the rule requires 'For the year ended [date]'; 'note [n]'; 'IAS 36'; no Remuneration Committee badge; '[name]'. |
Why it matters
No figure is affected; the slips reduce the polish of the audited statements and the governance pages.
Exposure
None.
Our workings
Each slip was confirmed on the page image. The statement of changes in equity is correctly headed 'For the year ended [date]', so the 'As at' headings on the two other period statements are inconsistent. Note 9 is 'Interest income and expense'; the acquisitions and their intangible assets are in note [n]. Cash-generating units are defined and tested under IAS 36, not IAS 38. The corporate governance statement and the remuneration report say each committee has three non-executive members and that the Chair stepped down from the Remuneration Committee at [date], but the board page, dated after that, still gives him the committee badge, so four directors carry it. None of these changes a figure.
Management’s best defence, and our reply
The company would say the headings, badge and spelling are cosmetic and the auditor's wording is the auditor's own. That is accepted, which is why these are listed as drafting slips only.
The fix
- Head the income and cash flow statements 'For the year ended [date]'; ask the auditor to correct the note and standard references; remove the stale committee badge; correct the shareholder's name.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | the income statement for the year is headed 'As at' | Document | Annual Report 2024, page 67 |
| 2 | the cash flow statement for the year is headed 'As at' | Document | Annual Report 2024, page 70 |
| 3 | the statement of changes in equity uses the correct period heading | Document | Annual Report 2024, page 69 |
| 4 | the 2025 income statement repeats the heading | Document | Annual Report 2025, page 65 |
| 5 | the acquired-intangibles key audit matter points to note 9 | Document | Annual Report 2024, page 63 |
| 6 | note 9 is the interest note, not acquisitions | Document | Annual Report 2024, page 79 |
| 7 | cash-generating units said to be assessed against IAS 38 | Document | Annual Report 2024, page 62 |
| 8 | the Chair is shown with Audit and Remuneration Committee badges | Document | Annual Report 2024, page 44 |
| 9 | he left the Remuneration Committee at the year end | Document | Annual Report 2024, page 52 |
| 10 | each committee has three members, but four directors carry the Remuneration Committee badge | Document | Annual Report 2024, page 48 |
| 11 | shareholder name misspelt | Document | Annual Report 2024, page 56 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.