7.04 Six drafting slips in the 2024 strategic report
UK Company C · an AIM-quoted scientific instruments group · Drafting slip
In brief
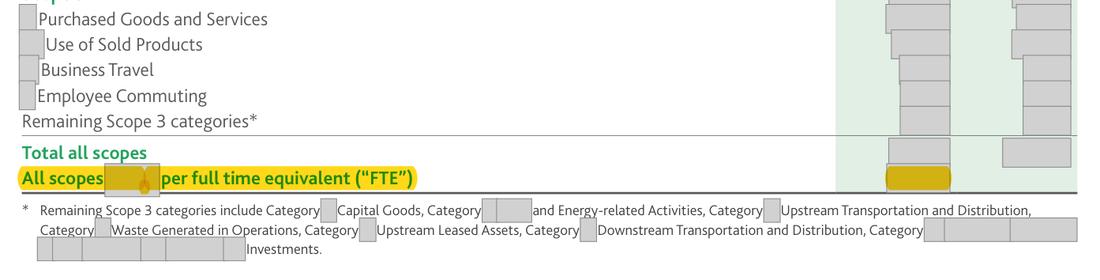
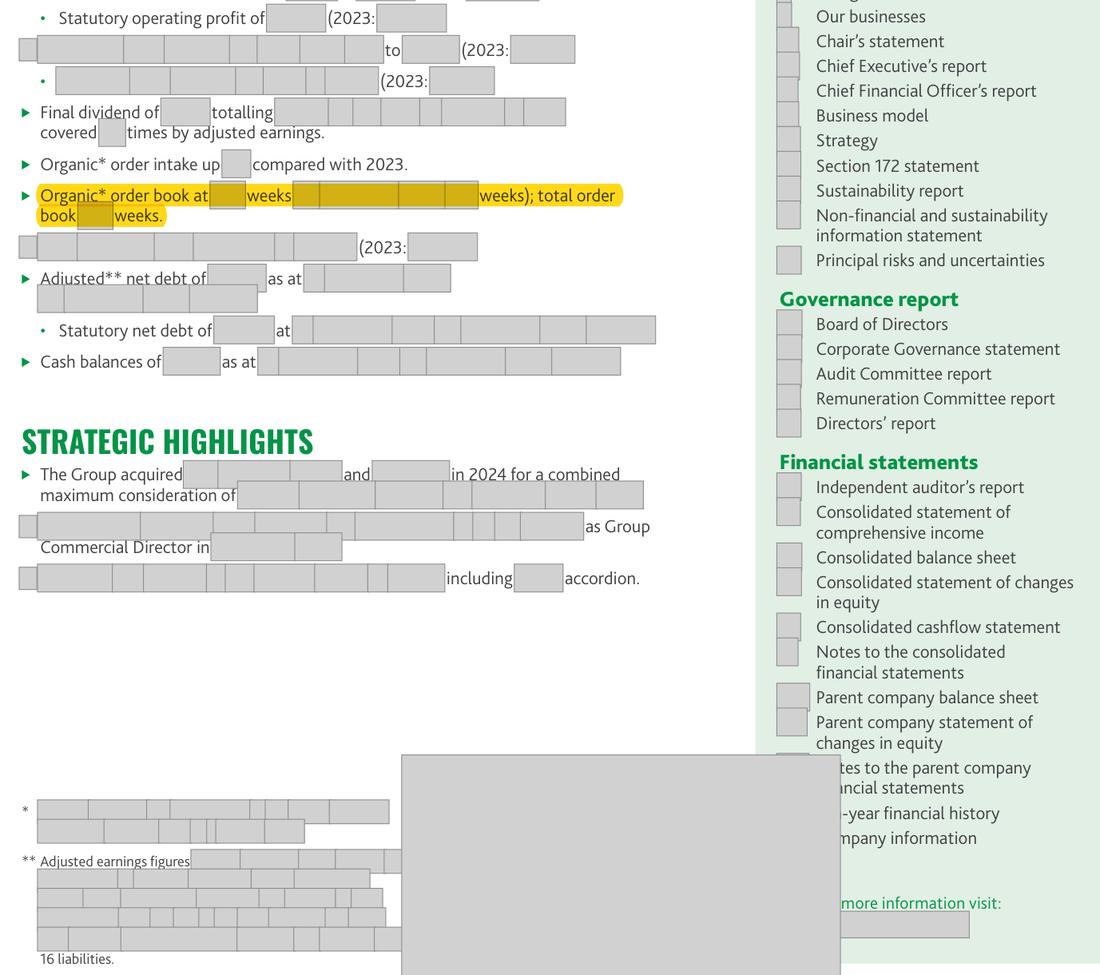
Six slips in the 2024 strategic report: the organic order book at [date] is [n] weeks on p.1 but [n] weeks on p.18; the facility amendment is dated [date] on p.16 and [date] on p.20; the section 172 statement sends readers to the Sustainability Report on 'pages 21 to 31' (it starts on p.24); the market-based emissions chart on p.30 is labelled 2023 and 2022 beside a table for 2024 and 2023; Table 7 prints all-scopes emissions per FTE as [n] where Table 9 gives [n]; and the climate statement refers to the risks 'in Tables 2 and 3' where the risk tables are Tables 3 and 4.
The evidence, as filed
Further pages withheld to protect the company’s identity (twelve): Annual Report 2025, page 14; Annual Report 2024, page 18; Annual Report 2025, page 20; Annual Report 2024, page 16; Annual Report 2025, page 69; Annual Report 2024, page 20; Annual Report 2024, page 23; Annual Report 2025, page 24; Annual Report 2024, page 30; Annual Report 2025, page 25; Annual Report 2024, page 41; Annual Report 2024, page 35. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows p.1 '[date]: [n] weeks' / p.18 '[date]: [n] weeks'; p.16 'On [date]' / p.20 'On [date]'; p.23 'pages 21 to 31'; p.30 chart years 2023 and 2022; p.40 '[n]'; p.35 'Tables 2 and 3'. | What the rule requires One order book figure for [date]; one facility date; 'pages 24 to 31'; chart years 2024 and 2023; '[n]' tCO2e per FTE; 'Tables 3 and 4'. |
What we checked: Each statement read on the page image and compared with the other page that gives the same item (contents list p.1, Table [amount].41, Table [amount].34).
Why it matters
Readers meet two values for the same measure or a wrong pointer; no audited amount is affected.
Exposure
No penalty.
Our workings
each pair of pages gives a different value or reference for the same item, as quoted in the evidence rows. None of the slips changes an audited figure; the facility date ([date] in note [n]) and the emissions intensity ([n] in Table 9) are given elsewhere in the same report; which of the two order book figures is right cannot be told from the report.
Management’s best defence, and our reply
The company could say each slip is obvious from its context and that the correct value is given elsewhere in the report. That is right, which is why these are listed as drafting points only.
The fix
- Read '[n] weeks' (or '[n] weeks') consistently, give one facility date, 'pages 24 to 31', chart years 2024 and 2023, '[n]' and 'Tables 3 and 4'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Highlights: [date] organic order book [n] weeks | Document | Annual Report 2024, page 1 |
| 2 | CFO report: the same measure at [n] weeks | Document | Annual Report 2024, page 18 |
| 3 | Chief Executive's report dates the facility amendment [date] | Document | Annual Report 2024, page 16 |
| 4 | CFO report dates it [date] | Document | Annual Report 2024, page 20 |
| 5 | Section 172 statement cross-reference starts at p.21 (the business model page) | Document | Annual Report 2024, page 23 |
| 6 | The same page gives the correct range | Document | Annual Report 2024, page 23 |
| 7 | Chart years read 2023 and 2022 while the table beside it is for 2024 and 2023 | Document | Annual Report 2024, page 30 |
| 8 | Table 7 prints [n] | Document | Annual Report 2024, page 40 |
| 9 | Table 9 gives the same 2023 intensity as [n] | Document | Annual Report 2024, page 41 |
| 10 | The risk tables are Tables 3 and 4; Table 2 is the scenario table | Document | Annual Report 2024, page 35 |
| 11 | The 2025 Chief Executive's report compares 2025 with itself; the comparison year should be 2024 | Document | Annual Report 2025, page 14 |
| 12 | The restatement is said to be explained in 'note [n] to this announcement': wording carried over from the results announcement | Document | Annual Report 2025, page 20 |
| 13 | In the Annual Report the restatement is explained within note 2 (accounting policies) | Document | Annual Report 2025, page 69 |
| 14 | Note 10 of the Annual Report is the taxation note, not the restatement | Document | Annual Report 2025, page 80 |
| 15 | The 2025 section 172 statement repeats the 2024 wording and year | Document | Annual Report 2025, page 24 |
| 16 | The cross-reference gives pages 22 to 32 | Document | Annual Report 2025, page 24 |
| 17 | The Sustainability Report begins on p.25, as the contents page and the other references on p.24 say | Document | Annual Report 2025, page 25 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.